
BHP Group And 2 Other Fully Franked Dividend Stocks To Own
Rising expectations of another Federal Reserve rate hike in December have sharpened the focus on dependable income. Higher borrowing costs can pressure growth stories, yet they often push investors toward companies that already return solid cash to shareholders. Fully taxed Australian dividends become especially interesting in that context. This article highlights three ASX stocks from a curated income list that prioritises consistent franked payouts and balance sheet strength.
The three stocks below are a sample from the wider income list, and the full screen surfaces 17 more fully franked dividend shares with similarly compelling stories that are not covered here.
Head straight into the Best ASX Fully Franked Dividend Shares screener to identify, analyse, and focus on the highest conviction fully franked dividend opportunities for your portfolio.
BHP Group (ASX:BHP)
Overview: BHP Group is a global resources producer, with iron ore and copper generating much of the free cash flow that supports fully franked dividends.
Operations: BHP generated about US$29b from copper, US$23.9b from iron ore and US$5.6b from coal, with China its largest market.
Market Cap: A$300.9b
BHP Group matters for this income-focused list because its core iron ore and copper operations help underpin the fully franked dividend stream that SMSF and yield-hunting investors care about. The analyst consensus Narrative on Simply Wall St frames how its growth projects could influence those cash flows over time.
"A strong pipeline of copper and potash projects positions BHP Group to benefit from a global surge in decarbonization efforts and electrification initiatives, with rising demand for critical minerals expected to influence future revenues."
What investors really need to watch now is how one unresolved pressure on future project economics shapes the headroom for margins and ongoing payouts.
That margin question is the real hinge for income investors, and the full narrative for BHP Group spells out how BHP Group's project mix could accelerate or cap future payout capacity.

Fortescue (ASX:FMG)
Overview: Fortescue is a Perth based miner whose iron ore exports generate the bulk of the free cash flow funding fully franked dividends.
Operations: Fortescue reports about $16.8b from Metals and $136m from Energy, with roughly $15.1b of revenue tied to China and $1.9b elsewhere.
Market Cap: A$47b
For income focused investors, Fortescue matters because its Pilbara iron ore engine still funds the fully franked dividends. The analyst consensus Narrative on Simply Wall St sets out how decarbonisation projects could reshape earnings power behind those payouts.
"Accelerating rollout of Fortescue’s Real Zero by 2030 program, including large scale renewables, storage and electric mobile equipment, is already cutting power costs at Eliwana and Iron Bridge and can further support net margins as diesel use is reduced and fuel savings accumulate."
What could really move the dial for Fortescue’s dividend comfort is how one unseen cost pressure tracks against those planned efficiency gains.
That hidden cost curve is exactly what the full narrative for Fortescue unpacks, showing where Fortescue’s decarbonisation spend could accelerate returns from its existing iron ore engine.

nib holdings (ASX:NHF)
Overview: nib holdings is a health insurer and related services group whose Australian residents policies provide much of the cash backing fully franked dividends.
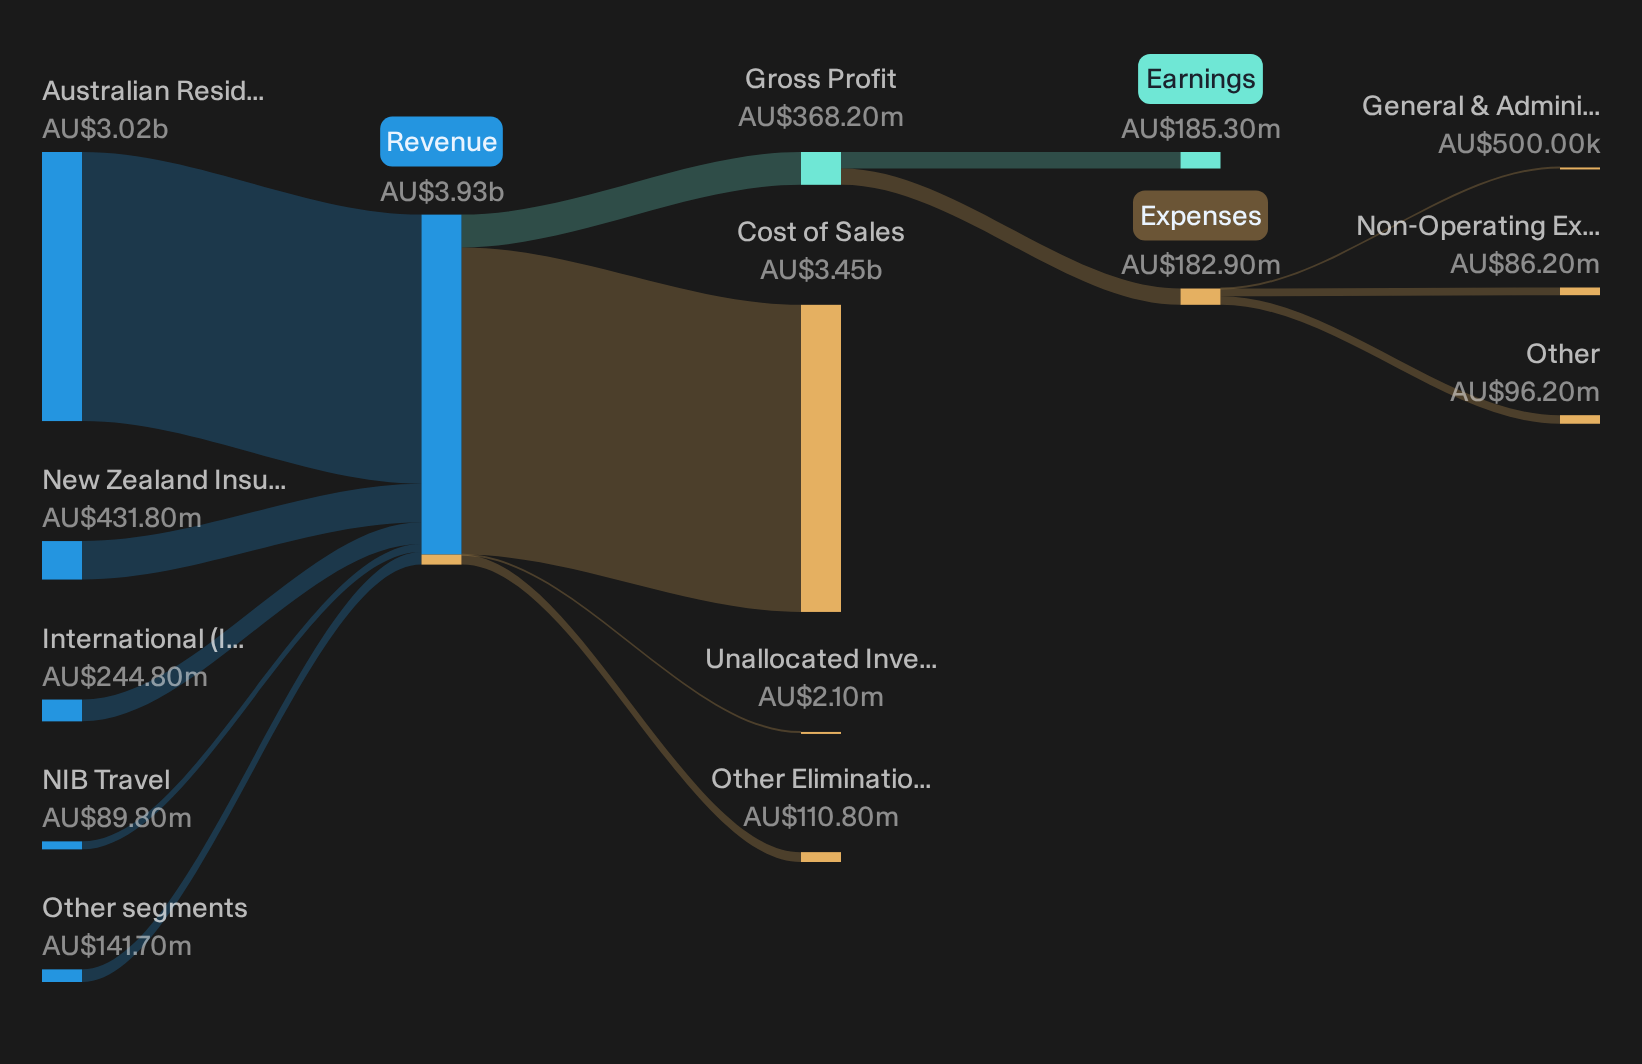
Operations: The business generates most of its A$3.9b revenue from Australian Residents Health Insurance at A$3.0b, with further income from New Zealand, international, travel and services segments.
Market Cap: A$3.3b
For income-focused investors, nib holdings matters because its Australian Residents Health Insurance arm anchors distributable profits. The analyst consensus Narrative on Simply Wall St highlights growing digital efficiency and a broader earnings mix as factors that may help support those fully franked distributions.
"Accelerated digital transformation through AI and machine learning initiatives is now visible in cumulative productivity savings of A$79 million since FY24, an operating expense ratio of 16.6% in FY26 and more than 86% of Australian residents claims processed automatically, which supports further improvement in net margins and earnings as these tools scale across nib holdings."
What really shapes nib holdings’ income appeal now is how one evolving pressure on claims and capital settings ultimately filters through to dividend headroom.
As that pressure builds, the full narrative for nib holdings shows how nib holdings could balance claims, capital needs and dividend ambition as digital gains keep accelerating.
Seeking Alternatives Beyond Fully Franked Dividends
Fresh ideas move first. Markets reward the investors who spot quiet momentum before it starts flying and stale data spreads. Scan new opportunities while it matters and act now.
- Track resilient income candidates before yield hunters crowd in by scanning the 4 dividend fortresses that prioritises durable payouts and balance sheet strength.
- Identify early-stage stories with real balance sheet support using the curated 17 elite penny stocks with strong financials set that filters for quality, not just hype.
- Consider positioning ahead of potential infrastructure momentum with the focused 42 power grid technology and infrastructure stocks collection, built around businesses exposed to grid upgrades and electrification trends.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com