
Is UDR (UDR) A Bargain After Its Profit Jump?
UDR earnings move shifts investor focus to profitability
UDR (UDR) has drawn fresh attention after reporting third quarter and nine month 2026 results, with net income and earnings per share much higher than a year earlier despite largely unchanged revenue.
At a share price of US$36.58, UDR has climbed with a 1 month share price return of 7.21%, while the 1 year total shareholder return of 10.13% and 3 year total shareholder return of 29.00% point to gradually improving momentum. However, the 5 year total shareholder return is still down 21.65% as investors reassess profit quality after the latest earnings jump.
Scan how UDR's earnings shift compares with other real estate players by reviewing our curated list of list of solid balance sheet and fundamentals (25 results).
Profit has surged while UDR's revenue held steady, and the share price has already reacted. Does the current valuation still leave enough upside to justify the risks from here?
Most Popular Narrative: 8% Undervalued
On the analyst consensus Narrative on Simply Wall St, UDR's fair value of $39.64 sits above the last close of $36.58. This frames the latest earnings jump inside a still cautious long term earnings outlook that is built into that model.
Ongoing capital recycling from roughly US$650 million of older, lower rent properties sold or under contract at mid 5% cap rates into share repurchases at an implied mid 6% cap rate and future higher growth assets can shift UDR’s mix toward properties with stronger rent potential and support earnings per share.
See why 10 investors see UDR as 8% undervalued.
Result: Fair Value of $39.64 (UNDERVALUED)
Still, pressure on Sunbelt rents and ongoing regulatory and legal scrutiny around pricing tools could easily upset the current UDR upside story.
Find out about the key risks to this UDR narrative.
Another view on UDR's valuation
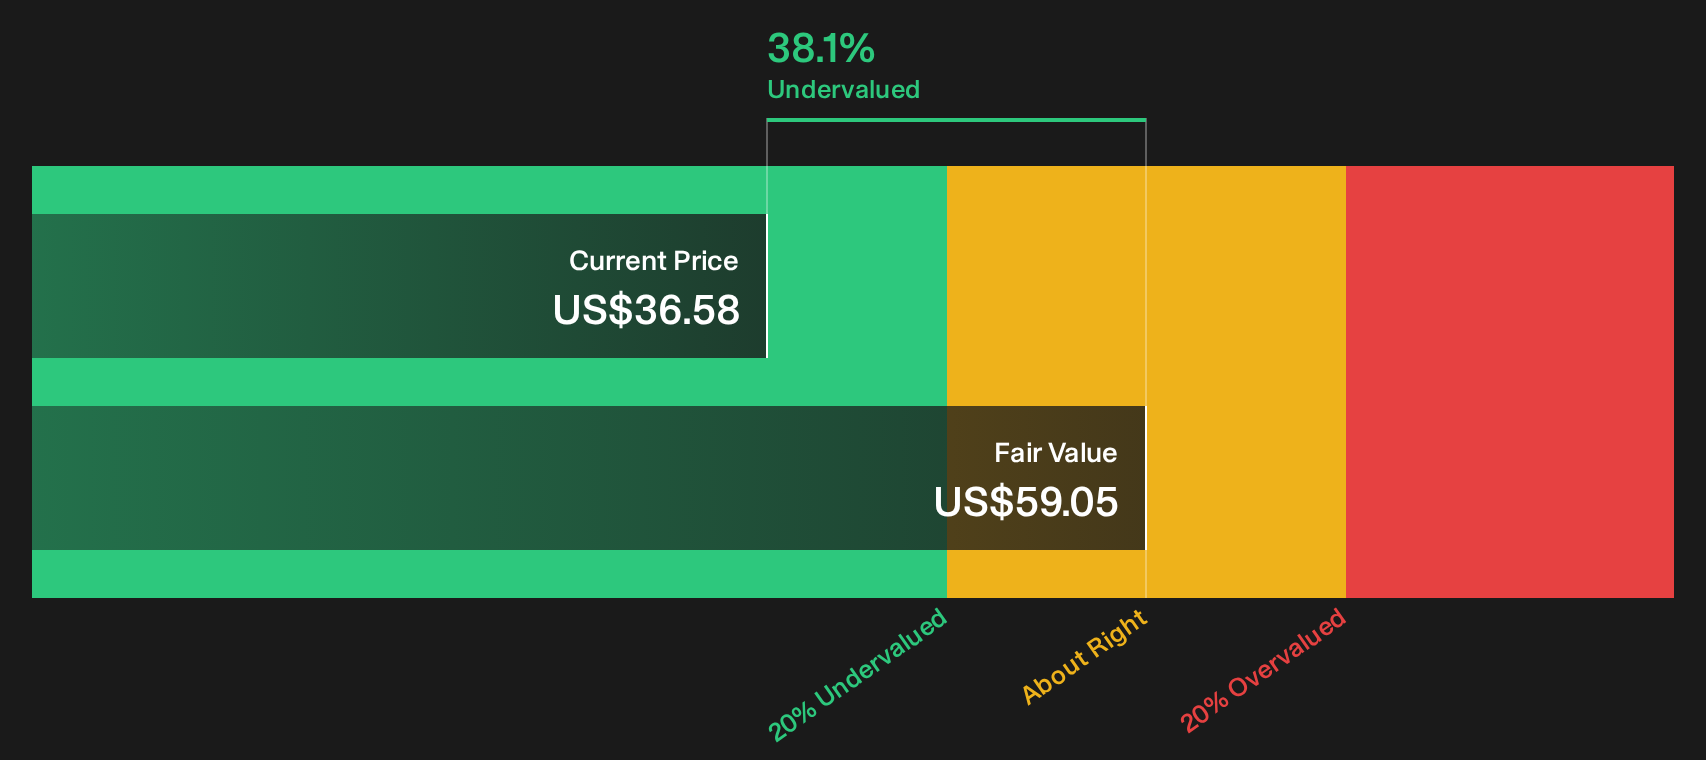
UDR looks inexpensive on future cash flows, with our DCF model suggesting the shares trade about 38.1% below an estimated value of $59.05. That sits uneasily beside analyst forecasts that point to shrinking earnings. Which story do you think better reflects the next few years?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals or fresh opportunity, you will need to move past the headline and weigh UDR's improving earnings against both the concerns and the potential rewards. To pressure test your own thesis against the key pros and cons, take a closer look at the 3 key rewards and 3 important warning signs.
Looking beyond UDR for your next move?
If UDR has sharpened your thinking, do not stop here. Broader idea hunting with a focused screener can sharpen your portfolio and reveal fresh possibilities.
- Target potential bargains by scanning companies that pass tight quality checks and valuation filters through our 40 high quality undervalued stocks.
- Prioritize resilience by reviewing a 31 resilient stocks with low risk scores that highlights businesses with more stable profiles and fewer red flags.
- Hunt for fresh stories using a 19 high quality undiscovered gems that surfaces under-the-radar opportunities before they gain wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com