
What ASM International Buyers Were Betting On
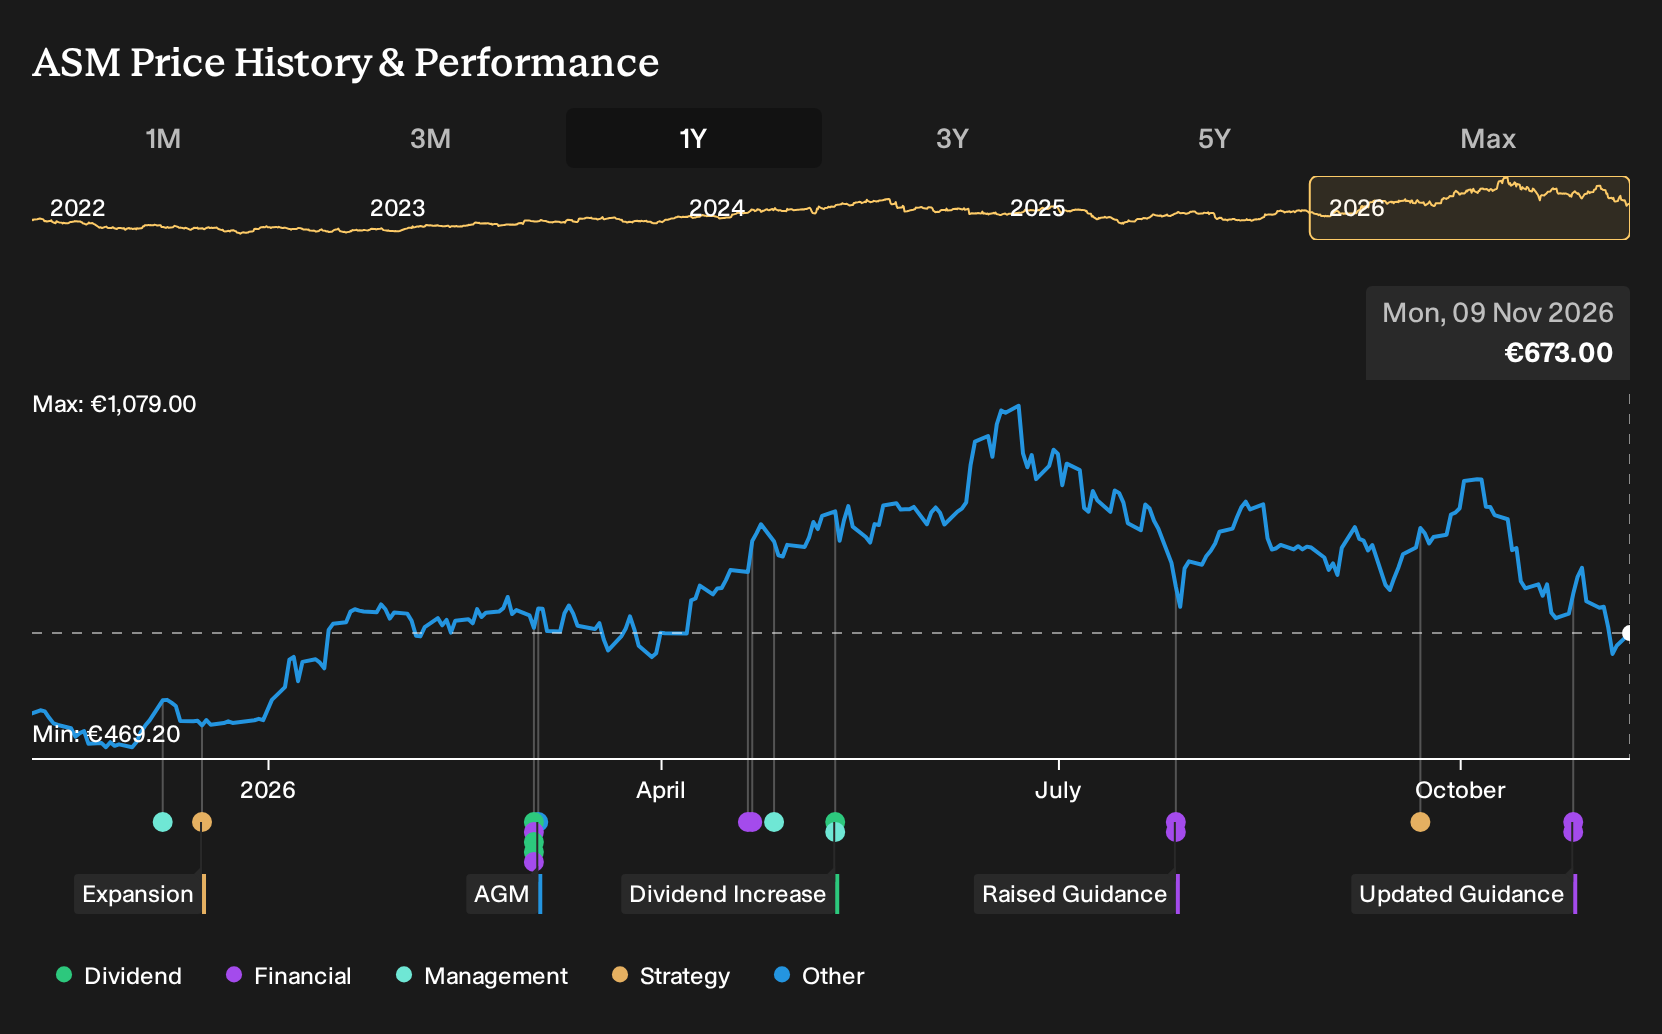
If you had bought ASM International on 9 November 2025, you were stepping into a debate between analysts lifting fair value on strong AI and gate all around exposure, and skeptics focused on China risk, customer dependence and rising costs. For ASM International shareholders, the return over the past year was 26.2%, including dividends. If you faced that choice again, how much weight would you give to margin pressure versus advanced node momentum?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
ASM International has already moved. Pinpoint other ways to investigate the theme among 53 AI infrastructure stocks.
The Two Narratives Investors Had To Weigh On ASM International
The shares cost €527 at the start of the period. ASM International sat between two well defined stories about what might come next.
The bullish narrative saw fair value at €571, 8% above the start price, built on assumed 12.0% annual revenue growth and profit margins reaching 24.3% within three years as advanced deposition tools fed AI and gate all around demand.
The bearish case put fair value at €440, 16% below the start price, and focused on geopolitical risk, higher compliance and R&D costs, and dependence on a small group of major customers.
What The Results Put To The Test For ASM International
ASM International reported Q3 2026 revenue of €1.159b compared with €800m in Q3 2025, which supported the optimistic case about AI and advanced node demand. Net income excluding extra items fell from €384.2m to €308.1m and the net margin moved from 48.0% to 26.6%, so profitability strength looked closer to the cautious view. Overall, the evidence cut both ways.
The key assumption investors needed to watch was margin resilience. For any similar stock, track how net margin and absolute profit move in relation to bullish revenue stories in quarterly results, especially when growth comes from capital intensive segments.
What ASM International's Price Now Asks You To Believe
ASM International shares now trade at €673, up 26.2% over the past year from €527. The bearish analyst Narrative on Simply Wall St still places its Fair Value above the current price, based on its own modelling of future earnings, margins and risks.
The Narrative leans on AI linked node transitions, memory roadmaps and services to carry more of the load than China or legacy markets. It argues today's price does not yet fully credit the possibility that high margin tools and service contracts offset weakness in more cyclical areas.
"The main thing that has to go right is that AI-driven node transitions, DRAM roadmaps and adjacent process and packaging products generate enough high-margin tool and services revenue to offset a double-digit decline in China and a prolonged downturn in power and analog markets."
The price and this Narrative do not agree. → Uncover what this Narrative says ASM International is actually worth
How Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 36% below our estimate - leans on long term service contracts that renew steadily as infrastructure ages.
- Company 2 - 20% below our estimate - turns alignment with a single software partner into repeat cloud and AI projects.
- Company 3 - 49% below our estimate - scales an asset light hotel network while a retail side business grows.
Those are three of them. See the full list of 218 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com