
How Emerging Markets Demand At Ninety One Group Shares Has Changed Its Investment Story
- Ninety One Group is in focus after commentary on its diversified asset management platform, including infrastructure related debt mandates and exposure to emerging markets credit.
- The discussion around UK utility debt stress highlights how Ninety One Group’s infrastructure credit exposure could influence demand for its higher margin mandates.
- We will examine how Ninety One Group’s broader investment narrative relates to renewed interest in emerging markets and infrastructure credit.
Scan the wider opportunity set by comparing Ninety One Group’s infrastructure and emerging markets angle with a curated list of 42 power grid technology and infrastructure stocks that are poised to benefit from long term capital flows into essential assets.
Ninety One Group Investment Narrative Recap
To own Ninety One Group, an investor needs to be comfortable with a fee based model that relies on stable assets under management and disciplined cost control. The analyst consensus Narrative on Simply Wall St leans on steady earnings growth near 6% a year, supported by emerging markets and fixed income mandates. Recent discussion around infrastructure credit and UK utility debt stress does not yet look like a material break in that story, but it does sharpen focus on credit underwriting and client appetite.
The key short term swing factor remains flows into higher margin strategies, particularly active emerging markets and select credit products. The main operational risk stays the same, structural fee pressure around the 38% to 40% management fee rate guidance combined with rising investment in technology, AI and new offices. If flows soften or costs bite harder while sentiment toward infrastructure credit turns cautious, Ninety One Group’s margins could come under pressure even if assets under management hold up.
The most relevant backdrop to this credit focused news is Ninety One Group’s earlier addition of £18.3b of predominantly lower fee fixed income mandates from the Sanlam transaction. Management has framed this, within the analyst consensus Narrative on Simply Wall St, as a margin stabiliser because the mandates are meant to bring more predictable assets and help smooth earnings. Against renewed questions about infrastructure and utility debt, that ballast looks operationally important even though it does not fully insulate higher margin strategies.
For catalysts, that same Sanlam relationship also broadens distribution for Ninety One Group’s emerging markets and credit capabilities. If clients use the platform to access more specialised infrastructure or emerging markets debt funds, that could support mix and fee levels despite headline fee compression. The risk is that any prolonged period of stress in infrastructure credit or UK utilities makes institutions more cautious on complex credit products, which might slow the shift into higher fee mandates the business is aiming for.
Ninety One Group Forecasts and Valuation Anchors
Ninety One Group's current analyst framework rests on a fee based model that is expected to support mid single digit top line expansion, while the business leans into emerging markets and credit. Analysts in the Simply Wall St report are working off an assumption of 6.8% yearly revenue growth over the next few years and profit margins edging from 23.6% today to 23.9% by year three. Earnings today are cited at £153.5 million, with a consensus forecast of £189.1 million by around 2029, which implies an earnings increase of roughly £35.6 million if those numbers play out. That trajectory sits inside a wider range, since the more optimistic forecasts point to earnings of up to £209.8 million, which underlines how sensitive the story is to flows into higher fee strategies and the behaviour of infrastructure and emerging markets credit.
The same analyst pack pins 2029 revenues at £791.8 million and earnings at £189.1 million, and then tests what sort of valuation multiple investors would effectively be underwriting. On those figures, the implied P/E ratio is 20.1x in 2029 compared with 12.8x today, while the wider GB Capital Markets group is quoted at 12.1x. Forecasters are also building in share count growth of 7.0% a year for the next three years, which matters because it influences how much of the earnings pool accrues to each share, even if total profit moves higher. Taken together, the revenue, margin and share assumptions explain why the consensus target links back to both the resilience of Ninety One Group’s infrastructure credit mandates and the ability to keep sourcing higher quality emerging markets assets under management.
Ninety One Group's narrative projects £791.8 million revenue and £189.1 million earnings by 2029. This setup assumes 6.8% yearly revenue growth and an earnings increase of about £35.6 million from £153.5 million today.
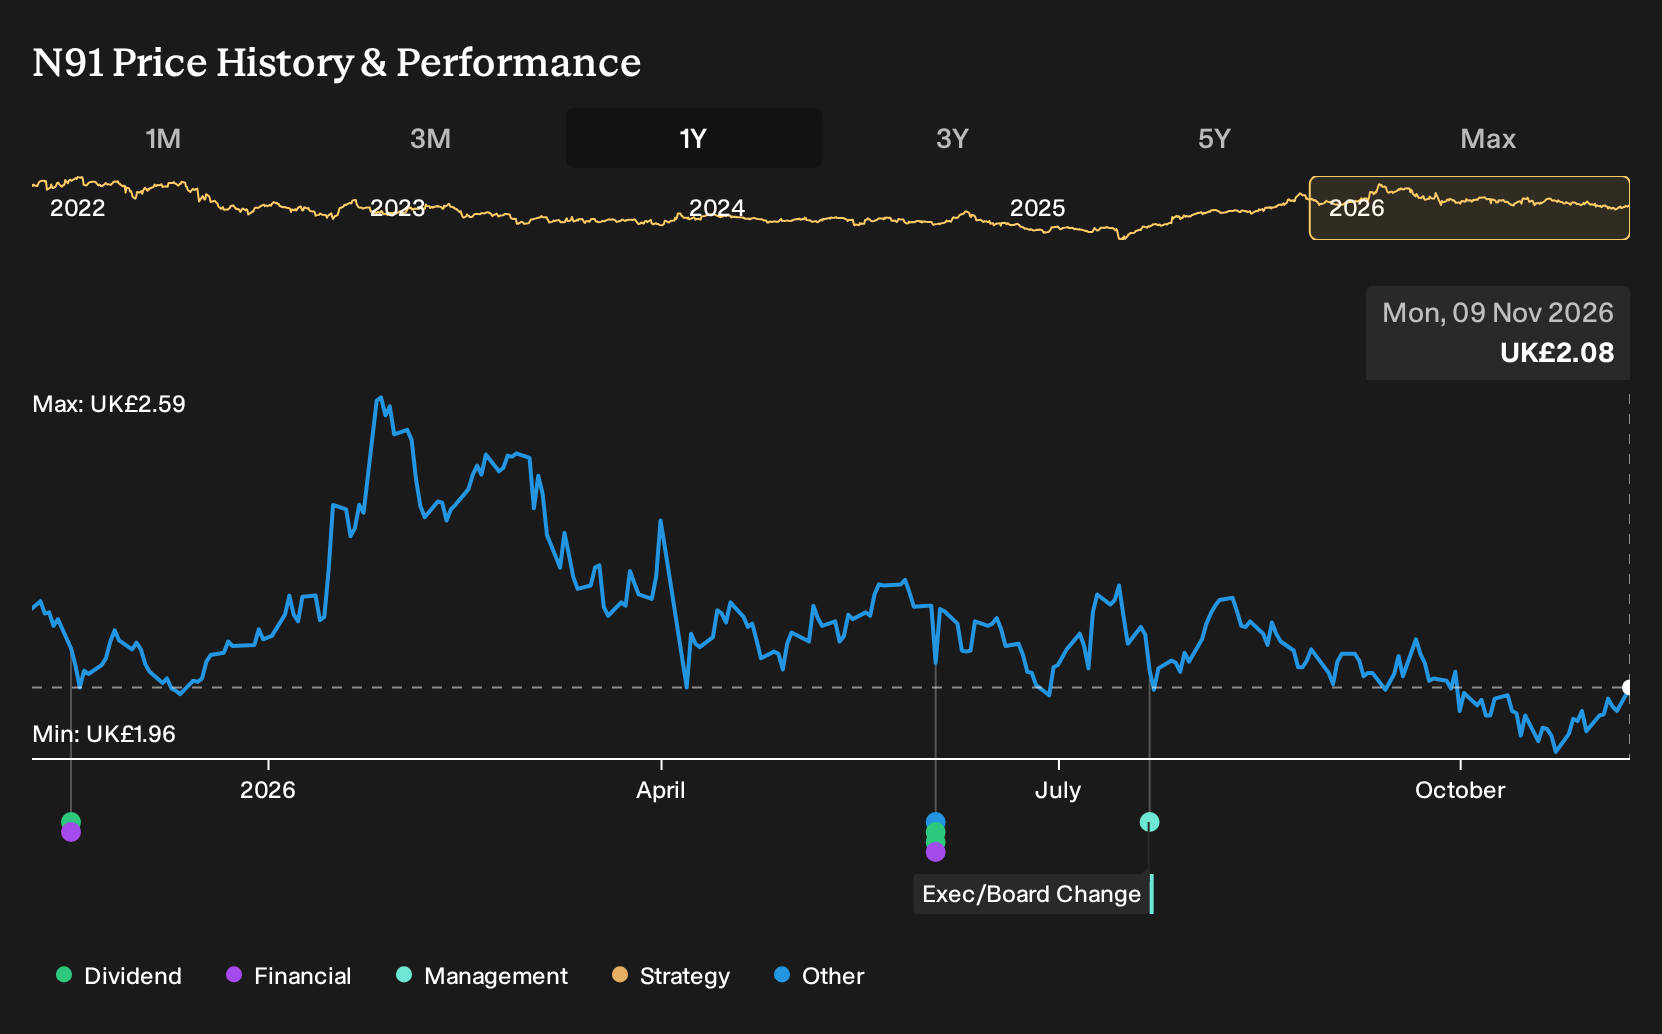
Uncover how Ninety One Group's fair value indicates a 12% potential upside to its current price, which could narrow quickly if sentiment improves.
Exploring Other Perspectives
One bullish angle on Ninety One Group puts a lot of weight on emerging market private credit as a potential earnings engine. Those analysts were modelling revenue of about £835.1 million and earnings near £209.3 million by 2029, far above the baseline view. You can treat that optimism as one possible scenario, especially since both narratives were built before the latest UK utility and infrastructure credit headlines. It is worth comparing these contrasting expectations and deciding which set of assumptions feels closer to how you see risk in this news.
Explore 4 other Ninety One Group fair value estimates, including one that suggests as much as 37% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ninety One Group research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Ninety One Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ninety One Group's overall financial health at a glance.
Looking for more Ninety One Group style investment ideas?
If the Ninety One Group story has sharpened your thinking about fees, risk and long term cash flows, broaden the search by using the Simply Wall St Screener to hunt for other stocks that fit your own checklist rather than someone else's.
- For investors who want potential mispricing combined with quality fundamentals, scan a curated pool of 16 high quality undervalued stocks that may align better with your return and risk expectations.
- If balance sheet strength is high on your list, filter for companies with conservative debt profiles and solid liquidity through a targeted list of solid balance sheet and fundamentals (9 results) that can help you sleep better at night.
- When you prefer resilient businesses with a focus on capital preservation, sort the universe with a 4 resilient stocks with low risk scores to see which stocks might offer a smoother ride through market swings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com