
monday.com (MNDY) Stock Could Trade At A Discount To Fair Value
monday.com has seen its share price come under pressure, which puts a sharper spotlight on whether the current US$87.93 level lines up with the earnings investors are paying for today. With recent headlines focused on AI products and profitability, the key issue is how that story lines up with what the income statement currently supports.
- Over the past 5 years, monday.com shareholders have seen the stock fall 75.8%, which raises the question of whether the market is now pricing its earnings more conservatively or still giving it a premium for future potential.
- Recent AI driven growth efforts and a workforce restructuring have reshaped expectations for revenue expansion and operating margins, which can feed directly into how durable the current earnings base looks against the price tag.
- Your read on monday.com is one view; the desks covering it have another. See what analysts think monday.com's shares could be worth.
The issue now is whether monday.com's current share price is adequately supported by the earnings power the business is generating today.
If you are weighing monday.com's earnings story against its recent share price slide, it can help to compare it with other AI exposed software stocks using 40 AI small caps.
Does monday.com Look Undervalued on Earnings?
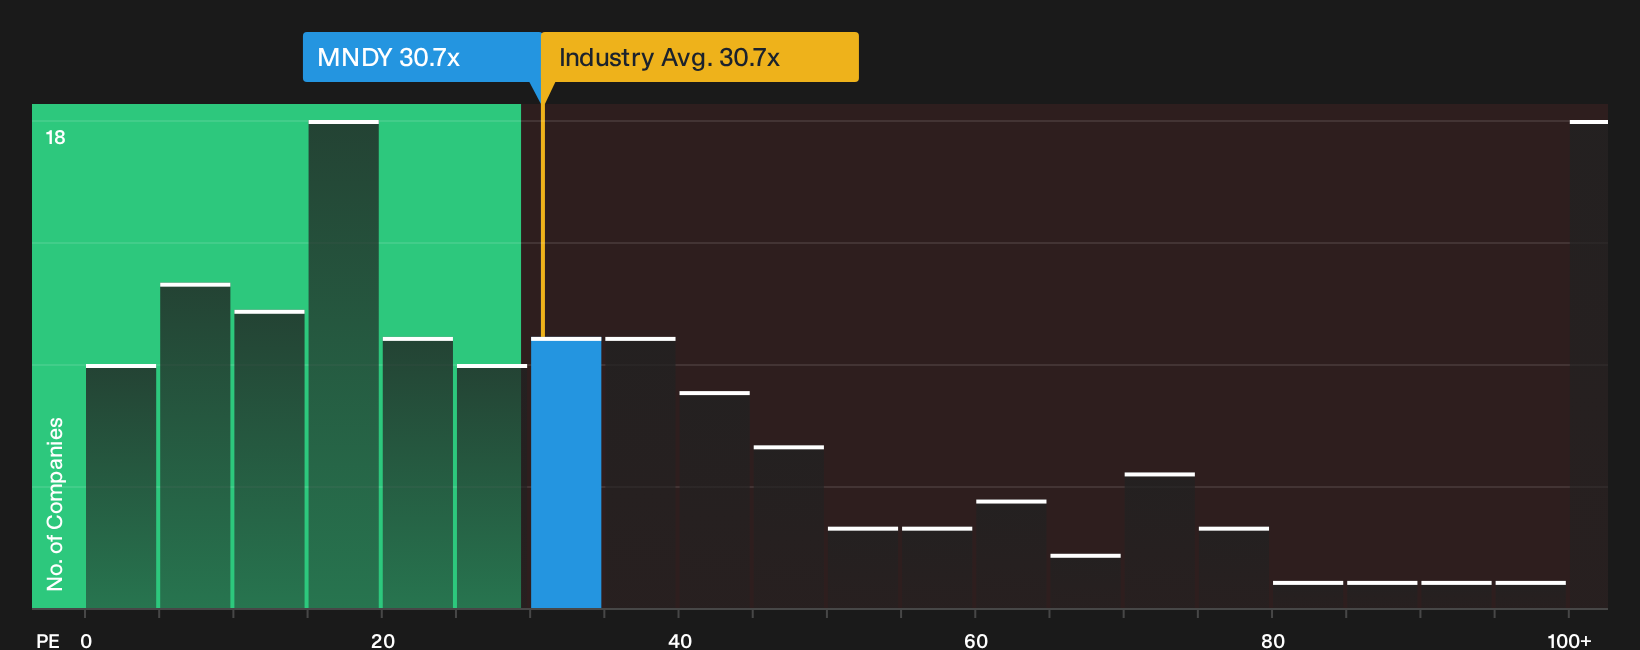
The P/E ratio is a useful lens for monday.com because it highlights what each dollar of profit costs at today’s share price. At the current level, the stock trades on a P/E of 30.7x, which is almost identical to the broader Software sector on 30.7x and very close to the peer group average of 30.7x. On raw earnings, the market is not applying a clear premium or discount to this ticker compared with similar software companies.
The tailored fair multiple for monday.com sits above the current P/E, so the shares screen as undervalued on this earnings yardstick. The recent AI driven earnings updates and cautious revenue guidance mean investors are weighing slower top line growth against stronger profitability. Even so, the valuation still points to a price that is below what this framework suggests could be justified. For anyone tracking how fully the AI story is already reflected in the earnings base, the current P/E offers a starting point rather than a final answer. Explore the numbers behind monday.com's P/E valuation.
The monday.com Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for monday.com pick up where the valuation puzzle leaves off. They spell out which expectations for future growth, profitability and earnings would need to hold for monday.com to be worth meaningfully more or less than the current share price. Each one frames fair value as a specific thesis about the business that you can watch play out over time. These sit on Simply Wall St's Community page.
Bulls see monday.com’s AI usage shift as underappreciated, while bears focus on whether softer retention and heavier AI spend cap what shareholders get paid for it.
Bull case: 19% undervalued
Supporters of the analyst consensus Narrative on Simply Wall St point to monday.com’s AI work platform and upmarket push as the key swing factors.
"Hybrid seat plus AI consumption pricing, with early signs of customers topping up AI credits and AI ARR contributing a growing share of net new ARR, introduces a usage based layer that can decouple growth from seat counts and support both revenue expansion and margin improvement…"
Discover why this Narrative puts monday.com at 19% undervalued.
Bear case: roughly fairly valued
The bearish analyst Narrative on Simply Wall St leans toward caution around execution, especially on AI monetisation and retention.
"While monday.com highlights strong AI adoption and a pivot to an AI work platform, the shift to a seats plus credits model is still early and management has not built any material AI consumption impact into 2026 guidance…"
Explore why this Narrative puts monday.com at roughly fairly valued.
monday.com’s valuation still leaves one crucial issue on the table
All the price and earnings work only goes so far if you do not also look at the specific risks that have tripped our checks for monday.com. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com