
Could Lower Output But Higher Profit Alter The Investment Case For TransAlta (TSX:TA)?
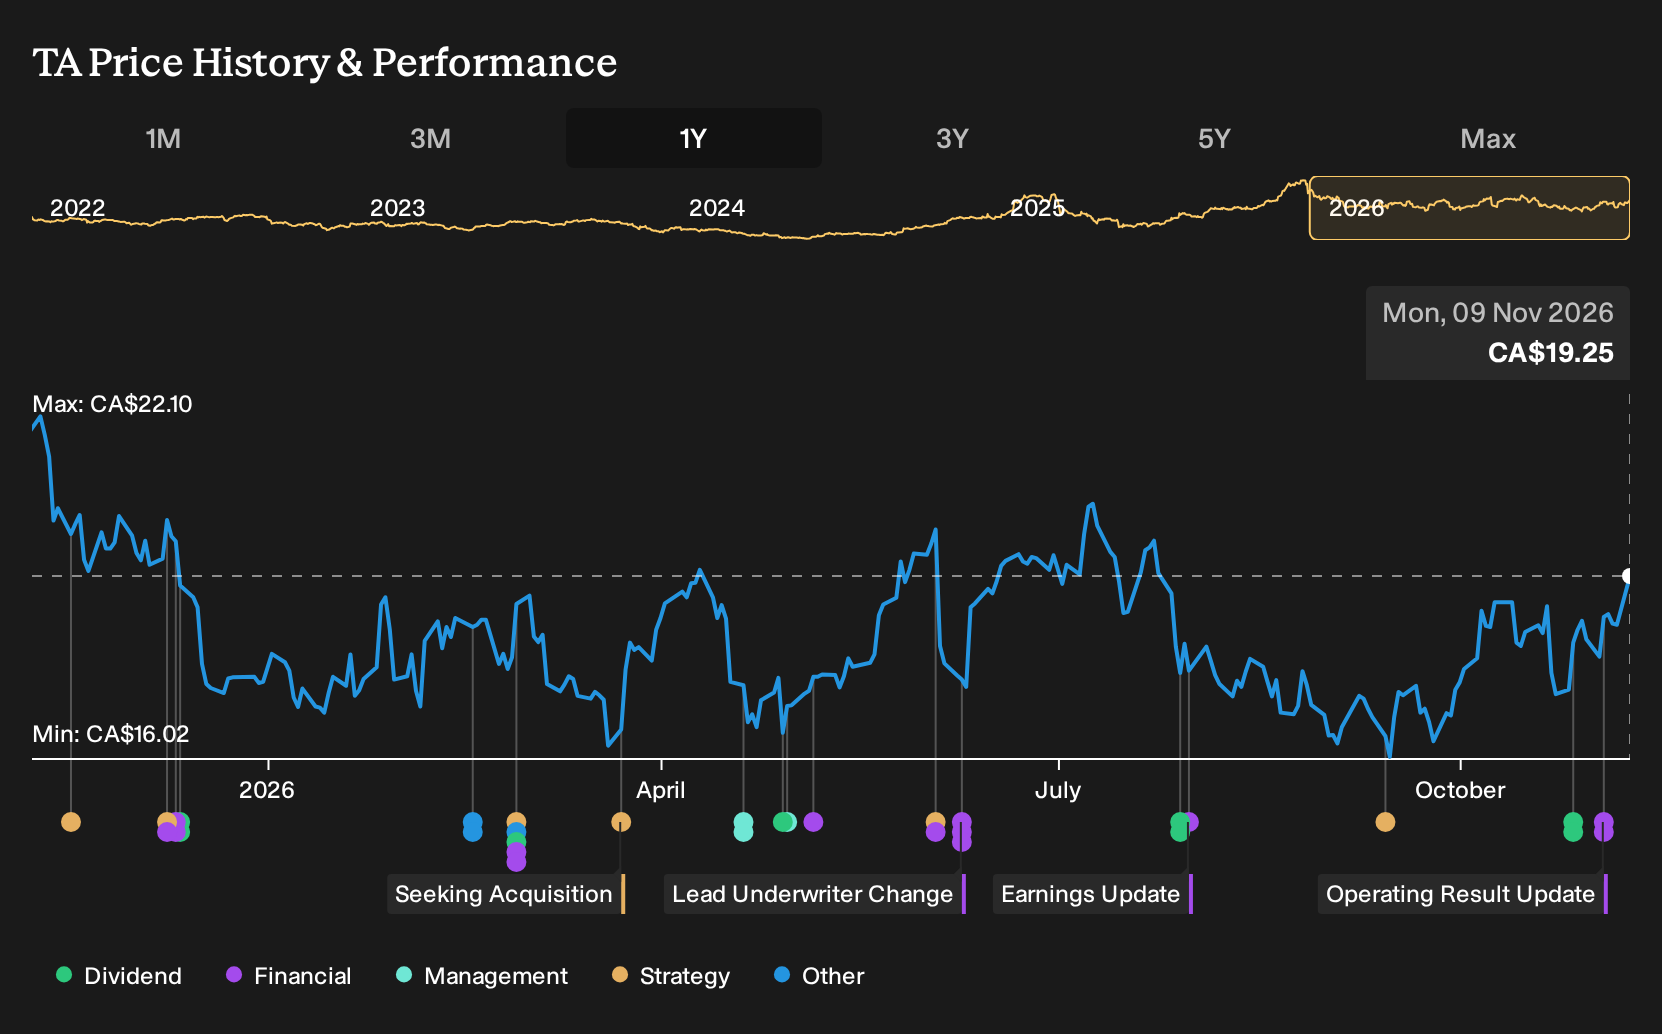
- TransAlta reported third quarter 2026 results with production at 5,260 GWh and sales at C$536 million, while net income reached C$77 million compared with a loss a year earlier.
- The business generated C$139 million of net income over the first nine months of 2026 despite lower output and sales, indicating that recent changes in costs, contracts or generation mix are having a material effect on profitability.
- We will now explore how TransAlta's shift from losses to profit in 2026 could reshape the investment narrative built around its contracted plans.
Compare TransAlta's return to profit with other power producers by scanning our hand picked 42 power grid technology and infrastructure stocks that could be repositioning based on similar operating and dividend updates.
TransAlta Investment Narrative Recap
To own TransAlta, you need to be comfortable with a power producer that relies on a mix of contracted assets and more volatile Alberta exposure. The analyst consensus Narrative on Simply Wall St emphasizes future contracted cash flows and data-center-driven demand as key supports. The latest quarter shows the firm can generate profit even with lower production and sales, so the near-term focus stays squarely on execution rather than volume growth.
The biggest immediate swing factor is how softer Alberta pricing feeds through once hedges roll off. In contrast, heavy reliance on older coal-to-gas and thermal assets keeps regulatory and refurbishment risk very real. If required spending or policy pressure on these units increases, earnings and free cash flow could come under strain.
The most relevant piece of recent news for this story is the earnings release itself. TransAlta reported C$77 million of net income in the quarter and C$139 million across the first nine months, compared with losses a year earlier, despite lower generation and revenue. That combination of weaker volumes and higher profit puts the quality and repeatability of the cost and contract improvements under closer scrutiny.
For catalysts, that profit swing matters because the broader growth case relies on funding data-center-related demand, long-dated Colorado peakers and the Centralia Unit 2 conversion while managing a balance sheet where interest costs are not yet well covered by earnings. The declared common and preferred dividends indicate management confidence in ongoing cash generation, but they also raise the bar for consistent execution on projects and on managing Alberta price risk.
TransAlta's current analyst narrative points to revenue of CA$2.7b and earnings of CA$338.4 million by 2029, based on an assumed 5.4% yearly increase in revenue and a swing in earnings of about CA$414 million from a loss of CA$76.0 million today.
Uncover why TransAlta's fair value indicates a 22% potential upside to its current price, which could narrow quicker than many investors expect.
Exploring Other Perspectives
You can read this quarter in two very different ways. Consensus leans on TransAlta eventually reaching about C$2.7b of revenue and C$338.4 million of earnings by 2029. The most cautious analysts were closer to C$2.5b and only C$41.0 million of earnings. Those more pessimistic forecasts, set before this profit swing, may now face a rethink.
Explore another TransAlta fair value estimate, including one that suggests it could be worth just CA$23.50!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your TransAlta research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TransAlta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TransAlta's overall financial health at a glance.
Looking for more investment ideas beyond TransAlta?
If the TransAlta story has you rethinking how you allocate capital across the power and infrastructure space, broadening your watchlist with a few focused stock shortlists can sharpen your next move.
- If you want potential value combined with quality fundamentals, start with a curated set of 6 high quality undervalued stocks that already screen for both financial strength and pricing appeal.
- If resilience and balance sheet strength matter most to you, narrow your search to a list of solid balance sheet and fundamentals (5 results) that can help filter out weaker businesses quickly.
- If you are hunting for companies that the market may not be fully focused on yet, widen your scope using a 7 high quality undiscovered gems that surfaces under-the-radar opportunities with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com