
Aecon Group Stock Q3 Earnings Improve While Year To Date Loss Keeps Questions Open
- Aecon Group reported third quarter 2026 sales of C$1,920.58 million and net income of C$52.9 million, with basic earnings per share from continuing operations of C$0.77.
- Across the first nine months of 2026, Aecon Group posted sales of C$4,808.58 million but recorded a net loss of C$73.1 million, highlighting that recent quarterly results are set against year to date pressures.
- Attention now turns to how Aecon Group's combination of a profitable quarter and a year to date loss influences the existing investment narrative.
Compare Aecon Group's mixed year-to-date picture with other infrastructure-focused plays by scanning a curated list of list of solid balance sheet and fundamentals (5 results).
Aecon Group Investment Narrative Recap
To own Aecon Group, you need to be comfortable with a construction and infrastructure contractor that currently shows strong quarterly profitability alongside a year to date loss. The analyst consensus Narrative on Simply Wall St leans heavily on energy transition, collaborative contracts, and recurring utilities work as the core pillars. The latest quarter supports the revenue side of that view, but not yet the full year earnings story.
The key short term swing factor is whether recent contract mix and execution can turn that year to date loss into cleaner, more consistent profitability. The main risk for now remains margin pressure. Management has previously accepted lower construction EBITDA margins in exchange for lower project risk, which can cap earnings progress even when sales look healthy.
The fresh earnings release for the quarter and nine months to 30 September 2026 sits at the center of this story. Aecon Group reported C$1,920.58 million in quarterly sales and C$52.9 million in net income, yet the first nine months still show a net loss of C$73.1 million. That split matters for how you think about execution.
This update gives you current evidence on two critical pieces. Strong quarterly profit provides some support for the idea of improving earnings quality tied to collaborative contracts and recurring segments. The ongoing year to date loss keeps attention on the known risks, including compressed margins, dependence on public infrastructure spending, and cost pressure from labour and large project delivery.
Aecon Group's narrative projects revenue of C$7.7b and earnings of C$366.3 million by 2029, based on analysts assuming 6.8% yearly revenue growth and earnings moving from a loss of C$52.4 million today to a profit of C$366.3 million, which represents an earnings swing of about C$418.7 million.
Uncover why Aecon Group's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
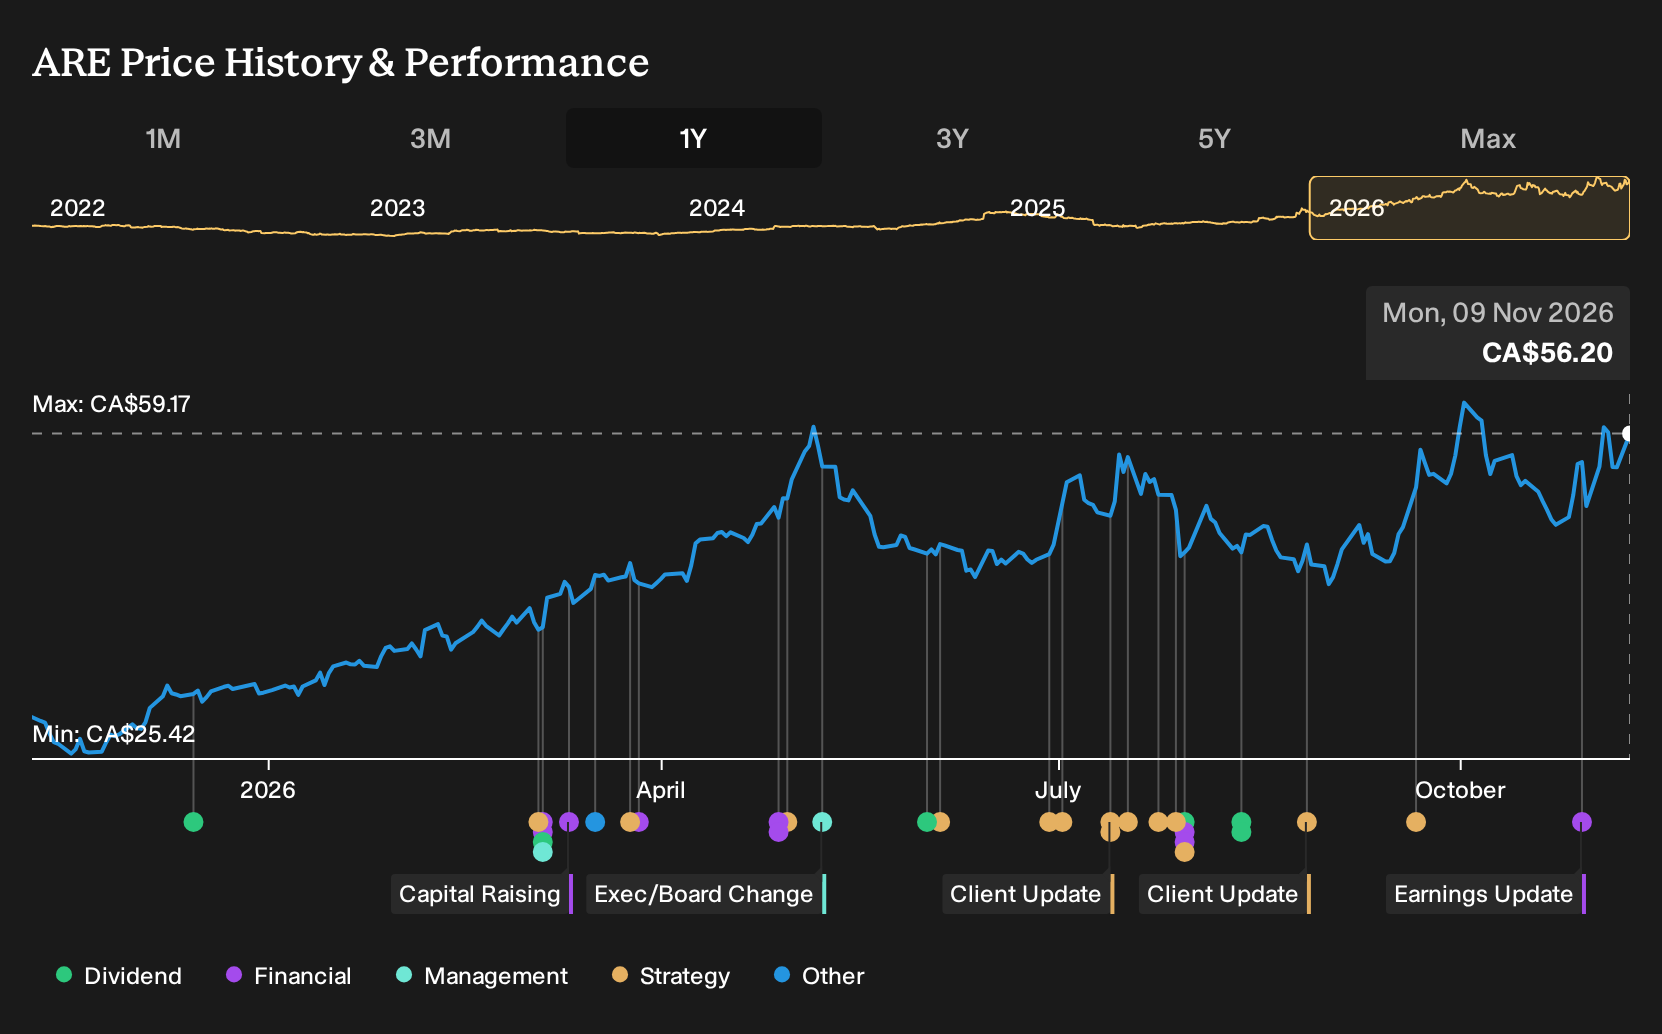
Exploring Other Perspectives
Some bullish analysts frame Aecon Group through a very different lens. They see record backlog and nuclear projects as the real catalyst, not just margin repair. That group was pencilling in roughly 8.6% annual revenue growth and C$355.3 million in earnings by 2029 before this earnings release, so their story may shift as new data lands.
Explore 3 other Aecon Group fair value estimates, including one that suggests as much as 25% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Aecon Group research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aecon Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aecon Group's overall financial health at a glance.
Looking for more investment ideas beyond Aecon Group?
Once you have a view on Aecon Group, it can help to widen the lens and compare it with other opportunities that fit your risk appetite and income goals using the Simply Wall St Screener.
- For investors who want growth potential without ignoring quality, scan a focused set of 7 high quality undiscovered gems that pair strong fundamentals with under-the-radar profiles.
- If stability matters more to you than chasing the highest returns, filter for companies with steadier profiles by reviewing 9 resilient stocks with low risk scores that score well on resilience.
- Income seekers who care about both yield and staying power can zero in on 3 dividend fortresses that combine higher payouts with robust underlying businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com