
Revenue Guidance Cut Could Reset The Case For Veracyte Stock (VCYT)
- Veracyte reported third quarter 2026 revenue of US$151.75 million and net income of US$31.5 million, then modestly lowered full year revenue guidance while authorizing a US$100 million share repurchase program funded from cash.
- The combination of reduced testing outlook, especially for the Decipher prostate cancer franchise and new launches, alongside a fresh buyback, highlights management's focus on balancing growth investment with capital returns.
- This article examines how Veracyte's trimmed 2026 revenue outlook shapes the existing investment narrative around diagnostics growth and profitability.
Compare Veracyte's reset expectations and cash funded buyback with other diagnostics players by scanning our curated list of 36 healthcare AI stocks riding similar testing and data trends.
Veracyte Investment Narrative Recap
To own Veracyte, investors need to be comfortable with a diagnostics business still heavily tied to Decipher and Afirma while it works to broaden its test portfolio. The analyst consensus Narrative on Simply Wall St assumes expanding adoption of genomic testing and a growing pipeline. The latest quarter shows Veracyte producing US$151.75 million in revenue and US$31.5 million in net income, which keeps that long term story intact.
The near term swing factor is execution on test volumes, particularly Decipher prostate, and payer coverage for newer assays. Management trimming 2026 revenue and testing guidance slightly suggests the biggest current risk is slower uptake from new launches rather than a structural break in demand. If those adoption trends stabilize, this reset looks more like calibration than a major shift.
The US$100 million share repurchase plan is the announcement that ties most closely to this earnings reset. Veracyte is committing cash and equivalents to buy back stock over 12 months while it works through softer testing expectations and limited near term revenue from new products. That shifts attention back to cash generation, capital allocation and balance sheet flexibility.
For you as a shareholder, the practical question is how this interacts with the main catalysts and risks already in play. Concentration in Decipher and Afirma still dominates operational exposure, and payer or competitive pressure around those assays remains central. The buyback adds another moving piece for per share metrics and may matter most if execution on upcoming launches and the OPTIMA study progresses in line with the existing pipeline narrative.
Analysts currently frame Veracyte's story around revenue of US$787.4 million and earnings of US$116.9 million by 2029, which lines up with an assumed 11.9% yearly increase in sales and an earnings uplift of about US$2.4 million from US$114.5 million today.
Uncover why Veracyte's fair value indicates a 130% potential upside to its current price, which could narrow quickly.
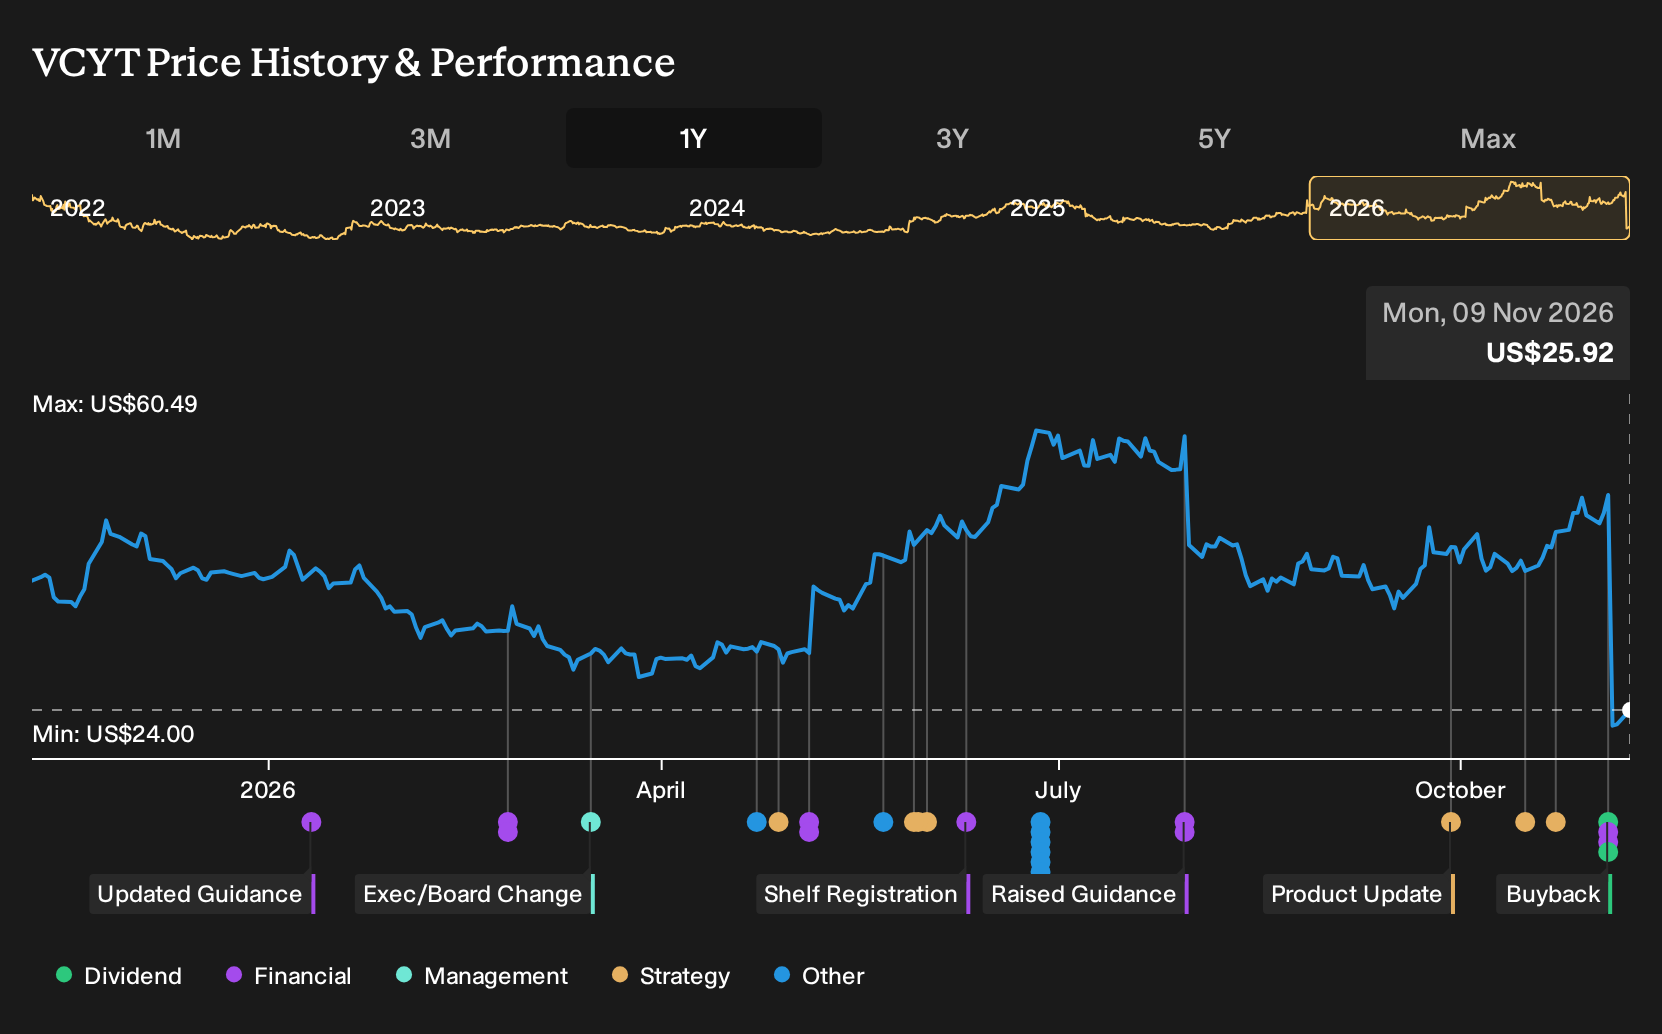
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Prosigna as a catalyst. Before this guidance cut and buyback, they were modeling revenue of about US$818.7 million and earnings near US$141.3 million by 2029 for Veracyte. You can treat that as one possible story and compare it with several others before deciding what makes sense to you.
Explore 3 other Veracyte fair value estimates, including one that suggests as much as 170% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Veracyte research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Veracyte. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Veracyte's overall financial health at a glance.
Looking For More Investment Ideas Beyond Veracyte?
If Veracyte sits at the center of your watchlist today, it can still pay to compare that thesis with other businesses that have very different risk and return profiles. Use the Simply Wall St Screener to broaden your opportunity set and stress test your thinking across sectors and balance sheet strengths.
- If capital preservation is a priority, start with a group of resilient businesses by reviewing 30 resilient stocks with low risk scores that aim to keep downside risk in check.
- If balance sheet strength matters most to you, scan a list of solid balance sheet and fundamentals (25 results) that can help you focus on companies with financial buffers to support their plans.
- If you are hunting for under-the-radar stories, widen your search using 19 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com