
Does Raised Full Year Guidance Change The Bull Case For InterDigital Stock (IDCC)?
- InterDigital reported third quarter 2026 sales of US$193.43 million and net income of US$80.23 million, along with higher basic and diluted EPS compared with the same period in 2025.
- The raised full year 2026 revenue, net income and diluted EPS guidance, based on revenue already under contract, indicates management confidence in the durability of InterDigital’s licensing model.
- We will look at how InterDigital’s investment narrative is influenced by stronger third quarter profitability and another increase to full year guidance.
Scan how InterDigital’s licensing strength and 6G research story compares with other potential breakouts by checking the hand picked 53 AI infrastructure stocks in this space.
InterDigital Investment Narrative Recap
To own InterDigital, you need to believe the firm can keep turning its wireless, video and AI research into long lived licenses across smartphones, streaming, cloud and connected devices. The third quarter showed higher quarterly sales and earnings per share than a year ago, yet nine month figures highlight that profit and revenue can still be lumpy.
The analyst consensus narrative on Simply Wall St frames the key near term catalyst as execution on existing contracts and arbitration linked to major streaming and cloud deals. The biggest current risk is enforcement and legal spend staying high. The raised 2026 guidance, based on contracted revenue, speaks directly to both points.
The most relevant update here is InterDigital’s higher full year 2026 outlook, which now calls for US$813 million to US$819 million of revenue and net income of US$307 million to US$315 million. Management also guided to fourth quarter revenue of US$154 million to US$160 million and diluted EPS of US$1.04 to US$1.27.
Those figures matter because they sit against a backdrop where analysts expect revenue and earnings to decline over the next three years and see enforcement costs as a key swing factor. The updated guidance, built only on already contracted revenue, gives you a clearer yardstick to track whether the licensing model, cash generation and legal expenses stay aligned with that consensus path.
InterDigital Long Term Forecasts In Context
InterDigital's narrative projects US$883.6 million revenue and US$371.6 million earnings by 2029. Analysts build this on 3.9% yearly revenue growth and an earnings increase of about US$69.4 million from US$302.2 million today.
Uncover why InterDigital's fair value indicates a 57% potential upside to its current price that may be short-lived.
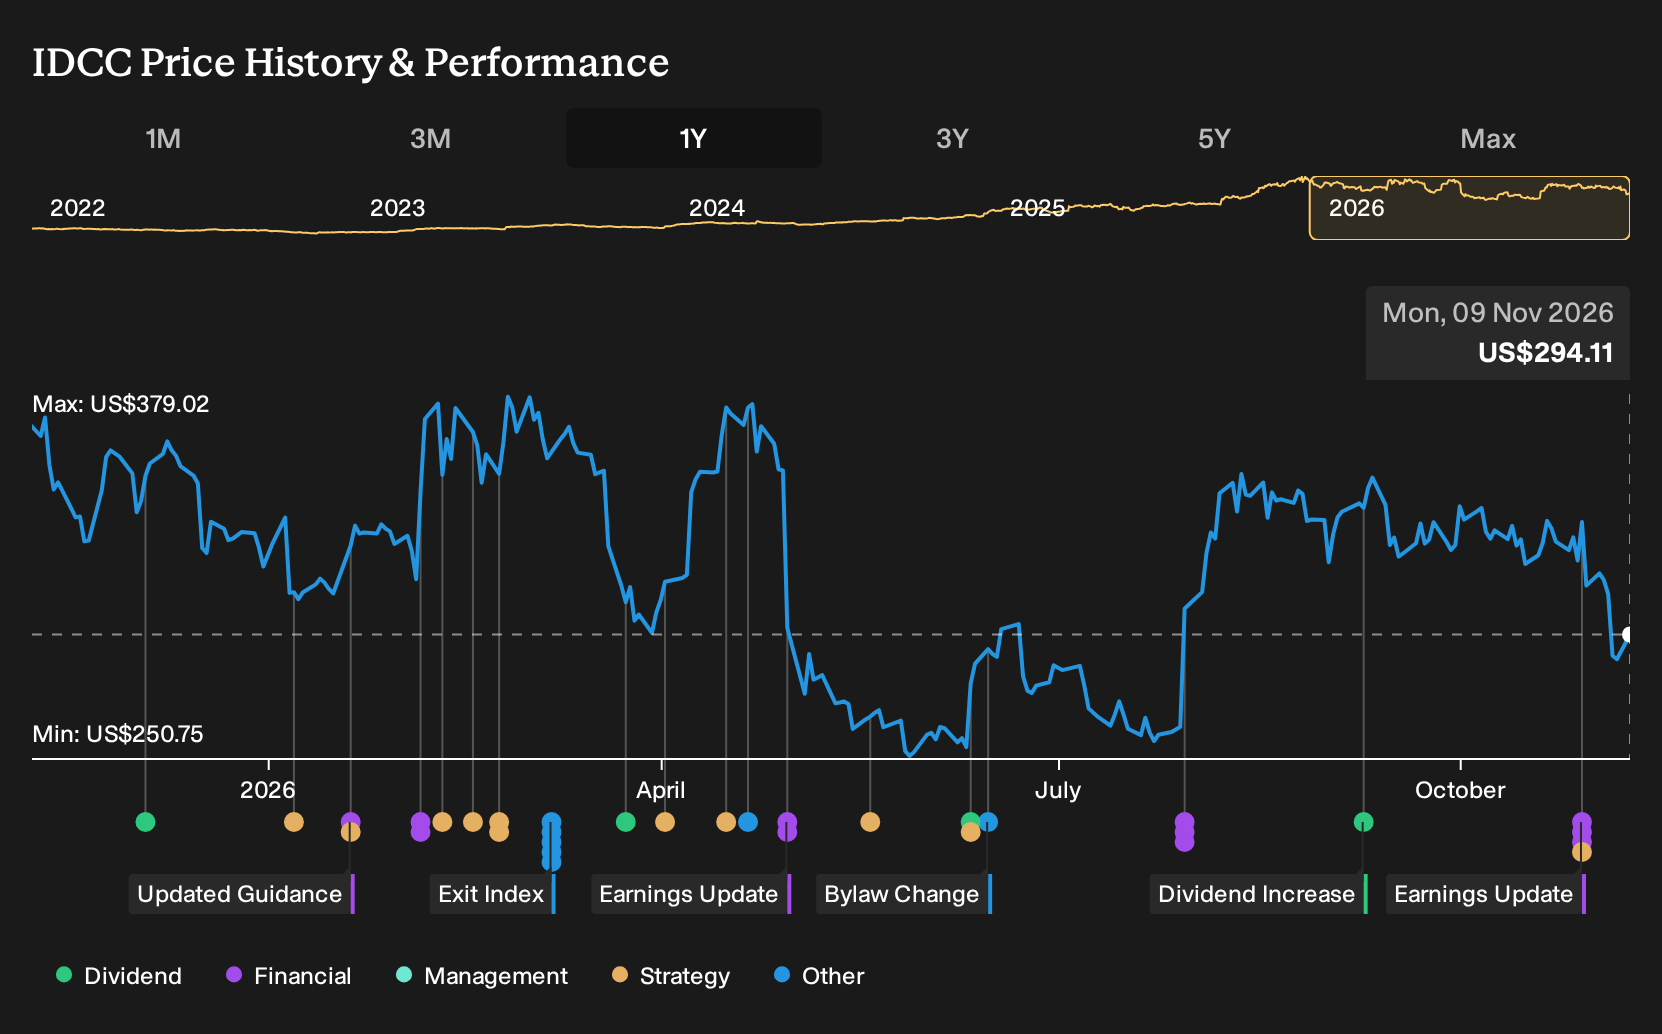
Exploring Other Perspectives
One sharp contrast comes from the most pessimistic view on InterDigital’s enforcement spend. Those analysts worry that higher legal and arbitration costs could outweigh licensing benefits, even though their own pre news forecasts still pointed to revenue of US$984.2 million and earnings of US$422.4 million by 2029. Use this latest guidance and 6G update as a prompt to compare those expectations with other scenarios and decide which story appears more realistic to you.
Explore 5 other InterDigital fair value estimates, including one that suggests as much as 41% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your InterDigital research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for InterDigital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate InterDigital's overall financial health at a glance.
Looking For More Ideas Beyond InterDigital?
Once you have a view on InterDigital, it can help to stress test that thesis against other opportunities that share similar quality markers or risk profiles. The Simply Wall St Screener lets you scan the market in a structured way so you are comparing InterDigital with companies that match your preferred balance of resilience, income and upside potential.
- For investors who care most about capital strength and staying power, start with a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with financial cushions that may better support their plans through different conditions.
- If your priority is to reduce portfolio shocks, consider using a 30 resilient stocks with low risk scores that filters for companies with steadier risk profiles so you can judge how InterDigital sits beside them.
- For those hunting for under followed opportunities, there is a 19 high quality undiscovered gems that highlights companies with strong fundamentals that may not yet be widely watched.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com