
Westlake (WLK) Returns To Profit As Valuation Debate Comes Into Focus
Westlake (WLK) just reported third quarter results that shifted back to profitability, with management highlighting ongoing housing sector pressure, softer seasonality ahead, and trimmed capital spending plans that could influence how investors view the stock.
At a share price of US$64.13, Westlake has seen short term momentum cool, with a 7 day share price return down 9.89% and a 90 day share price return down 20.67%. However, the 1 year total shareholder return is slightly positive at 1.06%, hinting that sentiment has softened recently despite the latest move back into the black.
Capitalize on Westlake's swing back to profitability by scanning a curated 33 high quality undervalued stocks that share resilient balance sheets and stronger fundamentals than recent share price moves suggest.Westlake now trades at a discount to analyst targets after a sharp pullback, while still carrying an intrinsic value estimate that points the other way. Is the market being cautious, or just too pessimistic on the recent earnings turn?
Most Popular Narrative: 19% Undervalued
Against Westlake's last close of $64.13, the analyst consensus Narrative on Simply Wall St anchors fair value at about $79.18, implying a sizeable gap that this framework ties to specific execution and industry drivers rather than broad market mood.
Westlake's three pillar profitability improvement plan, targeted to add $600 million of EBITDA benefit in 2026 with about $300 million already realized by mid year, remains an active lever through ongoing footprint optimization, cost savings and plant reliability efforts. These initiatives are intended to lower cost of sales and support net margin expansion.
See why 9 investors see Westlake as 19% undervalued.
Result: Fair Value of $79.18 (UNDERVALUED)
Still, the narrative around Westlake can break if global chemical oversupply keeps pressuring pricing, or if higher North American energy costs once again squeeze its cost advantage.
Find out about the key risks to this Westlake narrative.
Another View: DCF Says Westlake Is Overvalued
The analyst narrative pins Westlake at a fair value of about $79.18, yet the Simply Wall St DCF model lands closer to $57.44. On that cash flow view, the recent $64.13 share price screens as overvalued. Which lens do you trust more: earnings forecasts or cash generation?
Look into how the SWS DCF model arrives at its fair value.
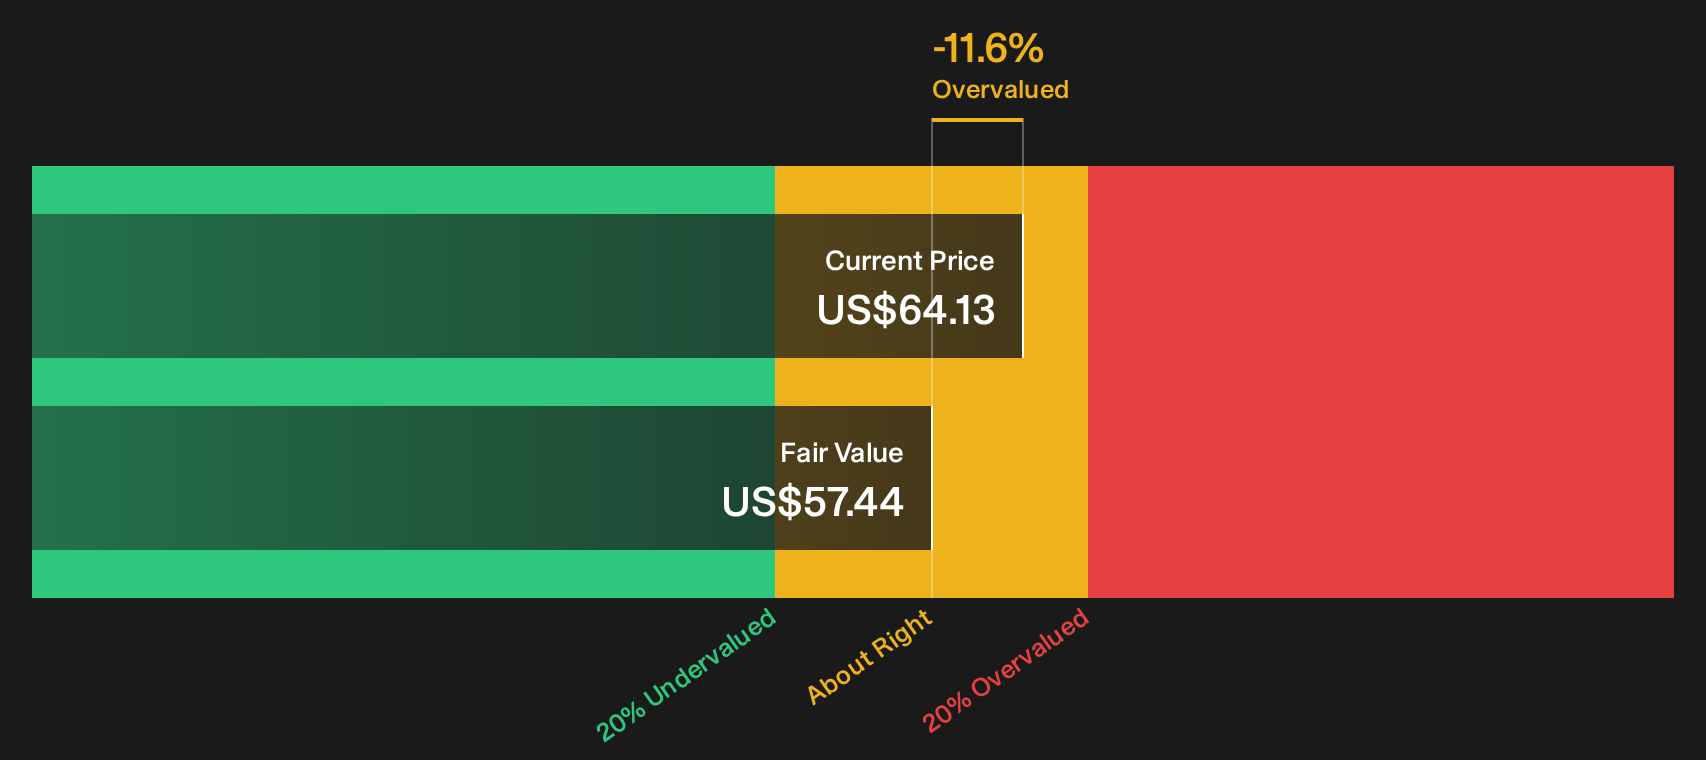
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Westlake for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Westlake is clearly split, and that is where your edge can come from if you move before the crowd settles. To weigh the potential upside and downside yourself, take a closer look at the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Westlake?
Do not stop your research with Westlake. Broaden your watchlist now by scanning focused stock ideas built from clear balance sheet strength, income potential, and valuation discipline.
- Target dependable income streams by reviewing a curated set of higher yielding payers in the 6 dividend fortresses that combine strong payouts with resilient fundamentals.
- Sharpen your focus on financial resilience and balance sheet strength by running through the list of solid balance sheet and fundamentals (25 results) so weaker businesses do not quietly dilute your portfolio quality.
- Hunt for underfollowed opportunities that still show quality metrics by checking the 19 high quality undiscovered gems before other investors start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com