
Nine Month Earnings Raise Fresh Questions For Prysmian (BIT:PRY) Stock
- Prysmian reported nine month 2026 results with sales of €17,656 million, revenue of €18,091 million and net income of €977 million, with basic and diluted EPS at €3.2.
- The mix of higher sales and revenue alongside slightly lower net income and earnings per share highlights the pressure that costs and project execution can place on Prysmian profitability, even when top line activity is strong.
- This article examines how Prysmian's investment narrative is affected by higher sales alongside slightly lower net income in these nine month results.
Prysmian Investment Narrative Recap
The big picture for Prysmian is about turning strong project demand in power grids and digital infrastructure into consistent earnings and cash generation. To stay invested, you need to believe management can keep large contracts on schedule and within budget while holding margins across Transmission, Power Grid, Electrification and Digital Solutions. The latest nine month results, with lower net income and EPS alongside higher sales, keep that execution question front and center.
According to the analyst consensus Narrative on Simply Wall St, expectations are already high, backed by record EBITDA in the most recent quarter and upgraded 2026 EBITDA and free cash flow guidance. The recent earnings release does not appear to change the main near term catalyst: delivery on that guidance. It also does not change the key risk: any shortfall in EBITDA or free cash flow that could challenge those assumptions.
The October 29 earnings release is the key announcement tied to this update. Prysmian reported sales of €17,656 million and revenue of €18,091 million for the nine months to September 30, 2026, compared with €14,684 million and €15,347 million a year earlier. Net income was €977 million versus €1,019 million, and basic and diluted EPS were €3.2 compared with €3.49 and €3.47.
This mix of heavier activity but slightly lower earnings sits alongside upgraded 2026 guidance referenced in the analyst consensus Narrative on Simply Wall St. For a shareholder, the operational focus now is whether segments such as Power Grid can lift margins toward internal targets, whether one off items that affect reported quality of earnings remain contained, and whether integration work around acquisitions like Atkore supports the EBITDA and free cash flow trajectory already set out.
Prysmian's narrative projects €28.5b revenue and €2.1b earnings by 2029. This assumes 10.1% yearly revenue growth and an earnings increase of about €700m from €1.4b today.
Uncover why Prysmian's fair value indicates a 44% potential upside to its current price that could narrow quickly.
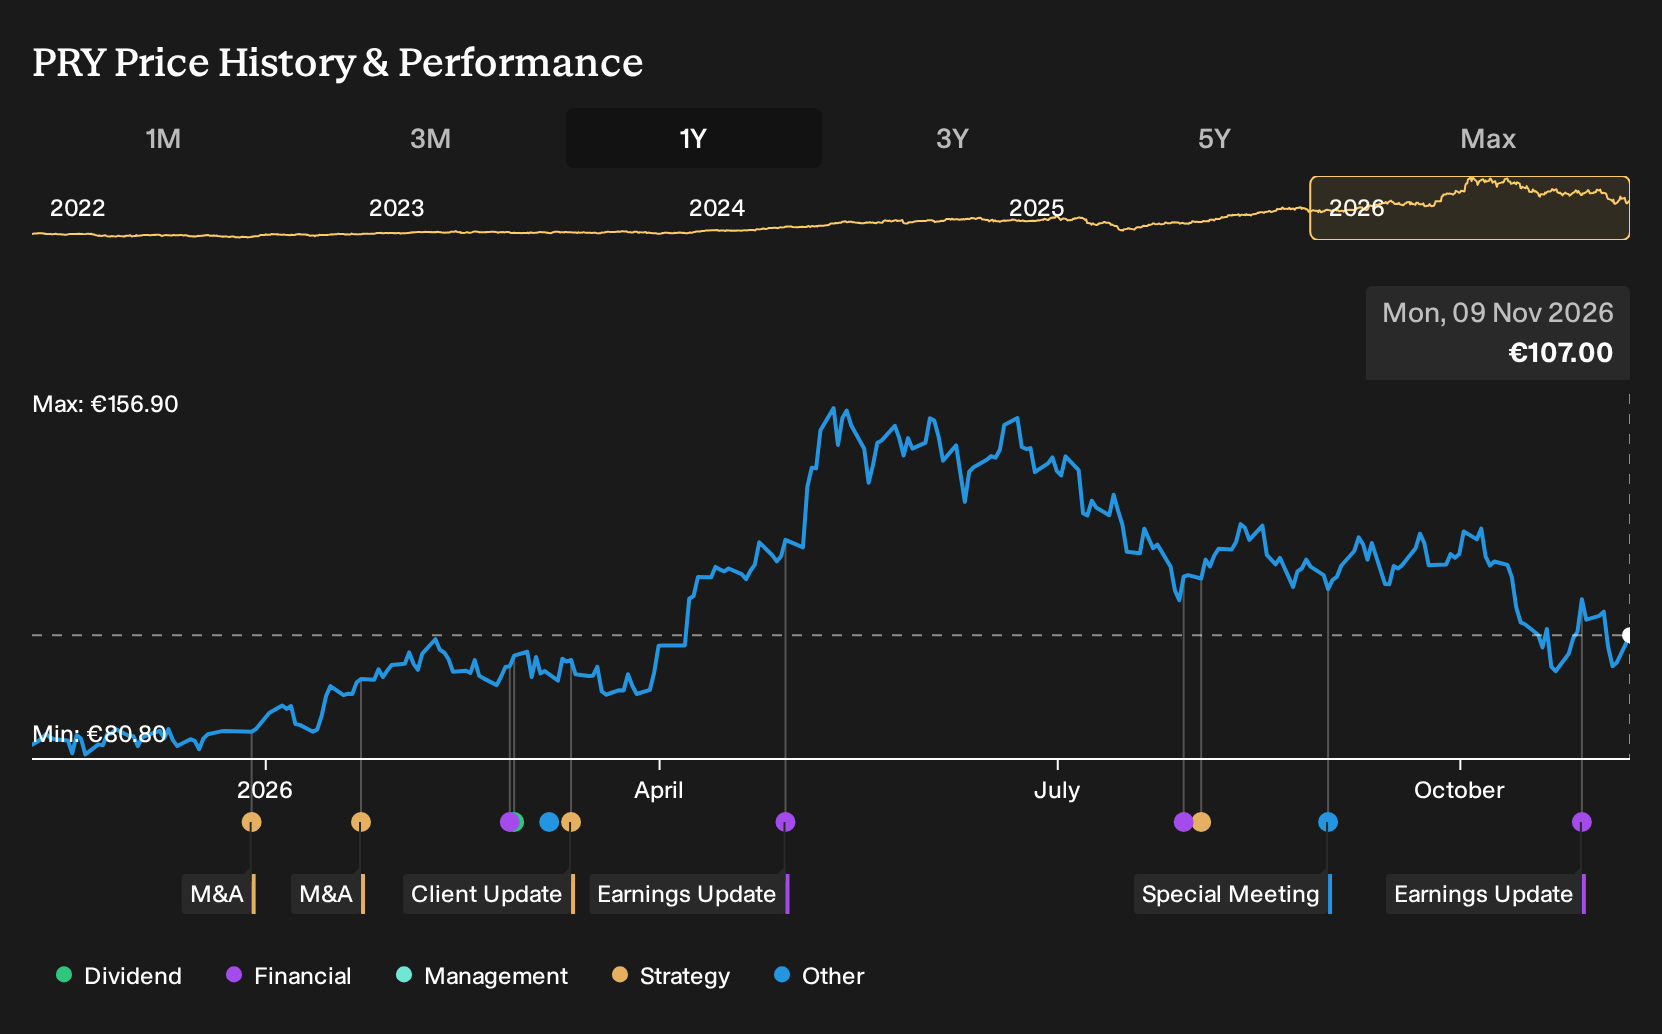
Exploring Other Perspectives
One bearish angle that really contrasts with the upbeat Prysmian story is project risk. The lowest analysts were already working off softer numbers, with revenue assumptions nearer €24.8b and earnings around €1.9b by 2029, and saw the €17b backlog as a source of potential cost overruns. With these nine month earnings now out, those pre news views could shift quite a bit. Treat them as a starting point and compare multiple narratives before deciding how you see the trade off between growth and execution risk.
Explore 6 other Prysmian fair value estimates, including one that suggests as much as 10% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Prysmian research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Prysmian. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Prysmian's overall financial health at a glance.
Looking For More Investment Ideas Beyond Prysmian?
If the Prysmian story has you thinking about where else project risk, balance sheet strength, or valuation might be working in your favour, it helps to scan a wider field of opportunities. Use the Simply Wall St Screener to quickly filter for shares that better fit your goals, whether you care more about upside potential, resilience, or dependable cash returns.
- For investors hunting for mispriced quality, review companies highlighted in the 209 high quality undervalued stocks that combine stronger fundamentals with what may be undemanding market expectations.
- If capital preservation and steadier profiles matter most to you, narrow your list using the 202 resilient stocks with low risk scores that focuses on businesses with more resilient risk scores.
- For readers who care about robust finances supporting long term plans, filter candidates through the list of solid balance sheet and fundamentals (194 results) to find companies with stronger balance sheets and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com