
Is Solaris Energy Infrastructure (SEI) Cheap After Its Earnings Beat And 900 Megawatt Contract?
Solaris Energy Infrastructure (SEI) just delivered third quarter results that topped analyst expectations on both revenue and earnings, paired with raised adjusted EBITDA guidance and a 15 year, 900 megawatt contract with an investment grade customer.
At a share price of $62.61 after an 8.38% 1 day share price gain, Solaris Energy Infrastructure is rebounding from a 30 day share price return that fell 18.05%. The year to date share price return of 24.57% and a very large 5 year total shareholder return suggest longer term momentum remains strong as investors factor in the upbeat quarter, the new 15 year power contract and the board’s decision on the fourth quarter dividend.
Scan other power and infrastructure players showing similar momentum by checking our curated list of 42 power grid technology and infrastructure stocks aligned with stories such as Solaris Energy Infrastructure’s contract win and guidance raise.
Solaris Energy Infrastructure now trades well below both analyst targets and some intrinsic value estimates after this sharp bounce. Is the recent move a catch up to fair value, or just the opening stretch of a longer rerating?
Most Popular Narrative: 41% Undervalued
The analyst consensus Narrative on Simply Wall St sees Solaris Energy Infrastructure’s fair value at $105.77 versus a last close of $62.61. This frames the current gap through aggressive growth forecasts, rising margins and a higher return profile discounted at 8.41%.
Executing on a capital program funded by over US$2.5b of issued notes, an undrawn US$650m revolver and more than US$800m of cash, alongside internal underwriting that targets unlevered returns above 20% on deployed capital, gives Solaris Energy Infrastructure a path to scale its contracted portfolio into a larger adjusted EBITDA contribution relative to current earnings.
See why 28 investors see Solaris Energy Infrastructure as 41% undervalued.
Result: Fair Value of $105.77 (UNDERVALUED)
Still, the upbeat Solaris Energy Infrastructure narrative leans heavily on successfully executing a capital intensive buildout under higher leverage, as well as on data center demand that could soften if AI funding or policy support wavers.
Find out about the key risks to this Solaris Energy Infrastructure narrative.
Another Take On Solaris Energy Infrastructure’s Valuation
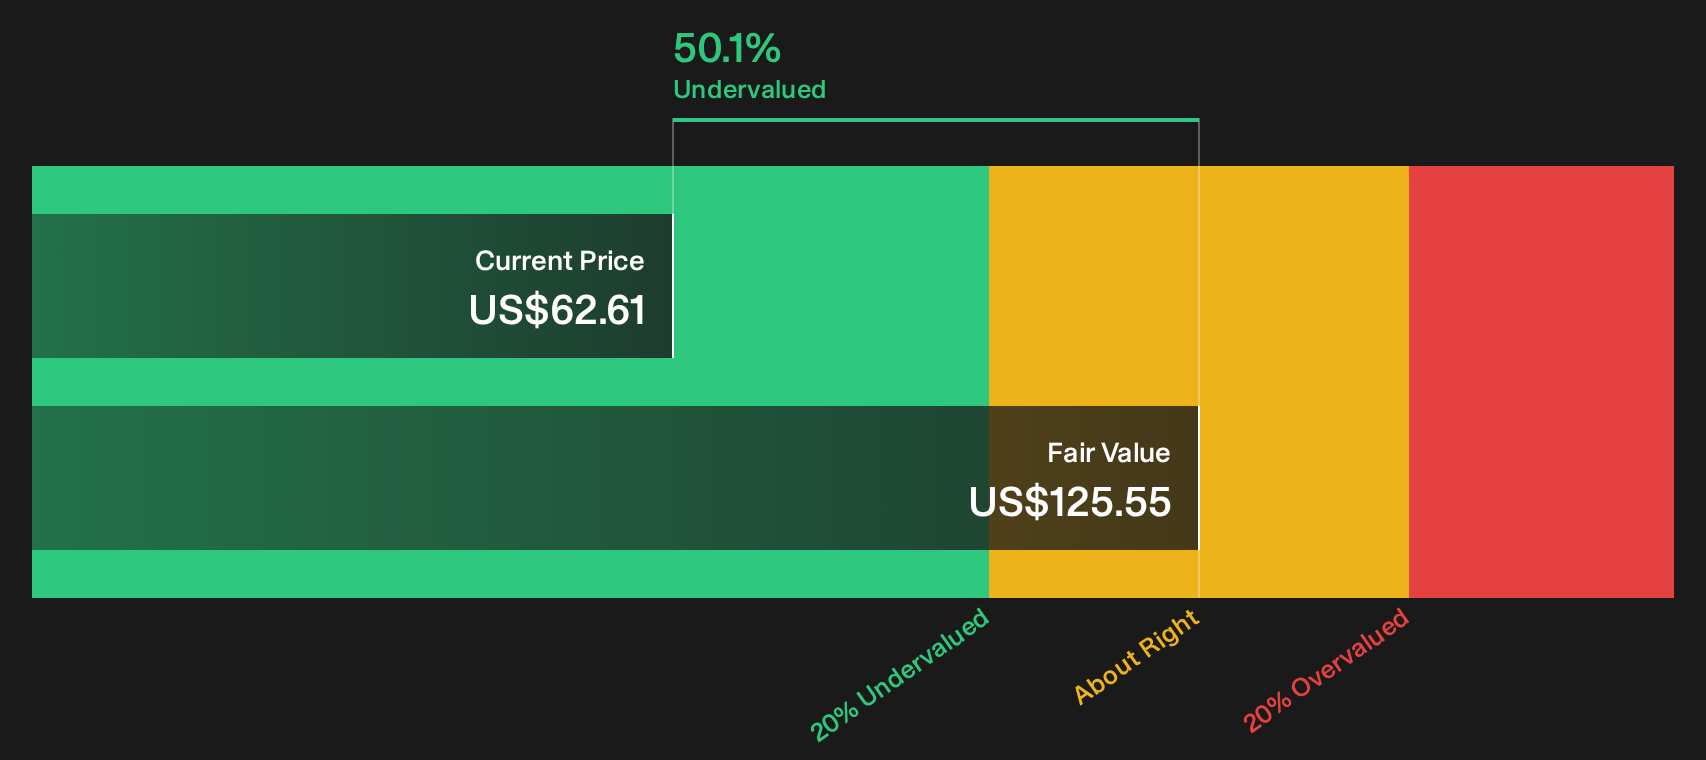
The SWS DCF model points to a fair value of $125.55 for Solaris Energy Infrastructure versus the current $62.61, which implies the shares screen as undervalued even more than the analyst narrative suggests. If cash flows come in below the model, that gap could reflect expectations rather than opportunity.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Conflicted by the mix of enthusiasm and caution around Solaris Energy Infrastructure? Act quickly, review the data, and weigh both sides using our 3 key rewards and 4 important warning signs.
Looking for more Solaris Energy Infrastructure style ideas?
If you stop with Solaris Energy Infrastructure, you risk missing other opportunities that fit your goals, risk appetite, and income needs across the wider market.
- Target potential mispricing by scanning a focused set of companies that appear cheap relative to their fundamentals with the 33 high quality undervalued stocks.
- Build more resilience into your portfolio by hunting for businesses with stronger balance sheets and sturdier finances using the list of solid balance sheet and fundamentals (25 results).
- Boost your income options by reviewing a curated group of higher yielding payers that screen for sustainability with the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com