
What OFG Bancorp (OFG)'s Dividend Hike Means For Shareholders
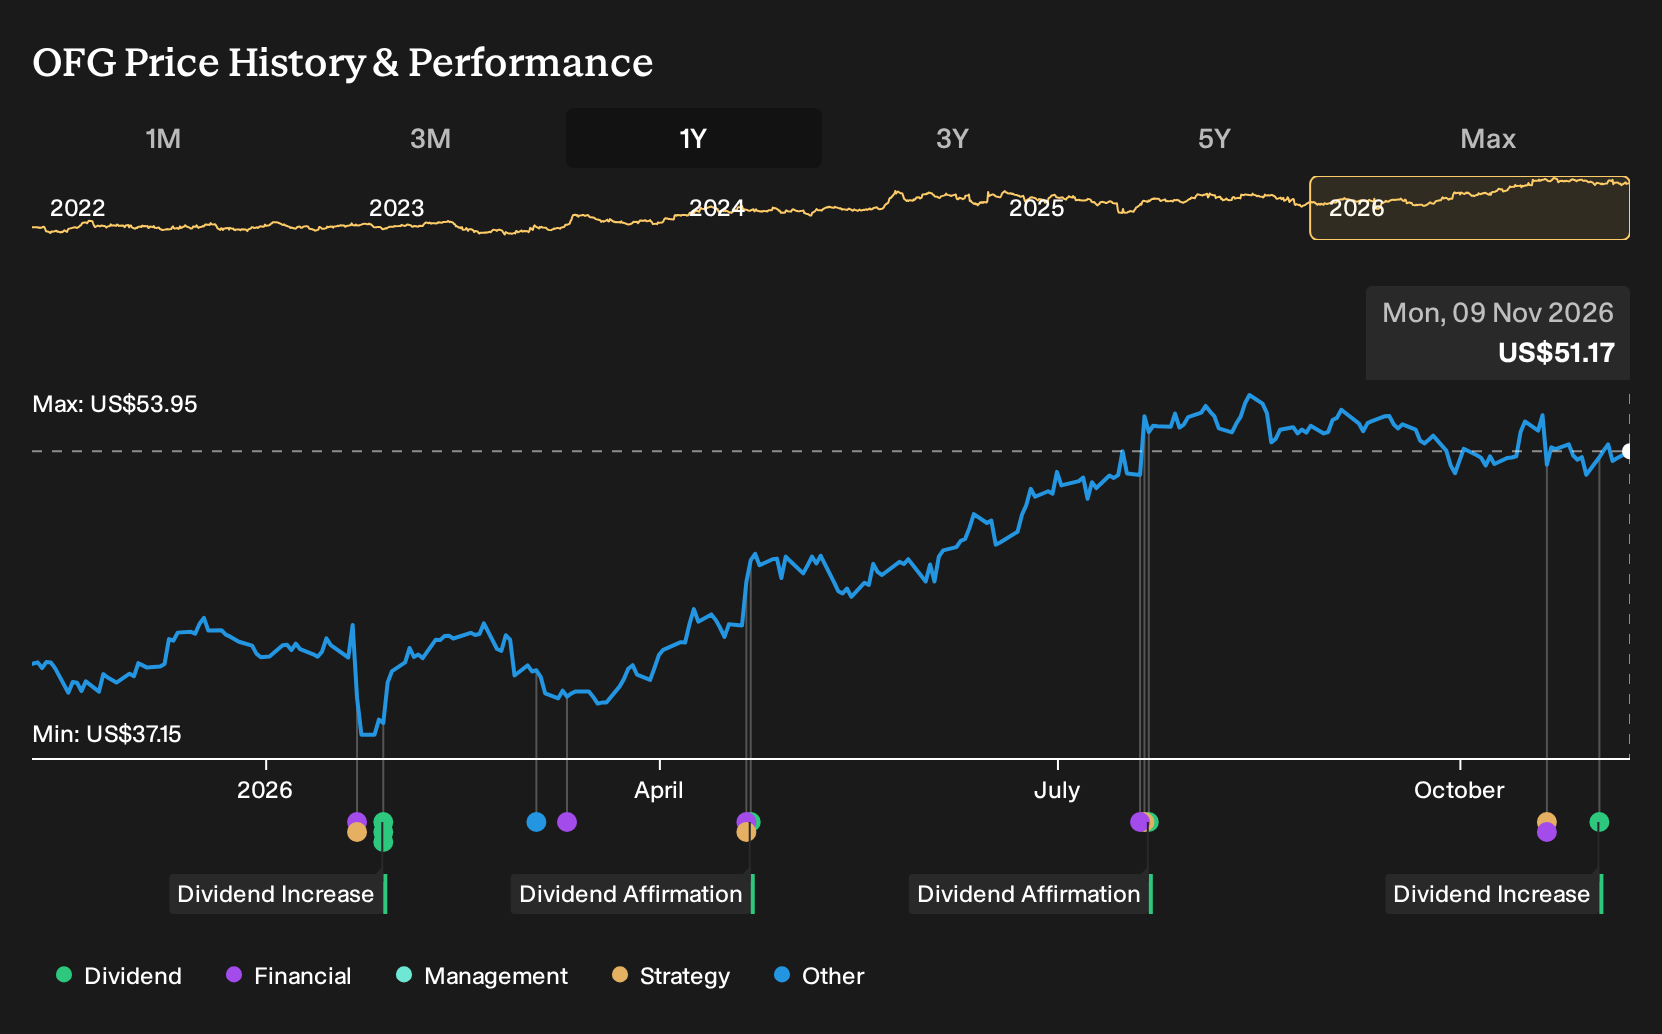
- OFG Bancorp reported that its Board of Directors raised the regular quarterly cash dividend by 14% to US$0.40 per common share for the quarter ended December 31, 2026. The dividend is payable on January 15, 2027, to holders of record as of December 31, 2026.
- The richer payout increases the cash yield drawn from OFG Bancorp's existing earnings base. This can matter for investors comparing this bank to peers with similar P/E ratios and capital return policies.
- This 14% increase in the quarterly dividend may influence how investors view OFG Bancorp's investment narrative around capital returns.
OFG Bancorp Investment Narrative Recap
For OFG Bancorp, the big-picture belief is that its Puerto Rico focused model, digital expansion, and loan pipeline can keep supporting earnings and capital returns over time. The analyst consensus Narrative on Simply Wall St expects revenue growth but points to earnings drifting lower, so pressure on net interest income and margins stays front of mind.
The 14% dividend increase does not remove the key short term swing factor, which is how net interest margin trends against funding costs after prior pricing concessions. It also does not mute the biggest risk, which is OFG Bancorp's heavy exposure to Puerto Rico's economic and political shocks and their impact on credit quality.
The most relevant backdrop for this dividend decision is management's existing capital return capacity. Analysts highlight strong capital ratios, a quarterly dividend that was previously US$0.35, and a US$200 million buyback authorization with most of it still available. That toolkit gives the board flexibility to adjust between cash payouts and repurchases.
For you as a shareholder, the higher US$0.40 dividend fits into a story that already relied on capital returns as a key catalyst. Execution still depends on digital banking traction, the roughly US$3b Puerto Rico project pipeline, and core deposit growth supporting a 5.45% net interest margin, while offsetting projected net interest income pressure and regional concentration risk.
OFG Bancorp's narrative projects US$826.7 million revenue and US$205.4 million earnings by 2029. This is based on an assumption of 8.3% yearly revenue growth and an earnings decline of about US$15 million from current earnings of US$220.4 million.
Uncover why OFG Bancorp's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about US$56.50 up to roughly US$121.27, so you are seeing very different views on OFG Bancorp. Consider that spread alongside Puerto Rico concentration risk and the dividend increase, then explore more Community viewpoints before shaping your own stance.
Explore another OFG Bancorp fair value estimate, including one that suggests there could be as much as 137% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your OFG Bancorp research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for OFG Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OFG Bancorp's overall financial health at a glance.
Looking For More OFG Bancorp Style Income Ideas?
If you like the income and capital return angle around OFG Bancorp but want to widen your watchlist, the Simply Wall St Screener can help you line up other candidates with similar traits or very different profiles for comparison.
- For investors who want income that aims to be both high and more resilient, review a curated set of 6 dividend fortresses that focus on yield and balance sheet strength.
- If quality at a reasonable entry point is your priority, scan a hand picked group of 33 high quality undervalued stocks that combine fundamentals with pricing that some investors may find appealing.
- To cast a wider net beyond widely followed tickers, check a targeted pool of 19 high quality undiscovered gems that may not yet be on every income or total return investor's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com