
Alibaba (BABA) Stock Could Still Sit Below Fair Value On AI Chip Supply Pressure
Alibaba Group Holding has had a mixed run in recent years, and the swings in its share price are pushing investors to ask whether the current US$105.38 level is adequately backed by the earnings the business is producing today.
- Over the past 3 years the stock has returned 36.0%. This puts the spotlight firmly on whether that journey lines up with the strength and resilience of Alibaba's profit stream.
- Recent news around constrained access to Nvidia AI chips and increased spending on global cloud and data center build out can influence how quickly Alibaba converts its AI and cloud ambitions into earnings and when those cash flows may materialize.
- The analysts covering Alibaba Group Holding have run their own numbers. See what analysts think Alibaba Group Holding's shares could be worth.
For investors, the debate is whether Alibaba's current share price is properly supported by its earnings when judged against the Fair Ratio benchmark.
If you are weighing Alibaba Group Holding against other ways to play AI infrastructure, a focused stock screen built around 53 AI infrastructure stocks can be a useful second starting point for research.
Is Alibaba Group Holding Still Cheap on Earnings?
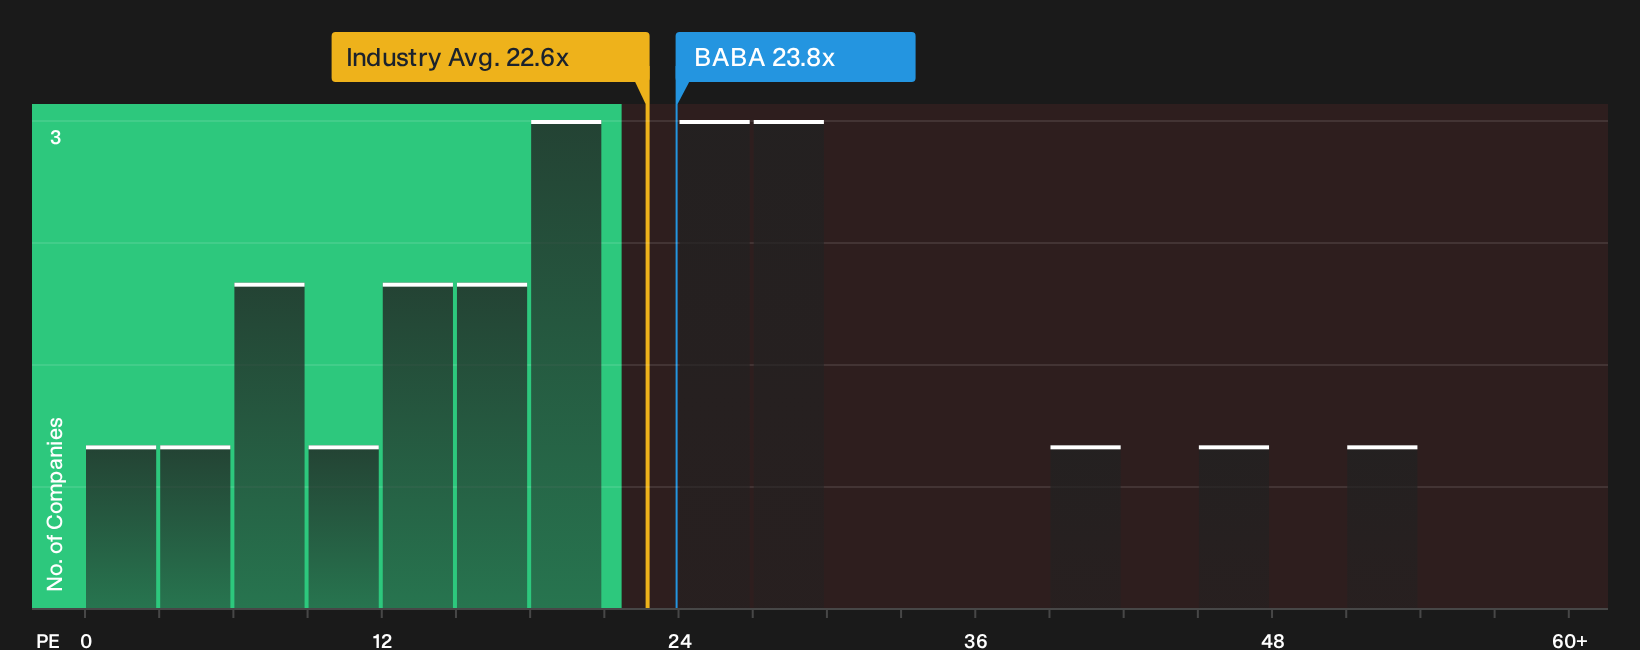
The P/E ratio suits Alibaba Group Holding because investors are mainly weighing the earnings power of its e commerce and cloud franchises. At a current P/E of 23.8x, Alibaba trades slightly above both its direct peer average of 23.0x and the broader Multiline Retail industry on 19.8x. That spread suggests the market is willing to pay a modest premium for the business compared with many listed retailers and platform operators.
Because the Fair Ratio benchmark incorporates Alibaba's growth profile, margin structure, scale and risk, it points to a higher multiple than where the stock trades today. Despite recent headlines about limited access to Nvidia AI chips and rising cloud capex, the current P/E still prices Alibaba at a discount to what that tailored benchmark would imply for its earnings stream. Explore the numbers behind Alibaba Group Holding's P/E valuation.
The Alibaba Group Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Alibaba Group Holding leaves off. They spell out which combinations of future growth, profitability and earnings power would need to hold for the shares to look meaningfully cheaper or more expensive than today. Each scenario links a fair value estimate to a concrete story about Alibaba Group Holding's possible catalysts and pressure points, so you can track over time which version of events seems to be taking shape.
One of the top community narratives on Alibaba Group Holding: 56% undervalued
According to alexandru_g3, a Simply Wall St Community investor who wrote the Narrative, many investors are still overlooking key parts of Alibaba's ecosystem.
"The thesis is that investors today are buying a leading e commerce platform, one of the world's largest cloud businesses, a major AI player, a significant stake in a fintech giant..."
Discover why this Narrative puts Alibaba Group Holding at 56% undervalued.
One more Alibaba Group Holding check that belongs next to the earnings multiple
The last piece many investors skip is who actually pulls the levers at Alibaba Group Holding, how they are rewarded and what that says about whose outcomes really come first. See who runs Alibaba Group Holding and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com