
Learn Why The Bull Case For Cullen Frost Bankers (CFR) Could Change Following Raised 2026 Guidance
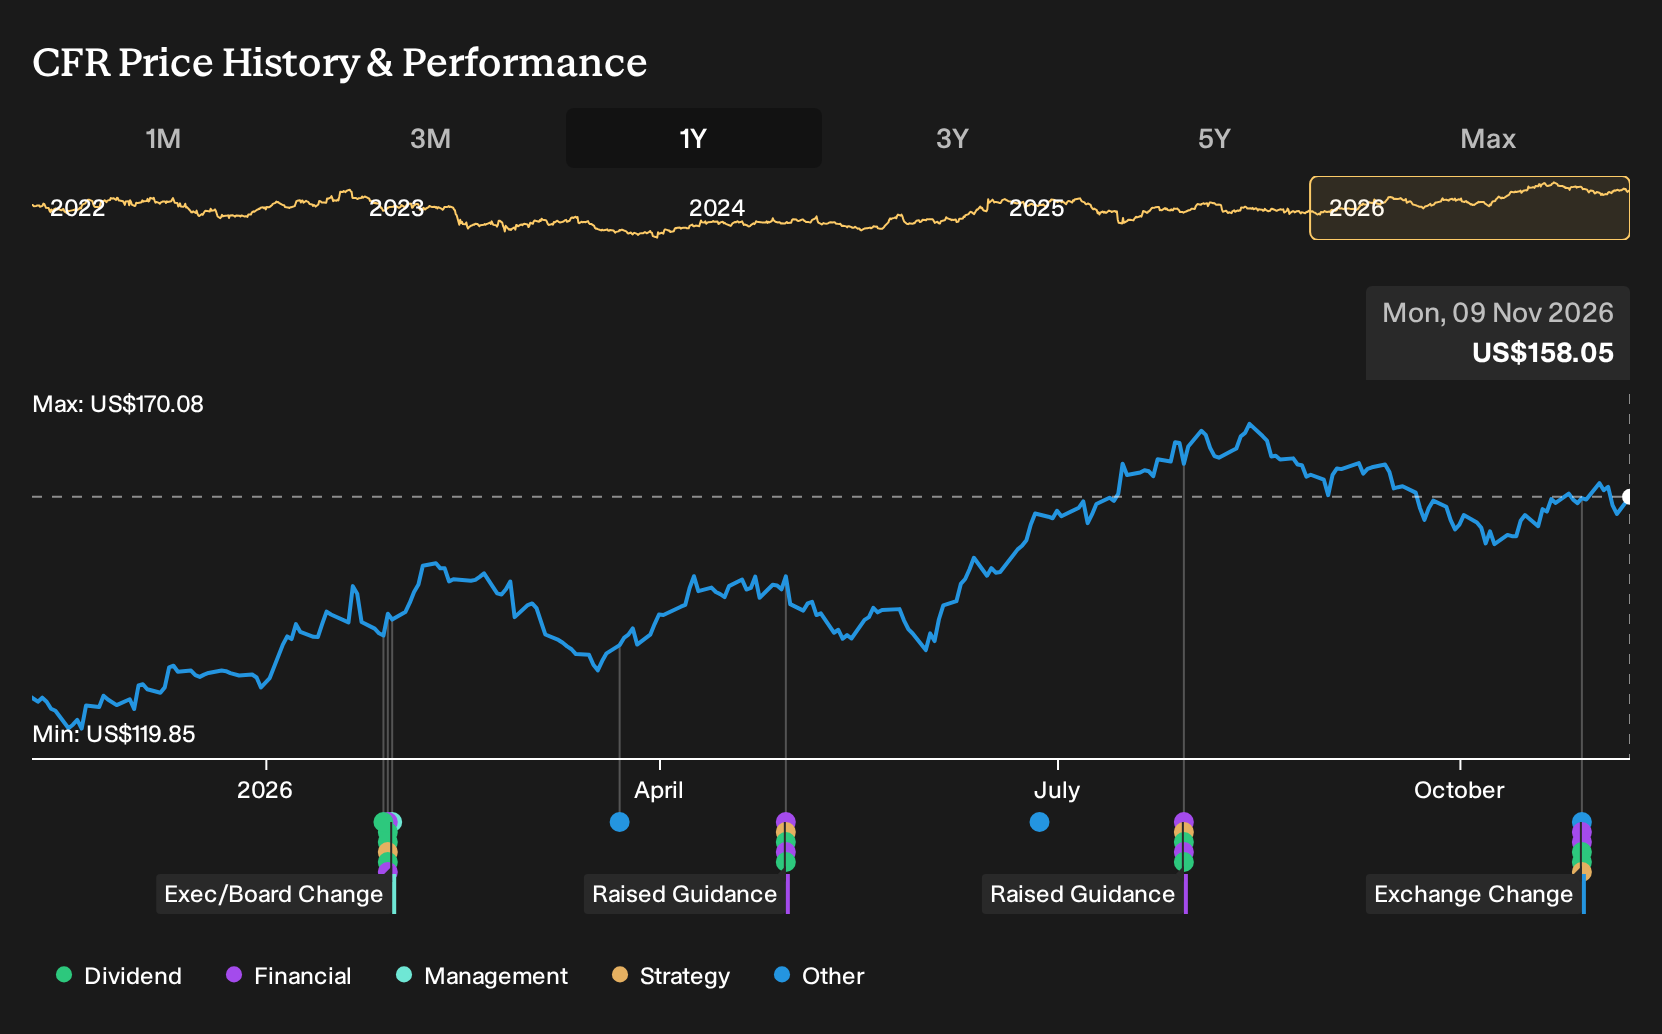
- Cullen/Frost Bankers reported third quarter 2026 net interest income of US$467.87 million and net income of US$180.21 million, and raised full year 2026 net interest income growth guidance to a range of 5% to 5.5%.
- Alongside higher earnings guidance, Cullen/Frost Bankers continued capital returns through share repurchases totaling US$175.03 million and affirmed both common and preferred dividends payable on December 15, 2026.
- We will look at how Cullen/Frost Bankers’ higher 2026 net interest income guidance reshapes the investment narrative built around its Texas franchise.
Cullen/Frost Bankers Investment Narrative Recap
To own Cullen/Frost Bankers, you need to be comfortable with a Texas centered model that leans on relationship banking, steady loan growth and branch expansion rather than rapid revenue acceleration. The analyst consensus Narrative on Simply Wall St leans on that formula. The higher 2026 net interest income guidance supports that story in the near term, while rising net charge offs keep credit quality as the key short term risk.
The most important swing factor right now is whether Cullen/Frost Bankers can keep net interest margin within guidance while competing for deposits in crowded Texas markets. Higher credit costs or weaker loan pricing could offset the guidance uplift. If that happens, the core thesis around operating leverage and steady earnings progress would look less reliable.
The raised net interest income growth range for 2026 to 5% to 5.5% is the announcement that ties closest to the current catalyst debate. Management kept its net interest margin outlook unchanged, pointing to an expected improvement of about 10 to 13 basis points compared with the 2025 level of 3.66%.
For you, the question is whether Cullen/Frost Bankers can deliver that guidance while expanding in Texas, funding mortgage and commercial pipelines and competing on price without eroding returns. Any sustained increase in net charge offs from the US$8.36 million reported in the third quarter of 2026, or heavier spending on new branches and technology, would test that balance.
Cullen/Frost Bankers’ current analyst narrative points to revenues of US$2.6b and earnings of US$716.4 million by 2029, based on an assumed 5.1% yearly revenue growth rate and a move in profits from US$669.4 million today to that 2029 consensus level. This represents an earnings increase of about US$47 million over the period.
Uncover how Cullen/Frost Bankers' fair value indicates an 11% potential upside to its current price before enthusiasm for Cullen/Frost Bankers closes that gap.
Exploring Other Perspectives
Fair value estimates for Cullen/Frost Bankers from 2 private members of the Simply Wall St Community span roughly US$175 to US$260 per share, so views differ widely. Those opinions predate the raised 2026 net interest income guidance and recent buybacks, while Texas concentration and credit costs keep the risk side of the debate alive.
Explore another Cullen/Frost Bankers fair value estimate, including one that suggests it could be worth just $174.86.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent research.
- A great starting point for your Cullen/Frost Bankers research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cullen/Frost Bankers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which may help you evaluate Cullen/Frost Bankers' overall financial health at a glance.
Looking for more Cullen/Frost Bankers style ideas?
If you like the consistency and balance sheet focus of Cullen/Frost Bankers, it can help to line it up against other candidates that share some of those traits. The Simply Wall St screener lets you filter for the mix of income, quality and risk profile that fits your approach, rather than relying on headlines or hunches.
- If capital preservation sits high on your list, compare Cullen/Frost Bankers with a curated set of companies that screen as more resilient using our 30 resilient stocks with low risk scores.
- If you want potential mispricing on your side, weigh Cullen/Frost Bankers against a hand picked group of quality businesses trading below estimated worth through the 33 high quality undervalued stocks.
- If regular cash payouts matter most to you, line up Cullen/Frost Bankers beside income focused candidates sourced from the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com