
How Upgraded Guidance At Sekisui Chemical Shares Has Changed Its Investment Story
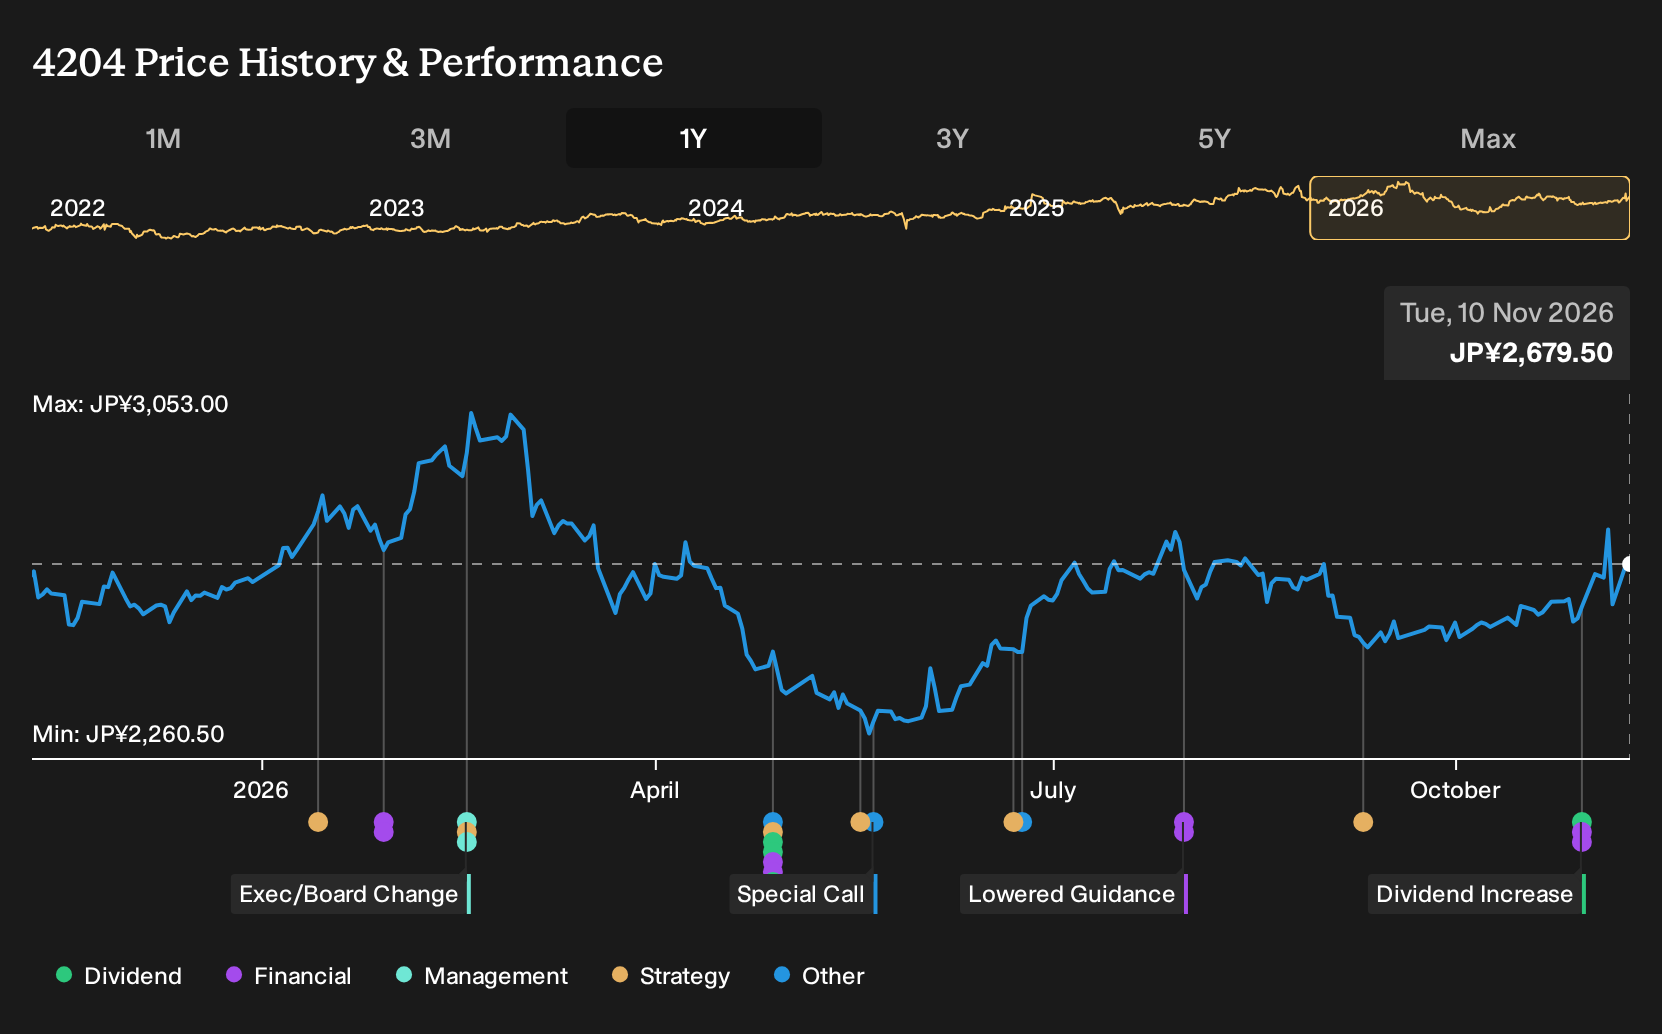
- Sekisui Chemical reported half year sales of ¥701,706 million, net income of ¥34,791 million, basic EPS of ¥86.16 and declared an interim dividend of ¥41 per share for the period ended September 30, 2026.
- The slightly higher interim payout sits alongside full year guidance that now calls for increased net sales and operating profit. This signals a focus on profitability and shareholder returns even as management cites uncertain market conditions.
- We will look at how Sekisui Chemical’s investment narrative is affected by the higher interim dividend and upgraded full year guidance.
Sekisui Chemical Investment Narrative Recap
To own Sekisui Chemical, you need to believe its shift toward higher value housing, infrastructure and materials can offset soft spots in Japanese housing, electronics and medical demand that the analyst consensus narrative on Simply Wall St highlights. The upgraded full year sales and operating profit outlook points to a business that is still finding room to improve spreads and product mix despite those headwinds.
The key short term swing factor remains execution in high performance plastics and housing, where weaker smartphone and auto volumes and a structurally softer domestic housing market could pressure earnings. Management still flags uncertain conditions and a possible reversal of pre emptive demand in the second half, so the catalyst is operational follow through rather than headline guidance alone.
The most relevant announcement for that story is the revised full year forecast, which now calls for ¥1,491,000 million in net sales and ¥123,000 million in operating profit. Profit attributable to owners of parent and EPS guidance remain essentially unchanged, so the focus shifts to whether higher sales and better spreads can sustain margins without relying on one off demand.
For you as a shareholder, the interest is in how this guidance lines up with the plan to lean on high value housing, infrastructure renewal products and advanced materials. If smartphone, auto and medical testing demand stay weaker for longer, as flagged in the risk sections, the upgraded outlook increases the pressure on Sekisui Chemical to deliver operational efficiency and product mix improvement to keep that narrative intact.
Sekisui Chemical's current earnings are ¥74.8 billion and analysts are assuming revenue will grow by 5.8% annually, with consensus forecasts pointing to revenue of ¥1,581.9 billion and earnings of ¥99.8 billion by 2029. This implies an earnings increase of about ¥25.0 billion from today.
Discover why Sekisui Chemical's fair value is essentially in line with its current price.
Exploring Other Perspectives
Payout policy is the big swing factor in the alternate view. The most optimistic analysts already expected Sekisui Chemical to reach around ¥1,626.0b of revenue and ¥101.5b of earnings by 2029, helped by aggressive dividends and buybacks. You can read this higher interim dividend as a fresh data point that might reshape those pre news assumptions.
Explore 2 other Sekisui Chemical fair value estimates, including one that suggests as much as 54% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sekisui Chemical research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sekisui Chemical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sekisui Chemical's overall financial health at a glance.
Looking for more investment ideas beyond Sekisui Chemical?
If the Sekisui Chemical story has you thinking about how dividend strength, balance sheet resilience and long term earnings power fit together, it can help to line it up against a broader watchlist of stocks with similar traits.
- For investors who care about getting paid while they wait, review companies with consistent income profiles through the 27 dividend fortresses.
- If capital preservation sits high on your checklist, focus on businesses that score well on financial resilience via the 18 resilient stocks with low risk scores.
- When you want potential mispricing backed by solid fundamentals, scan for under the radar opportunities using the 76 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com