
Earnings Beat Could Be A Game Changer For Waste Management Stock (WM)
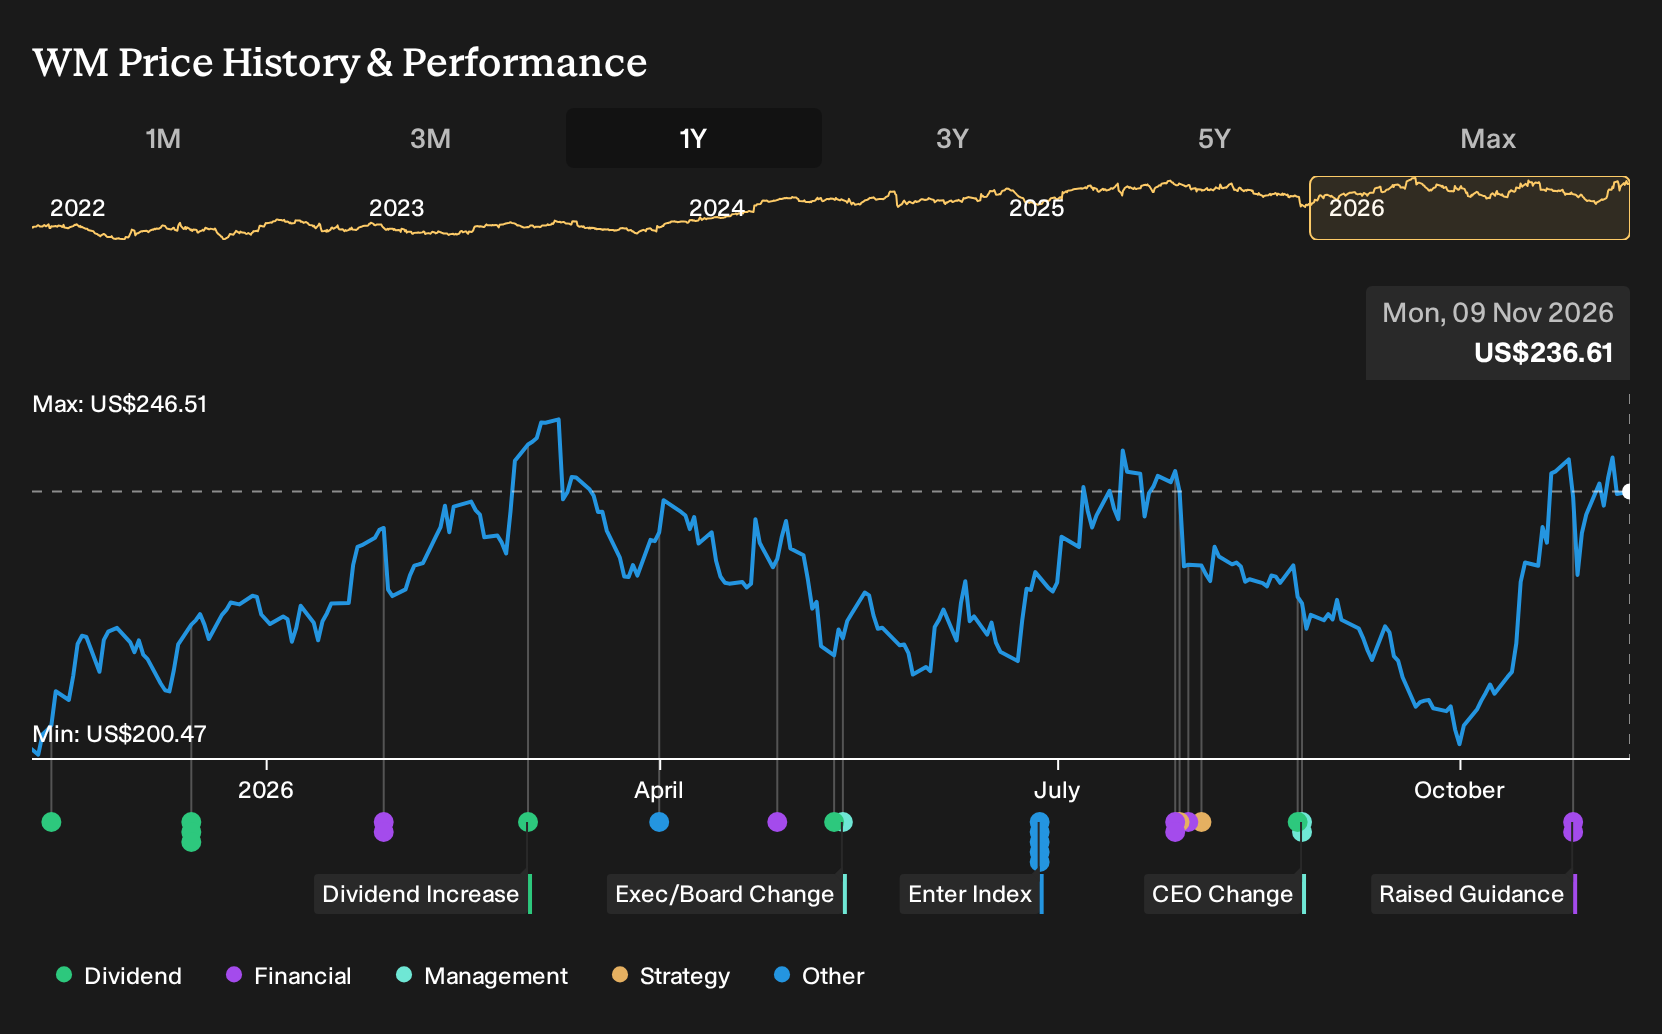
- Waste Management reported past third quarter 2026 results with US$6.846b in sales, US$820m in net income and diluted EPS of US$2.05, alongside nine month figures that showed higher sales, earnings and earnings per share compared with the prior year period.
- The company paired these stronger fundamentals with an updated outlook that points to full year 2026 revenue landing toward the top end of its US$26.275b to US$26.475b guidance range. It also continued to return capital through a US$1.606b share repurchase program that reduced the share count by 1.77%.
- The next step is to see how Waste Management's raised full year revenue guidance might influence the existing investment narrative around margins, cash generation and growth projects.
Scan beyond Waste Management and see how other high cash flow, asset heavy operators are priced today with our curated list of list of solid balance sheet and fundamentals (25 results)
Waste Management Investment Narrative Recap
To own Waste Management, you need to be comfortable with a mature, capital intensive operation that leans on pricing power, technology and its landfill and energy assets rather than rapid expansion. The analyst consensus Narrative on Simply Wall St leans heavily on the firm turning big spending on recycling, renewable natural gas and healthcare waste into steady earnings and cash conversion.
The latest quarter backs up that thesis on execution, but it does not really change the near term swing factors. The main upside catalyst still sits in ramping renewable natural gas and WM Healthcare Solutions synergies, while key risks remain soft collection volumes, potential tax credit changes and the company’s higher debt load.
The raised 2026 revenue outlook, which points toward the top of the US$26.275b to US$26.475b range, is the clearest link between this earnings release and the existing catalysts. It directly supports the idea that Waste Management can keep operating expenses controlled with technology while extracting more value from its asset base.
For you as a shareholder, that guidance update matters because it interacts with volume softness, recycling pricing and the renewable energy buildout already highlighted in the analyst consensus Narrative on Simply Wall St. It keeps the focus on execution rather than on a new story, and leaves the biggest operational risk as any sustained pressure on industrial and commercial activity that would drag on throughput and margins.
Waste Management's current earnings sit at US$2.9b, and analysts as a group expect profits to reach US$4.1b by 2029. This implies an earnings increase of about US$1.2b on the way to forecast revenue of US$30.1b in that same year, supported by an assumed 5.5% yearly revenue growth rate.
Uncover why Waste Management's fair value indicates a 7% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between about US$252.18 and US$253.84 per share, which shows how closely some private investors model Waste Management today. You still face clear disagreement on risks, from volume softness to tax credit uncertainty, so explore multiple viewpoints before anchoring on any single number.
Explore another Waste Management fair value estimate, including one that suggests potential upside of up to 7% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Waste Management research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Waste Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waste Management's overall financial health at a glance.
Looking For More Investment Ideas Beyond Waste Management?
Once you have formed a view on Waste Management, it can help to compare it with other businesses that share similar qualities or offer a different risk profile. The Simply Wall St Screener is a straightforward way to surface stocks that match the kind of balance sheet strength, cash generation or income profile you want in your portfolio.
- If you care most about resilient balance sheets and strong fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can handle shocks without stretching finances.
- For investors who put capital preservation first and want fewer surprises, filter the market using 30 resilient stocks with low risk scores that score well on stability metrics.
- If you would like to pair quality with income, consider stocks offering solid yields and dependable payouts by reviewing a focused 6 dividend fortresses built around higher dividend thresholds.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com