
Did Board Probe Just Shift Nvidia's (NVDA) Investment Narrative?
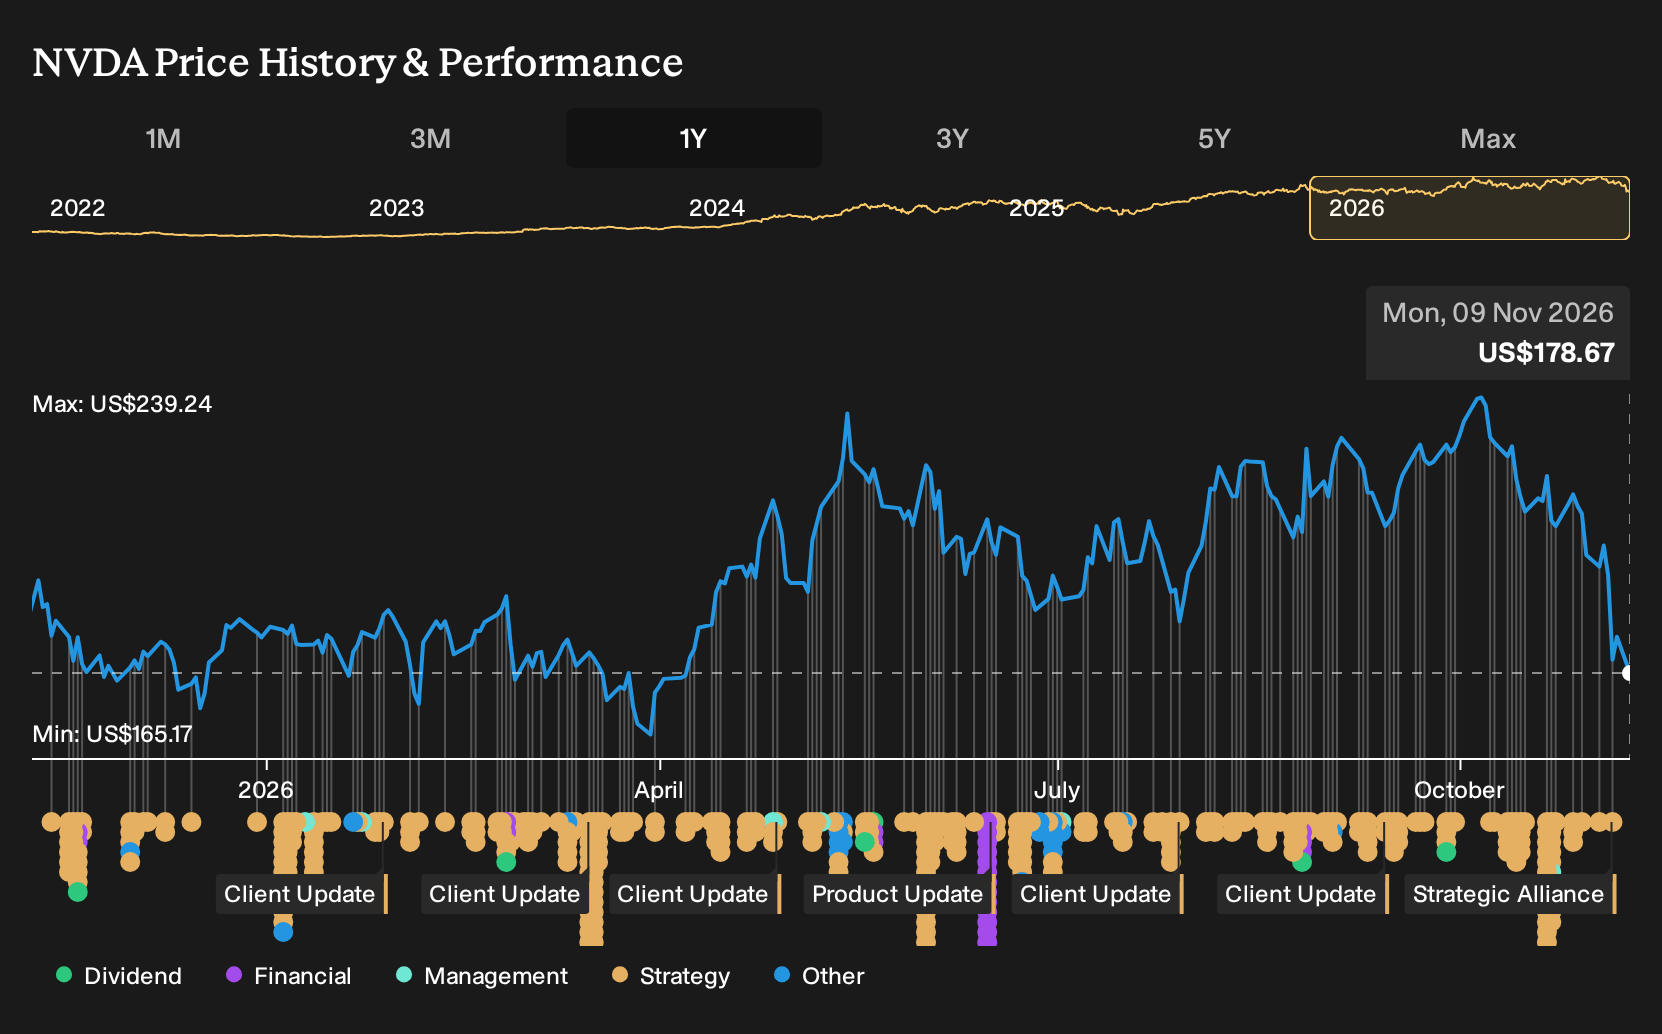
- Nvidia’s board has launched an independent investigation into CEO Jensen Huang’s past relationship with an individual U.S. officials suspect of Chinese intelligence ties. This raises questions about governance, export-control compliance and how the firm manages access to sensitive AI technology.
- The controversy has triggered class-action litigation, political scrutiny and succession planning concerns at Nvidia. This has put board oversight and key-person risk under the microscope at a moment when the chipmaker is deeply embedded in global AI infrastructure and national security debates.
- The focus now shifts to how Nvidia’s AI powerhouse narrative intersects with the board’s probe into Huang’s relationship and related governance risk.
Spread your risk beyond one AI heavyweight by scanning a hand-picked 30 resilient stocks with low risk scores that can help balance out the governance and key-person risk now hanging over Nvidia.
NVIDIA Investment Narrative Recap
To own NVIDIA today, you need to believe its AI data center engine keeps driving the story. According to oscargarcia, an investor in the Simply Wall St Community, NVIDIA is the platform play in AI, with GPUs, CUDA software and networking sold as a full stack. In the near term, the operating focus is whether hyperscalers and enterprises keep committing to large AI infrastructure orders despite governance headlines and tighter data center scrutiny.
The key short term catalyst is the upcoming earnings and guidance on AI infrastructure demand, margins and supply capacity. The biggest current risk sits in governance and export control scrutiny tied to the CEO probe, alongside already high expectations incorporated into revenue and earnings forecasts. If customers, regulators and key partners stay engaged, the operational impact from the scandal may be limited.
Among recent announcements, the NVIDIA, Rebellions and SK Telecom agreement on Korea’s sovereign AI infrastructure speaks directly to the resilience of NVIDIA’s operating pipeline. It indicates that customers and governments are still designing long dated projects around its platform, from NVLink Fusion interconnects to MGX rack designs, even as governance questions surround leadership.
For you as an investor, that collaboration matters because it touches several catalysts at once. It extends NVIDIA’s reach into custom XPUs, embeds its software and networking more deeply in another region’s AI plans, and adds another large scale reference for data center operators. On the risk side, sovereign AI projects can heighten political and export control visibility at the same time the company is under investigation, which could make execution and timelines more sensitive to regulatory shifts.
Using revenue growth of 7.5% a year and a future profit margin of 51.7%, oscargarcia frames NVIDIA’s fair value at US$280.00. They argue that this reflects a mature but still AI centric business that monetizes GPUs, software and full stack infrastructure at very high profitability.
Uncover why NVIDIA's fair value indicates a 57% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest NVIDIA analysts were already more worried about export controls and China before this scandal, even while penciling in revenue reaching about US$705.9b and earnings of US$375.5b by 2029. That is a far more cautious story than the baseline, and this new governance shock could easily push those views in either direction.
Explore 91 other NVIDIA fair value estimates, including one that suggests it could be worth just $205.27.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so trust your own research and instincts.
- A great starting point for your NVIDIA research is our analysis highlighting 4 key rewards and 2 important warning signs that could factor into your investment process.
- See our latest analysis for NVIDIA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review NVIDIA's overall financial profile at a glance.
Looking for more ideas beyond NVIDIA?
Once you have formed a view on NVIDIA, it can help to spread your attention across other opportunities that match different risk and income profiles. The Simply Wall St Screener lets you filter for stocks that fit your own criteria rather than relying solely on a single AI leader.
- If capital preservation matters most right now, consider using a screener focused on stability and balance sheet strength through a 30 resilient stocks with low risk scores that filters for companies with more resilient profiles.
- Income focused investors who want cash returns from their holdings can scan for reliable payers by using a curated 6 dividend fortresses that concentrates on higher yielding businesses.
- For readers who want to look beyond the usual tickers, there is a hand picked 19 high quality undiscovered gems that highlights under followed companies with stronger fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com