
3 Bank Stocks That Could Benefit If The Fed Turns More Hawkish
When a Federal Reserve governor openly floats a bigger rate hike if October core CPI lands near 0.3%, rate sensitive bank stocks suddenly move from background noise to front of mind. Faster policy tightening can reshuffle which lenders benefit as loan yields and deposit costs reset at different speeds. This article unpacks that theme and highlights three regional and mid sized banks that appear most exposed to this latest Fed signal.
The three stocks covered below are just a sample of this theme, and the full screen surfaced 47 more regional and mid sized banks with asset sensitive net interest margins that carry similarly detailed stories. To go straight to the source, identify potential winners, and analyze each balance sheet setup in context, head into the U.S. Regional and Mid-Sized Banks with Asset-Sensitive Net Interest Margins screener.
Peoples Bancorp (PEBO)
Peoples Bancorp plugs directly into the asset sensitive theme of this screener, with a community banking franchise that leans on interest earning loans and securities and a wide range of fee based services to power earnings as rate policy shifts.
Peoples Bancorp runs a broad commercial and consumer banking operation, generating about $443 million from community banking in the United States, and has a market value of roughly $1.36 billion.
"Scaling Peoples Bancorp through the pending Capital Bancorp and Citizens National acquisitions is expected to lift the company to about $14b in assets with $10b in loans and $11b in deposits, which could support higher earnings power and more resilient revenue."
What happens to Peoples Bancorp margins if a single key assumption about how quickly deposit costs move against loan yields breaks?
If that funding swing matters for you, read the full narrative for Peoples Bancorp to see how deposit repricing, capital use, and fee income could be quietly affecting Peoples Bancorp earnings potential.

Third Coast Bancshares (TCBX)
Third Coast Bancshares leans into the screener theme as a Texas lender geared toward small and mid sized businesses, where a lot of commercial borrowing tends to carry floating rates that reset quickly when the Fed moves. The analyst consensus Narrative on Simply Wall St argues this can be a meaningful earnings lever.
Third Coast Bancshares runs a Texas focused commercial bank serving small and medium sized businesses and professionals, generating about $243 million from community banking in the United States, and the stock is valued by the market at roughly $646 million.
"Strong ongoing loan growth and robust pipelines, supported by recent C&I expansion of about $187 million in 2Q26 and continued guidance for quarterly loan growth, position Third Coast Bancshares to keep building interest earning assets and support revenue over time."
What really counts for Third Coast Bancshares is how one quiet funding pressure shapes the gap between repricing loan yields and deposit costs.
That funding pressure is the real swing factor, and the full narrative for Third Coast Bancshares lays out how repricing could either accelerate earnings power or quietly cap Third Coast Bancshares momentum.

Live Oak Bancshares (LOB)
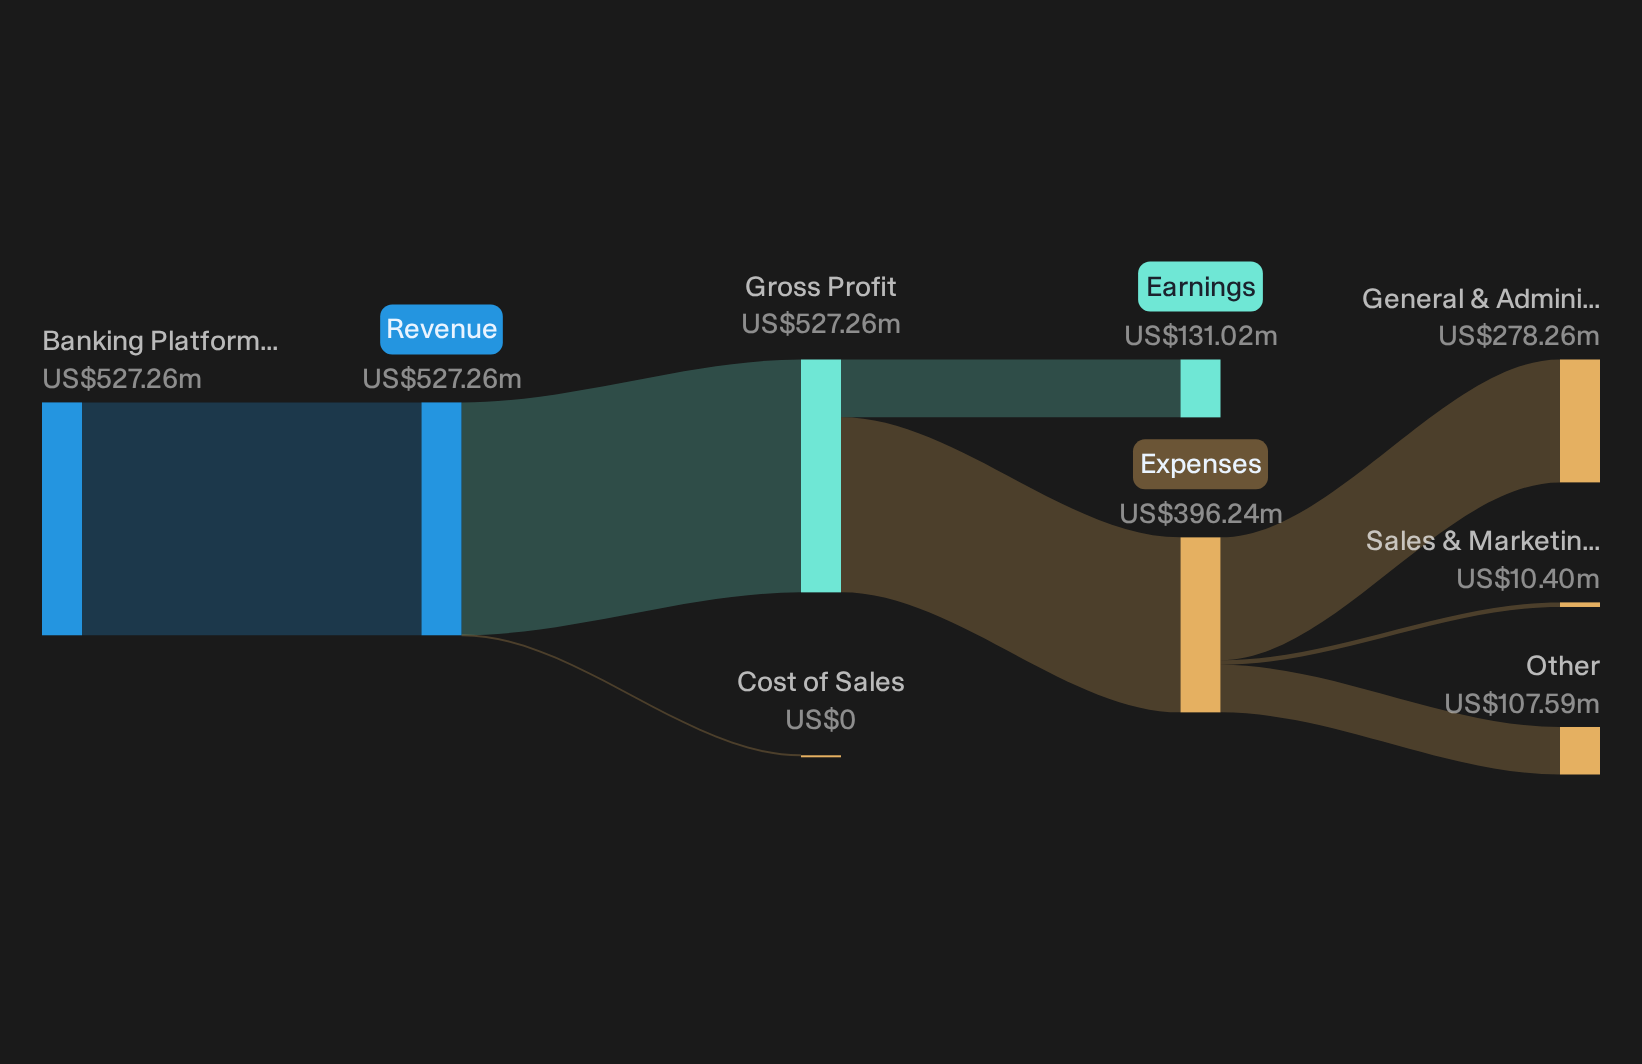
Live Oak Bancshares focuses on lending to small and medium sized businesses across the United States, which ties directly into the asset sensitive theme, with about US$527 million from its small business banking platform and a market value of roughly US$1.6b.
For investors watching how higher Fed policy rates interact with small business lenders, Live Oak Bancshares sits in a sweet spot where asset sensitive loans meet relationship driven deposits. The analyst consensus Narrative on Simply Wall St points to one key engine behind that story.
"The rapid scaling of Live Oak Express and newer business checking offerings from essentially zero in 2023 to record small-dollar 7(a) production of US$82 million in Q2 2026 and US$744 million of checking and other DDA balances is widening Live Oak Bancshares’ reach with digitally oriented small businesses and can support further revenue growth and a lower funding cost over time."
The real question is how one unresolved credit and funding pressure shapes where margins and earnings settle as rate policy tightens further.
If that margin question is front of mind, the full narrative for Live Oak Bancshares shows how Live Oak Bancshares’ funding mix could be quietly accelerating or masking its earnings trajectory.
Curious About What You Might Be Missing?
Fresh ideas often move first. By the time every screener is crowded, the real breakout momentum may have already passed. Review these under the radar lists while it matters and consider getting in earlier in your research process.
- Explore potential income resilience by reviewing a curated set of cash-generating businesses through the 6 dividend fortresses before yields begin to look more similar to the broader group.
- Look for early movers in frontier computing by scanning the hand picked 25 quantum computing stocks collection while these stories may still be flying under many investors’ radar.
- Follow real-world infrastructure demand by checking the focused 42 power grid technology and infrastructure stocks group before grid upgrade themes become more widely reflected in available opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com