
Digital Turbine (APPS) Stock Looks Reasonable On Strong Q2 Results
Digital Turbine has seen its share price move sharply in recent years. This puts a spotlight on whether the current US$11.30 level is backed up by the revenue it generates. With investors reacting to fresh results and management changes, the open question is how far the stock price lines up with the sales profile of the business.
- Over the past 3 years, Digital Turbine has returned 140.4%. A lot now rests on whether its revenue base can support that kind of share price reset.
- Recent profit improvement and higher revenue have given the business more breathing room. This can influence how much value investors are willing to ascribe to each dollar of sales.
- The analysts covering Digital Turbine have run their own numbers. See what analysts think Digital Turbine's shares could be worth.
The issue now is whether Digital Turbine's current market value is justified by its sales when viewed through this single lens.
If you want to test the same sales based valuation question on a wider set of companies, compare Digital Turbine with stocks in the 33 high quality undervalued stocks.
Where Does Digital Turbine Sit on Sales?
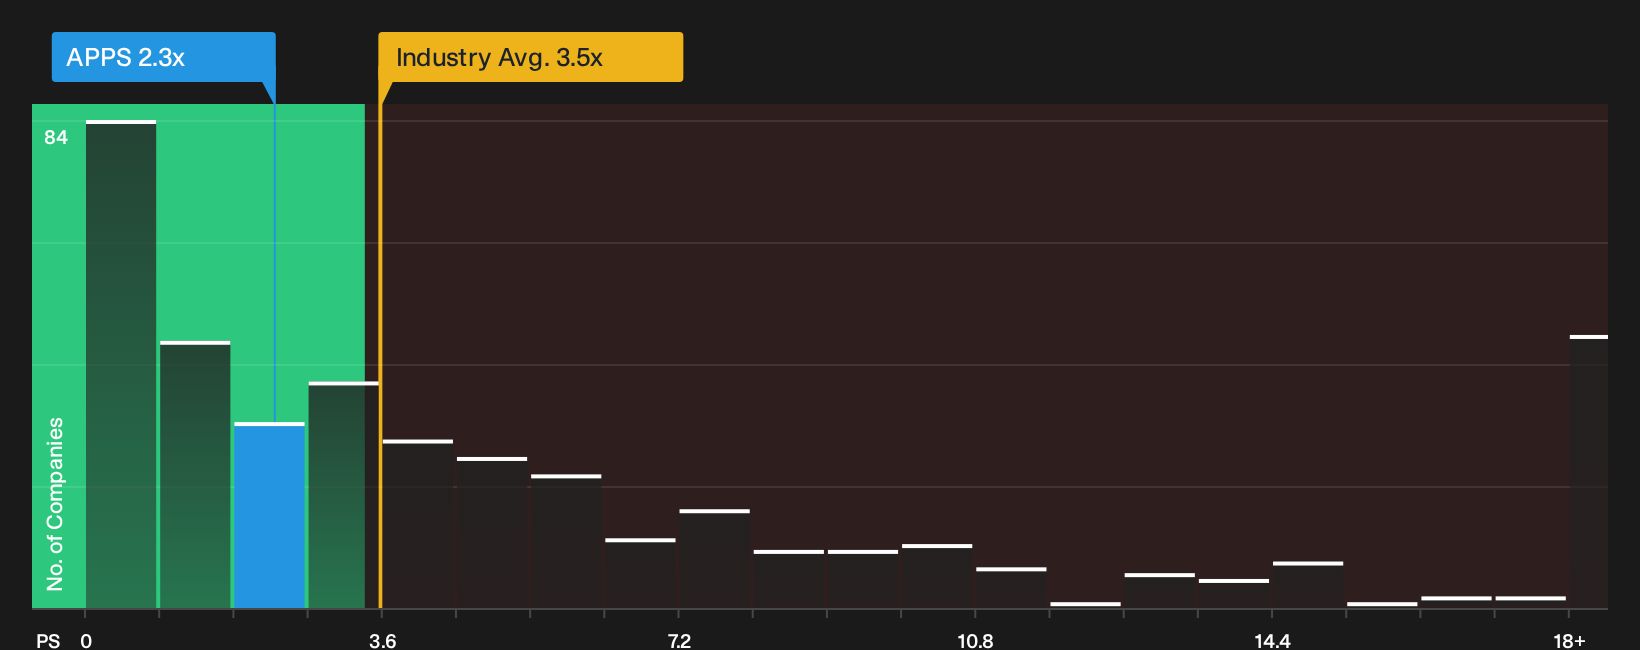
P/S suits Digital Turbine because revenue is still the cleaner yardstick than earnings for a business that only recently swung back to profit. At a P/S of about 2.3x, the stock trades slightly above the peer group average of roughly 2.1x, yet below the wider Software industry at about 3.5x, which signals investors are paying a modest premium to closer peers but not a sector level price tag.
Because the P/S is close to the fair multiple implied by the valuation model, the ratio points to a share price that looks about right against the company’s own growth profile and risk mix rather than clearly cheap or expensive. Despite the strong fiscal 2027 guidance and the recent profitability turnaround, the current P/S level still prices Digital Turbine as a mid pack Software valuation story rather than a high flying outlier. Explore the numbers behind Digital Turbine's P/S valuation.
The Digital Turbine Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Digital Turbine pick up where the P/S discussion leaves off and explain which paths for revenue, margins and future earnings would need to hold for the stock to be worth much more or much less than it is today. Instead of a single figure from a ratio or model, Narratives map the future that number relies on so you can watch how closely Digital Turbine's actual progress tracks that story on the Community page.
One of the top narratives on Digital Turbine: 34% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation suggests that the market is weighing risks around stock volatility, accounting reviews, and sentiment more heavily than factors such as the company’s recent revenue growth, margin expansion, deleveraging, and analyst price targets in the mid to high teens, which some view as supporting a bullish undervaluation perspective on Digital Turbine’s shares…"
Discover why this Narrative puts Digital Turbine at 34% undervalued.
One more crucial piece on Digital Turbine is still off the table
You have seen what the current price says about Digital Turbine today, but not how professional forecasters currently frame its prospects a few years from now. Explore where analysts expect Digital Turbine to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com