
Hesai Group (HSAI) Earnings Reset Puts Its Undervalued Narrative To The Test
Hesai Group (NasdaqGS:HSAI) just posted third quarter 2026 results, reporting sales of CNY 1,068.29 million and net income of CNY 80.79 million, which may prompt fresh investor scrutiny.
Hesai Group’s latest earnings drop into a choppy price backdrop, with the share price at US$14.31 after a sharp 16.34% gain over the past week. However, the year-to-date share price return has declined 40.57%, while the three-year total shareholder return of 43.10% points to earlier momentum that now appears to be fading as investors reassess profits against revenue growth.
Capture how Hesai Group’s earnings reset compares with other robotics and automation plays by scanning our hand picked 91 robotics and automation stocks.Hesai Group now trades well below both analyst targets and intrinsic value estimates after that earnings wobble and rapid rebound. Is the discount a signal of excessive caution, or a fair response to softer profits?
Most Popular Narrative: 44% Undervalued
The analyst consensus Narrative on Simply Wall St places Hesai Group’s fair value at $25.49, well above the last close at $14.31. This frames the recent reset as a sizeable discount rather than a marginal mismatch.
The plan for Strategic Growth Initiatives to reach about RMB 700 million revenue and breakeven in 2027, supported by the increase in 2026 SGI guidance to RMB 200 to 300 million, suggests that newer businesses such as actuation modules can move from current operating losses toward contributing to operating profit and cash flow.
See why 35 investors see Hesai Group as 44% undervalued.
Result: Fair Value of $25.49 (UNDERVALUED)
Still, the Hesai Group story can falter if lidar price competition keeps squeezing that near 40% blended gross margin, or if loss making SGI projects drag on longer than investors expect.
Find out about the key risks to this Hesai Group narrative.
Another View: Hesai Group Through A P/E Lens
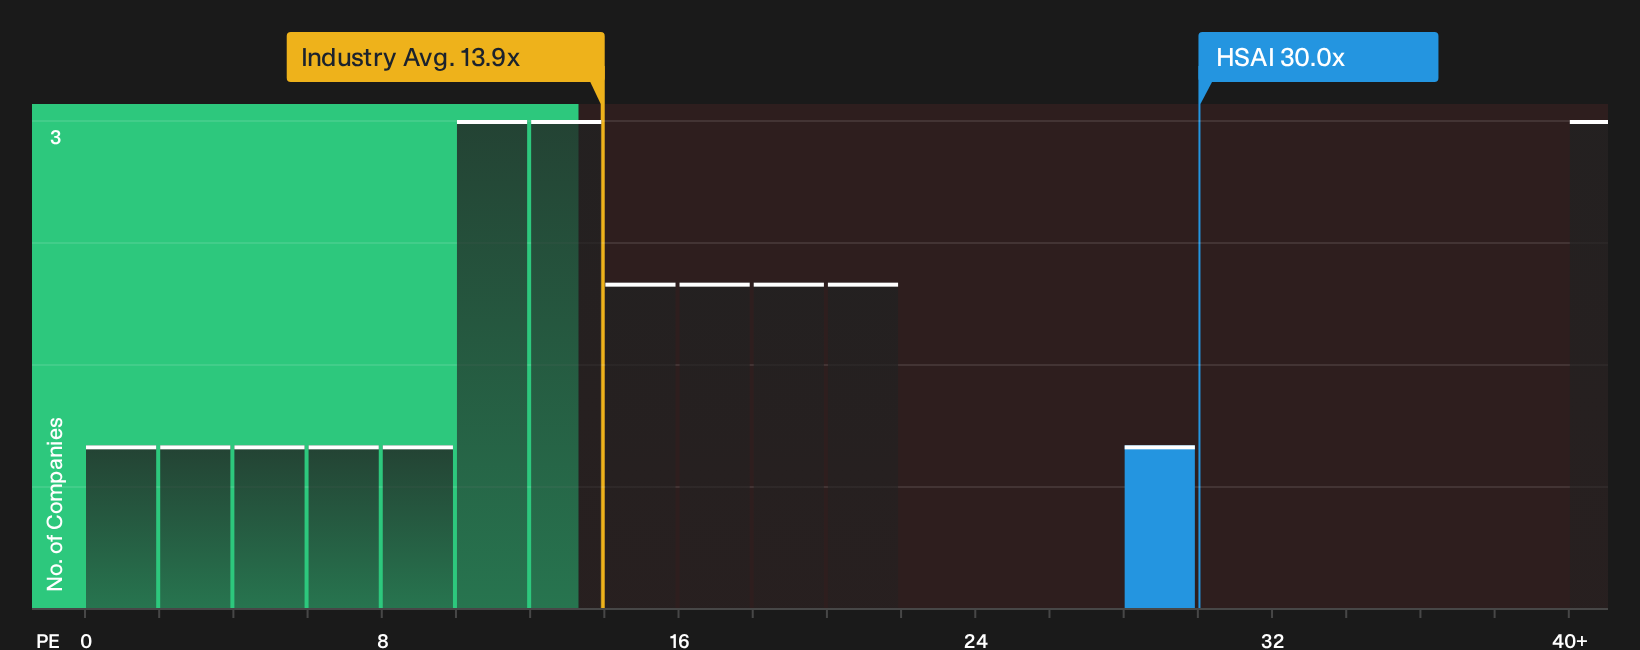
Hesai Group screens very differently once the focus shifts to its P/E ratio. The shares trade on about 30x earnings, which is more than double the 13.9x average for the US Auto Components group and slightly above the 28.5x fair ratio estimate. That premium points to less room for error if growth or margins disappoint.
To see how those earnings multiples stack up in more detail, including the gap to sector peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Hesai Group is split, with one side focused on pressure points and the other looking at potential upside. Move quickly and examine the full picture for yourself by weighing its 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Hesai Group?
If Hesai Group has your attention, do not stop there. Broaden your watchlist and give yourself more ways to put capital to work intelligently.
- Target steady compounding by scanning a curated 33 high quality undervalued stocks that combines strong business quality with prices that still lag their fundamentals.
- Prioritize resilience first and hunt through a 30 resilient stocks with low risk scores where balance sheets and risk scores do the heavy lifting before you commit capital.
- Move ahead of the crowd by assessing a 19 high quality undiscovered gems that pairs robust metrics with relatively low investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com