
Should Raised Guidance Require Action From Jazz Pharmaceuticals Stock Investors?
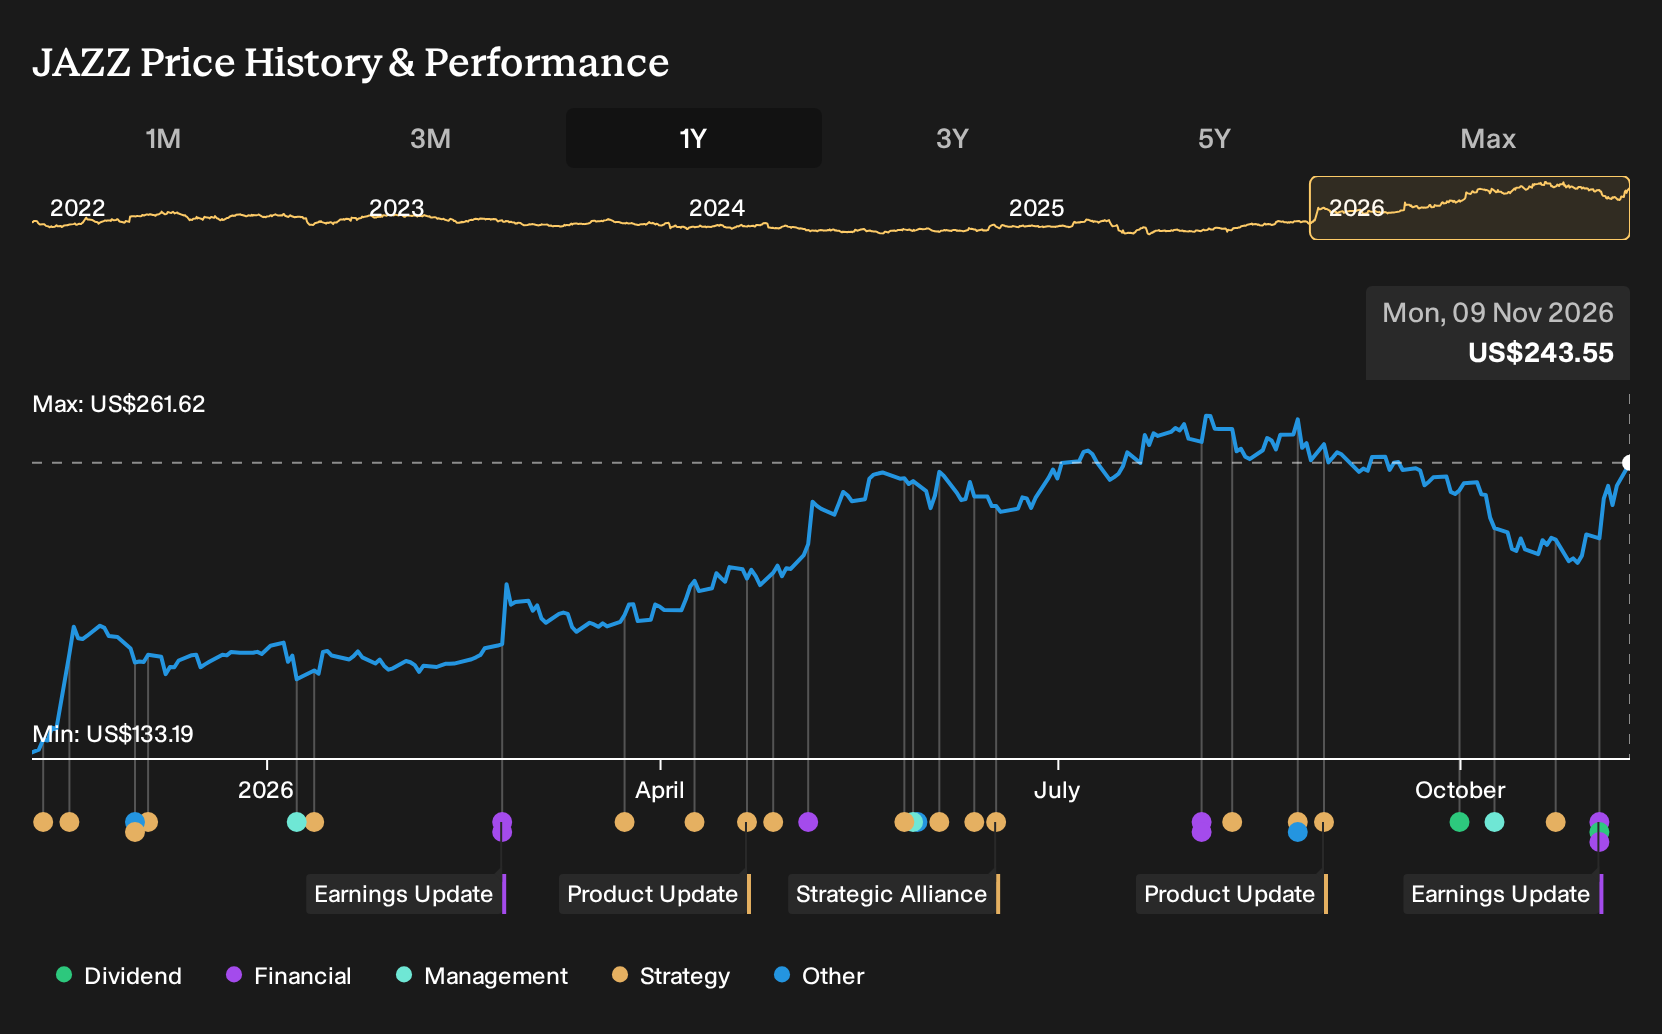
- Jazz Pharmaceuticals reported third quarter 2026 revenue of US$1,243 million and a net loss of US$483.4 million, while raising full year revenue guidance and announcing a US$500 million share repurchase program.
- The combination of higher revenue guidance and a new buyback plan highlights management’s focus on capital returns, even as near term earnings remain volatile.
- We will examine how Jazz Pharmaceuticals' raised revenue guidance influences the existing investment narrative around its oncology and sleep portfolio.
Jazz Pharmaceuticals Investment Narrative Recap
Owning Jazz Pharmaceuticals means backing a pipeline-heavy story across oncology, sleep and rare epilepsy, where execution matters more than short term earnings swings. The analyst consensus narrative on Simply Wall St leans on Ziihera expansion, continued Xywav and Epidiolex contribution, and integration of acquired assets to support that view. The recent quarter showed record quarterly revenue alongside a sizeable one-off driven net loss, so the operational question is how consistently that higher top line can be converted into cleaner profitability.
In the near term, the main catalyst remains progress across Ziihera and the broader oncology and epilepsy portfolio, including uptake in current indications and advancement of late stage programs. The biggest risk still sits with patent and competitive pressures on the sleep franchise and Jazz Pharmaceuticals' use of higher debt funding. The raised full year revenue guidance and nine month return to modest profitability help the story, but they do not fundamentally change those core drivers or threats.
The most relevant fresh data point is Jazz Pharmaceuticals' move to raise 2026 revenue guidance to US$4.78b to US$4.85b after reporting US$1.24b in third quarter revenue and a net loss of US$483.4m. That increase from the prior US$4.60b to US$4.75b range signals that management now expects stronger full year sales than previously indicated based on what is already visible inside the business.
For you as an investor, this updated outlook feeds directly into the existing catalysts around Ziihera expansion, sleep and epilepsy growth and broader international uptake. It frames the recent net loss as a period of heavier investment and one-off items rather than a simple deterioration in the underlying franchises. The operational test from here is whether Jazz Pharmaceuticals can translate that higher revenue base into more durable earnings while managing debt and generic risks.
Analysts currently model Jazz Pharmaceuticals reaching US$5.7b in revenue and US$1.7b in earnings by 2029, based on forecast yearly revenue growth of 7.4% and an earnings increase of roughly US$759m from current earnings of US$940.8m.
Uncover why Jazz Pharmaceuticals' fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on oncology risk rather than guidance upgrades. The most cautious Jazz Pharmaceuticals analysts were only penciling in revenue of about US$5.2b and earnings of roughly US$1.4b by 2029, well below the consensus path. That more muted story may shift once this stronger 2026 outlook is fully absorbed, so consider both perspectives.
Explore 3 other Jazz Pharmaceuticals fair value estimates, including one that suggests it could be worth just $242.03.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jazz Pharmaceuticals research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Jazz Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jazz Pharmaceuticals' overall financial health at a glance.
Looking for more investment ideas beyond Jazz Pharmaceuticals?
Once you have a view on Jazz Pharmaceuticals, it can help to compare it with other opportunities that share similar financial strengths or different risk profiles. The Simply Wall St Screener is built for that kind of side by side check so you can see where Jazz Pharmaceuticals fits in your wider portfolio.
- If capital preservation matters most to you, start with companies that score well on resilience and financial risk using the 30 resilient stocks with low risk scores.
- If balance sheet strength is a priority, scan a curated list of solid balance sheet and fundamentals (25 results) that can complement or contrast with your view on Jazz Pharmaceuticals.
- If you are searching for underfollowed opportunities, broaden your watchlist with a focused 19 high quality undiscovered gems that already screen well on fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com