
First GAAP Profit Might Change The Case For Investing In Unity Stock (U)
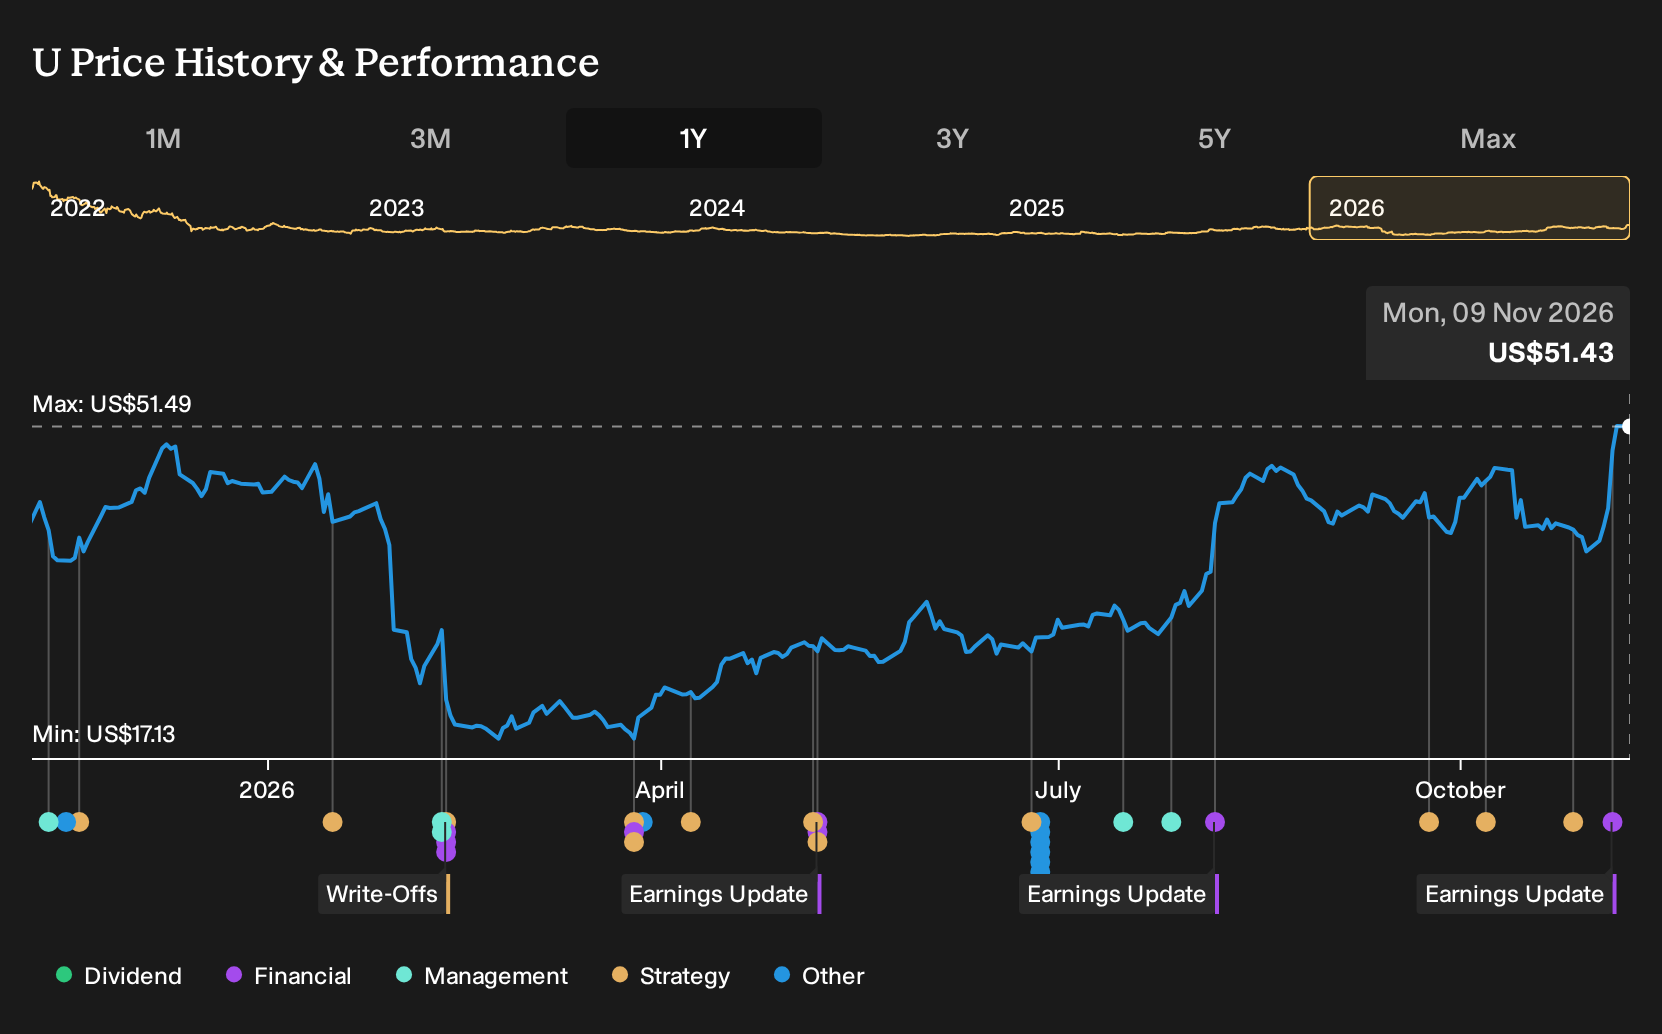
- Unity Software reported third quarter 2026 sales of US$622.09 million and net income of US$121.23 million, marking a shift from a loss in the prior year period and its first GAAP profitable quarter since the IPO.
- Management linked this profitability to AI driven products such as the Vector platform and Day 28 Optimizer, as well as a PvX partnership that offers non dilutive user acquisition financing and integrates with Unity’s Developer Data Framework.
- We will look at how Unity's first GAAP profit, supported by AI driven Vector gains, feeds back into the broader investment narrative.
See how Unity Software’s AI driven pivot compares with other fast moving platforms by reviewing our hand picked list of 53 AI infrastructure stocks in one place.
Unity Software Investment Narrative Recap
To own Unity Software, an investor needs to believe that the AI fueled Vector and Grow segment can stay healthy while the Create engine remains relevant enough to feed that ad flywheel. The Q3 2026 GAAP profit and US$622.09 million in quarterly sales help that story, but the most important near term catalyst is still consistent Vector driven revenue in upcoming quarters.
The biggest present risk is concentration. Grow contributes a large share of the top line and the arbitration over AppLovin data still hangs in the background, as wanderer, an investor in the Simply Wall St Community, argues. Any wobble in Vector usage or a legal setback could matter more to Unity Software than one profitable quarter.
The PvX partnership appears closely tied to this earnings moment because it plugs directly into Unity’s AI tools and Vector platform. PvX has already committed over US$1.3b of user acquisition financing across 17 markets and now channels some of that into studios using Unity, which can reinforce ad spend through Vector if execution stays tight.
For investors watching catalysts, this is essentially a volume and quality bet. If more qualified games tap PvX’s non dilutive funding and route campaigns through Unity’s Developer Data Framework, Vector gets richer cohorts to model and the Q3 profitability milestone may look more repeatable. If uptake disappoints or underwriting misfires, that growth flywheel may appear less secure.
wanderer’s own fair value for Unity Software lands at US$10.88, based on a model that assumes revenue grows 10.0% a year and the business eventually settles at an 11.6% profit margin, which together support a lower earnings power than the bull Vector narrative implies.
Uncover why Unity Software's fair value indicates a 79% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
You are now seeing two very different stories about Unity Software. The most optimistic analysts were already penciling in about 29.1% annual revenue growth and earnings of US$1.7b by 2029 before this Q3 profit. Those forecasts lean on ecosystem partnerships like PvX, so this fresh earnings report may push those projections to shift again.
Explore 3 other Unity Software fair value estimates, including one that suggests potential upside of up to 74% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Unity Software research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Unity Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Unity Software's overall financial health at a glance.
Looking for more investment ideas beyond Unity Software?
If Unity Software has sharpened your thinking on what you want in a business, use that momentum to scan for other opportunities that better fit your risk, income, or quality preferences with the Simply Wall St Screener.
- If you want potential value candidates with solid fundamentals, start with a curated 33 high quality undervalued stocks that match strict quality and valuation filters.
- If capital preservation ranks high on your list, focus on stability by checking a 30 resilient stocks with low risk scores that screen well on balance sheet and volatility metrics.
- If reliable cash returns appeal to you, lean into income ideas through a targeted 6 dividend fortresses that meet a 5%+ yield hurdle with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com