
Is Fervo Energy (FRVO) Undervalued After Its Q3 Report And Sharp Share Price Jump?
Fervo Energy (FRVO) is back in focus after its third quarter 2026 report, which showed sales of US$0.116 million and net income of US$11.66 million, compared with a net loss a year earlier.
The Q3 update and the ramp up of Fervo Energy's geothermal projects arrived alongside a sharp shift in sentiment, with a 1 day share price return of 26.09% and a 7 day share price return of 37.94%. However, the 90 day share price return is down 52.92% and the year to date share price return is down 68.86%, which signals short term momentum building against a still weak longer term chart.
Scan beyond Fervo Energy's latest move and compare it with hand picked clean energy players through 42 power grid technology and infrastructure stocks in the same grid and infrastructure theme.
Fervo Energy now trades far below the average analyst target, even after the latest jump. This raises a sharper question: Is the discount a genuine opportunity or a signal that the market’s caution on losses and execution risk still holds?
Most Popular Narrative: 67% Undervalued
Against the last close of $11.38, the analyst consensus Narrative on Simply Wall St anchors Fervo Energy’s fair value at about $34 per share. This frames today’s price as a steep discount and puts execution, contracts, and project timing under the microscope.
Large, long duration power purchase agreements totaling 658 megawatts and US$7.2b in contracted revenue, alongside a 3 gigawatt framework agreement with Google, provide visibility on future cash inflows and potential support for revenue growth and earnings stability.
See why 24 investors see Fervo Energy as 67% undervalued.
Result: Fair Value of $34 (UNDERVALUED)
Still, heavy planned capex of about US$1.2b and ongoing operating losses mean any project delays or financing setbacks could quickly challenge the current undervalued narrative.
Find out about the key risks to this Fervo Energy narrative.
Another View: SWS DCF Flags A Very Different Fervo Energy Story
There is a clear split emerging. While analysts on Simply Wall St frame Fervo Energy as undervalued around $34 per share, the SWS DCF model points the other way and places future cash flow value closer to $1.18 per share. This implies a stock that screens as expensive rather than cheap.
This kind of gap forces a hard question for investors. Are the long term contracts and growth forecasts strong enough to outweigh what a strict cash flow lens is signaling? Or is the market already paying up for an earnings path that still needs to be delivered in practice?
Look into how the SWS DCF model arrives at its fair value.
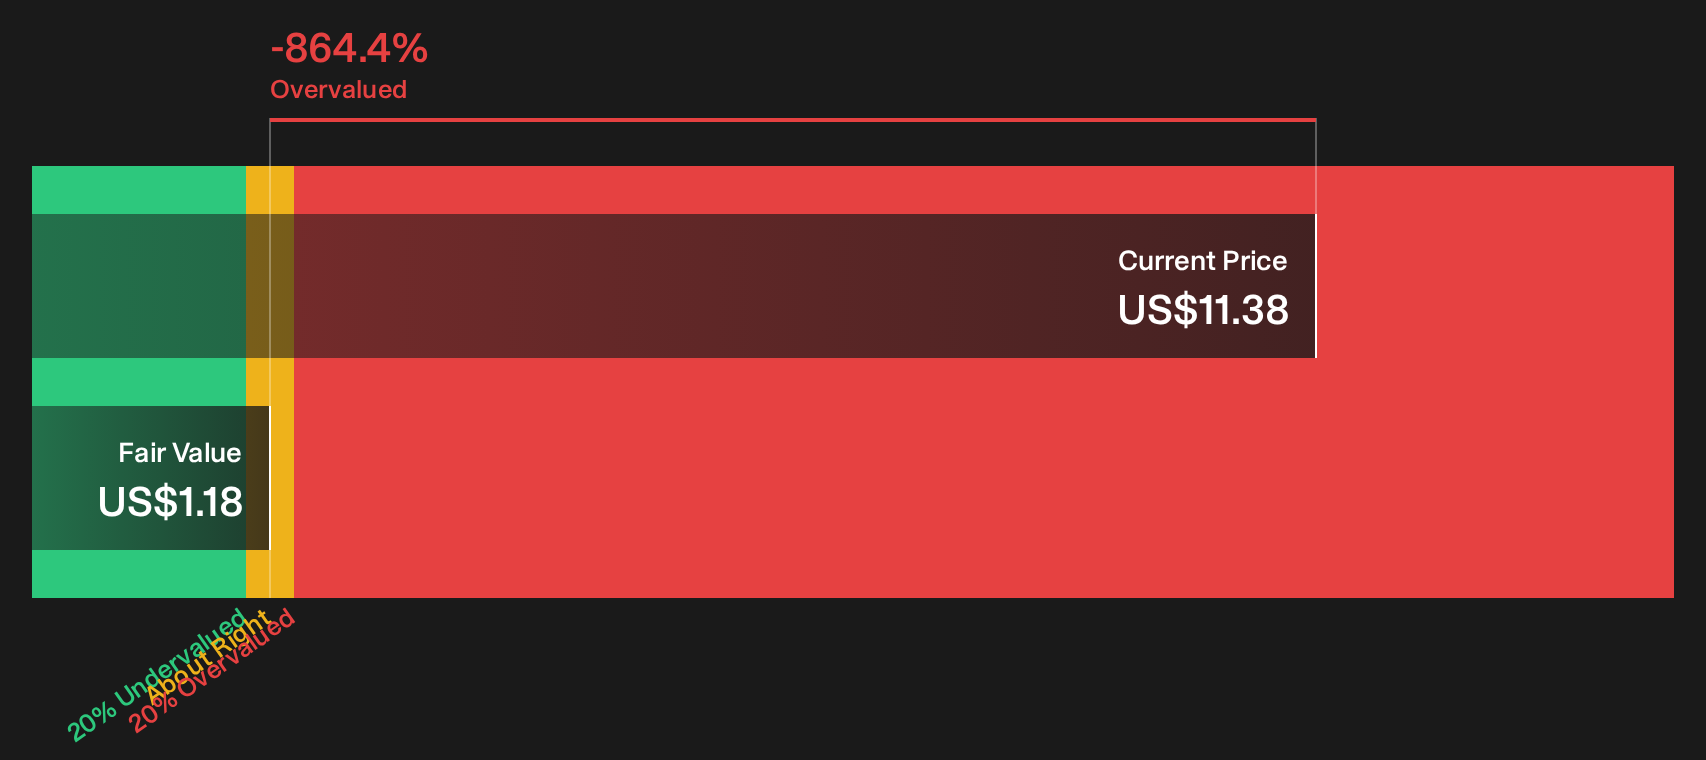
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fervo Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Fervo Energy is clearly split, with both concern and optimism showing up in the data. Move quickly and review the full balance of risks and rewards for yourself through 2 key rewards and 2 important warning signs.
Looking for more Fervo Energy style investment ideas?
If the split views on Fervo Energy have you thinking harder about where to deploy capital next, do not stop with a single stock story.
- Target stronger pricing power by reviewing companies that screen as attractively priced using the 33 high quality undervalued stocks.
- Prioritise resilience by checking businesses that pass the list of solid balance sheet and fundamentals (25 results) with cleaner leverage profiles and sturdier funding positions.
- Hunt for earlier stage potential by scanning the 19 high quality undiscovered gems before wider market attention closes the window.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com