
How Strong Earnings Will Impact UMB Financial Stock
- UMB Financial reported third quarter 2026 net interest income of US$540.01 million and net income of US$278.09 million, along with reduced net charge offs of US$14.00 million compared with the prior year and board approval of both common and preferred dividends payable in early 2027.
- The company is concentrating Shannon A. Johnson fully on the Chief Risk Officer position while folding the Chief Administrative Officer duties into existing leadership, which tightens focus on enterprise risk management as earnings and credit performance both improve.
- The focus now turns to how UMB Financial's stronger earnings and lower net charge offs may influence the existing investment narrative.
Compare UMB Financial's mix of rising earnings, lower net charge offs, and steady dividends with a curated 30 resilient stocks with low risk scores built around financial resilience and disciplined risk management.
UMB Financial Investment Narrative Recap
To own UMB Financial, you need to be comfortable with a bank that leans on commercial lending and institutional services while working to keep credit costs contained. The analyst consensus Narrative on Simply Wall St assumes that operating leverage from the Heartland acquisition, recurring fee income, and disciplined capital levels remain intact. The latest quarter, with higher net interest income and net income, supports that broad case for now.
The more immediate swing factor is how quickly temporary purchase accounting accretion fades relative to organic loan and fee growth. The step down in that income stream is already flagged as a risk, so this report does not materially change the short term catalyst. The biggest operational risk stays the same, that high recent growth in loans and institutional fees could cool or turn choppier.
The most relevant piece of news for that story is the decision for Shannon A. Johnson to focus solely on the Chief Risk Officer role, while the Chief Administrative Officer responsibilities move into existing leadership. For a bank leaning on double digit linked quarter annualized loan expansion and very large institutional assets under administration and custody, concentrated attention on risk systems is directly tied to the thesis.
For you as a shareholder, the question becomes whether a more focused enterprise risk function helps UMB Financial keep net charge offs and nonperforming assets aligned with the cleaner credit profile highlighted in the analyst consensus Narrative on Simply Wall St. If execution stays tight, that supports the catalyst of stable credit costs alongside loan and fee growth. If credit metrics worsen or institutional client activity softens, that would pressure the same story this role change is designed to support operationally.
UMB Financial's outlook projects US$3.5b in revenue and US$1.2b in earnings by 2029. This is based on an assumed 7.7% annual revenue growth rate and an earnings increase of about US$283m from current earnings of US$917.3m.
Uncover how UMB Financial's fair value indicates a 19% potential upside to its current price before enthusiasm for the discount fades.
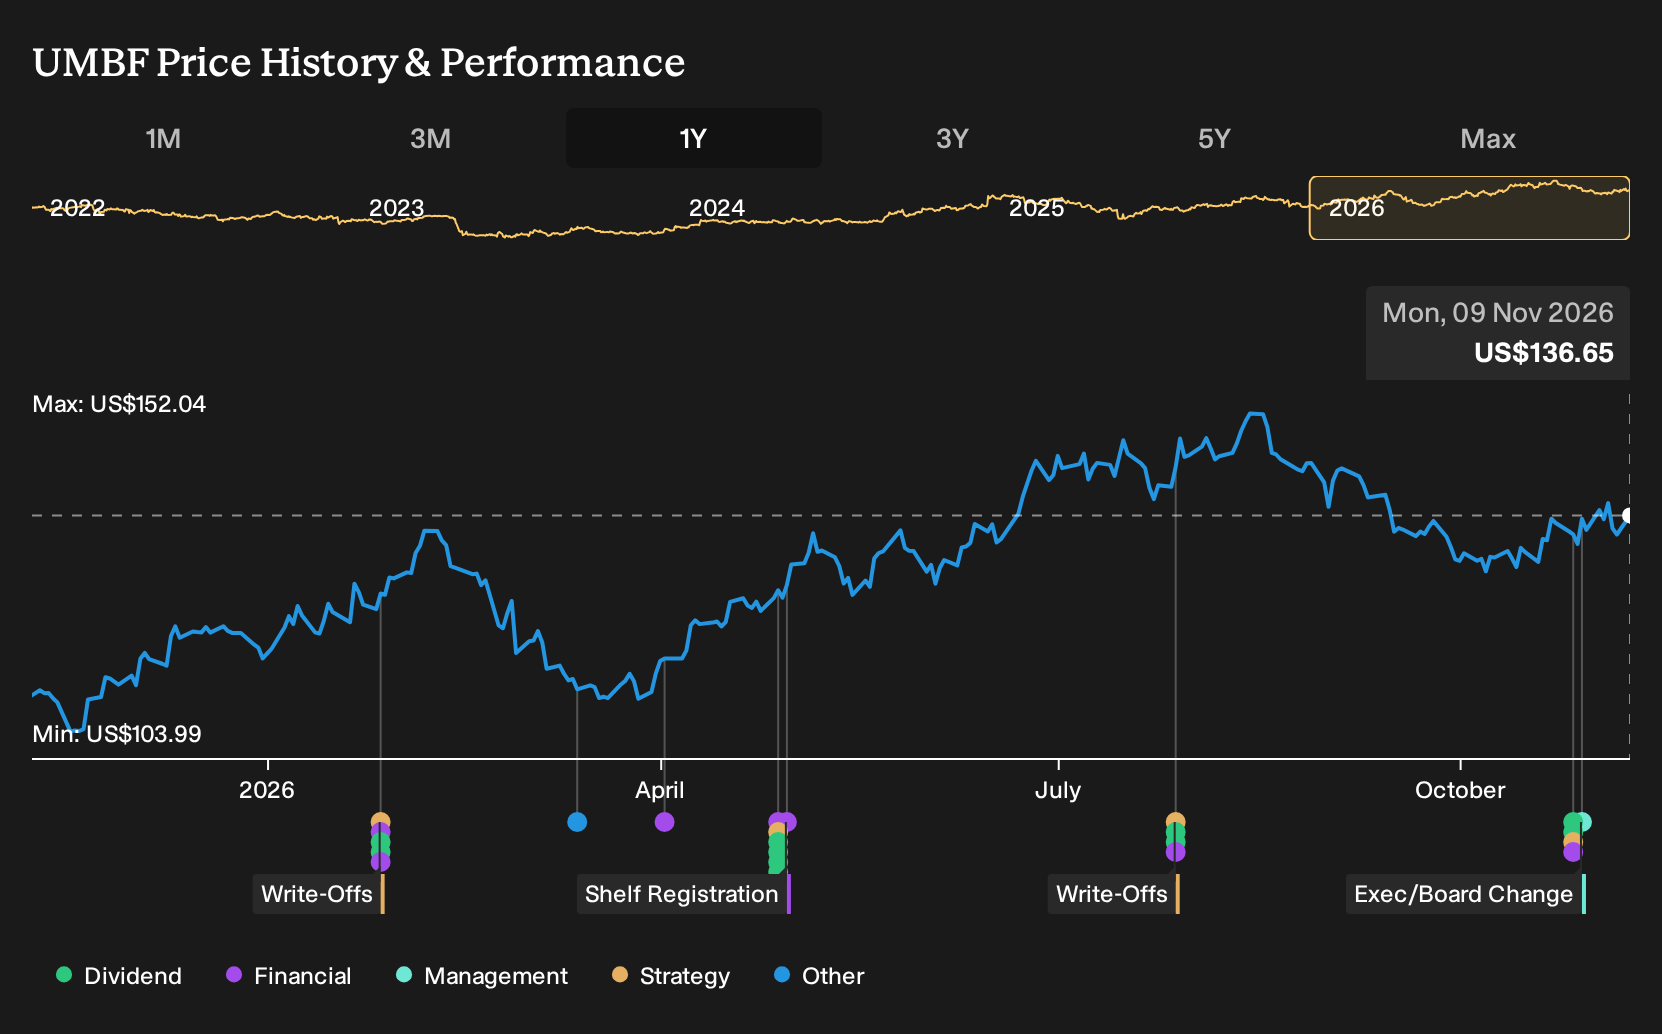
Exploring Other Perspectives
The Simply Wall St Community only includes two fair value views for UMB Financial, yet those estimates already stretch from about US$163 to just over US$242. That spread sits alongside rising reported earnings, lower recent net charge offs, and a sharper risk focus under the dedicated Chief Risk Officer. Use that mix as a prompt to compare several contrasting community viewpoints before setting your own expectations.
Explore another UMB Financial fair value estimate, including one that suggests as much as 77% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your UMB Financial research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UMB Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UMB Financial's overall financial health at a glance.
Looking for more UMB Financial style investment ideas?
If you want to take what you have learned from UMB Financial and apply it across a wider watchlist, the Simply Wall St Screener can help you quickly filter for stocks that fit specific risk, income, or quality preferences.
- For investors who put capital preservation first, scan for companies with sturdier profiles using a 30 resilient stocks with low risk scores.
- If you are hunting for income ideas, sort potential opportunities through a 6 dividend fortresses that focuses on higher yielding payers.
- When quality at a reasonable price matters most, cast a wider net with a 19 high quality undiscovered gems built around businesses with stronger fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com