
Dear Bending Spoons Stock Fans, Mark Your Calendars for November 20
Bending Spoons (BSP) is making its mark on the global software industry with a business model built around acquiring established digital platforms and improving how they operate. Yet, its growing footprint has not translated into equally strong stock performance. In recent months, concerns over its premium valuation, acquisition-heavy growth strategy, and increasing debt have kept the shares under pressure.
Adding another layer to the debate is the growing threat of artificial intelligence (AI). BofA Securities noted that AI disruption remains a recurring concern among bearish clients. In particular, Bending Spoons' established user bases could eventually shift toward AI agents such as Meta Platforms' (META) Muse, potentially reducing direct consumer engagement with individual apps or enabling these agents to replicate the company's existing businesses.
That makes the upcoming earnings announcement particularly important, as the report would offer a better sense of whether Bending Spoons can turn its expanding portfolio into durable growth. The company is scheduled to release its Q3 FY2026 financial results on Friday, Nov. 20, before the market opens.
Still, the broader picture is not without encouraging developments. Bending Spoons recently completed its acquisition of Miro, a collaborative software platform with more than 100 million users. Berkshire Hathaway (BRK.A) (BRK.B) also made an additional $330 million investment, lifting its ownership stake to 4%. However, the endorsement has not entirely quieted concerns about leverage.
With acquisitions expanding its reach and financial commitments attracting closer scrutiny, Bending Spoons’ Q3 results could help determine if the company is building a stronger software business or taking on more financial risk than its growth can comfortably support.
About Bending Spoons Stock
Based in Milan, Italy, Bending Spoons is a technology company that acquires, transforms, and optimizes digital businesses across international markets. Commanding a market cap of nearly $25.5 billion, its portfolio features AOL, Vimeo, Evernote, Eventbrite, WeTransfer, Brightcove, and other platforms operating across productivity, media, streaming, and digital services.
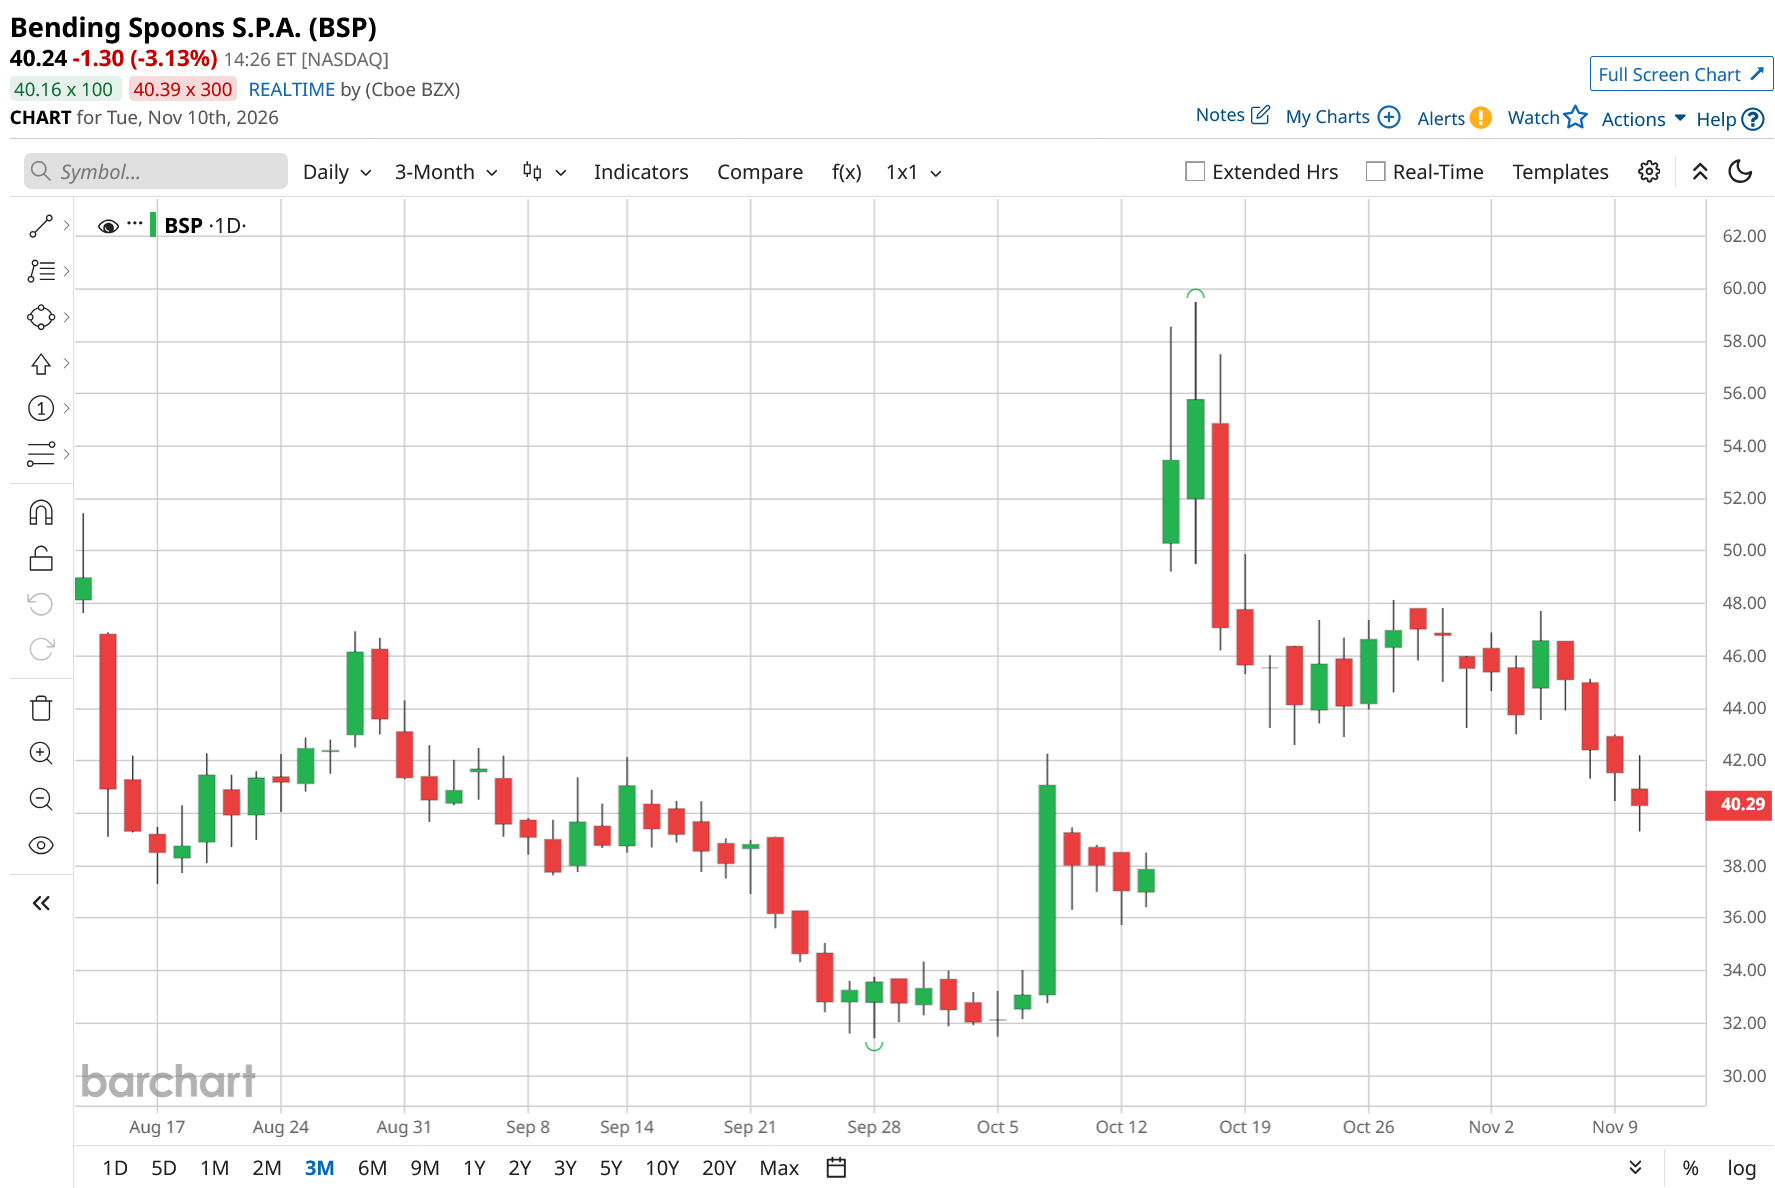
Despite its expanding business portfolio, the stock's recent performance has been uneven. BSP stock has declined 22% over the past three months, although it has managed to recover some ground with a 5% gain over the last month.
Valuation remains another important consideration. BSP stock is currently trading at 29.74 times forward adjusted earnings and 4.96 times sales. Both multiples exceed their respective industry averages, highlighting the premium attached to the company's shares.
A Closer Look at Bending Spoons’ Q2 Earnings
The company's previous earnings announcement offered a striking example of how quickly market expectations can shift. On Aug. 13, Bending Spoons’ shares plunged 16.5% as the company released its Q2 FY2026 results. This came despite revenue soaring 126.3% year-over-year (YoY) to $704.2 million, although organic revenue growth remained considerably more modest at 3%.
The gap between reported and organic growth largely reflected the company's acquisition strategy. Deals completed between Q2 FY2025 and Q2 FY2026, including AOL, Eventbrite, Harvest, MileIQ, Tractive, and Vimeo, contributed most of the expansion. Meanwhile, Bending Spoons continued working on its existing businesses, introducing more than 70 product improvements across these three businesses during the quarter.
Profitability, meanwhile, provided a brighter spot in the results. Gross profit climbed 126.7% to $463.6 million, while adjusted operating income surged 149.9% YoY to $381.2 million. The corresponding margin also expanded by five percentage points to 54%, indicating stronger operating performance alongside the substantial increase in revenue.
The improvement extended to the bottom line, where adjusted net income advanced 175.4% to $293 million. Adjusted EPS also jumped 170.6% to $0.46, giving the company another strong set of profitability figures despite the relatively limited contribution from organic revenue growth.
Looking ahead, management's guidance offers further insight into the growth trajectory. For Q3, Bending Spoons expects revenue of $733 million to $745 million, representing YOY growth of 113% at the midpoint. Adjusted operating income is projected at $380 million to $400 million, implying 111% YoY growth at the midpoint.
The full-year outlook is equally ambitious. For FY2026, management forecasts revenue between $2.78 billion and $2.82 billion, equivalent to 114% YoY growth at the midpoint of the range. Adjusted operating income is expected to reach $1.46 billion to $1.51 billion, representing 142% YoY growth at the midpoint.
Analyst estimates, however, suggest that the earnings trajectory may not be entirely smooth. For Q3 FY2026, EPS is expected to decline 100% YoY to $0.26. The longer-term projections are considerably stronger, with FY2026 EPS expected to increase 126.7% from the previous year to $1.36, followed by another 79.4% rise to $2.44 in FY2027.
What Do Analysts Expect for BSP Stock?
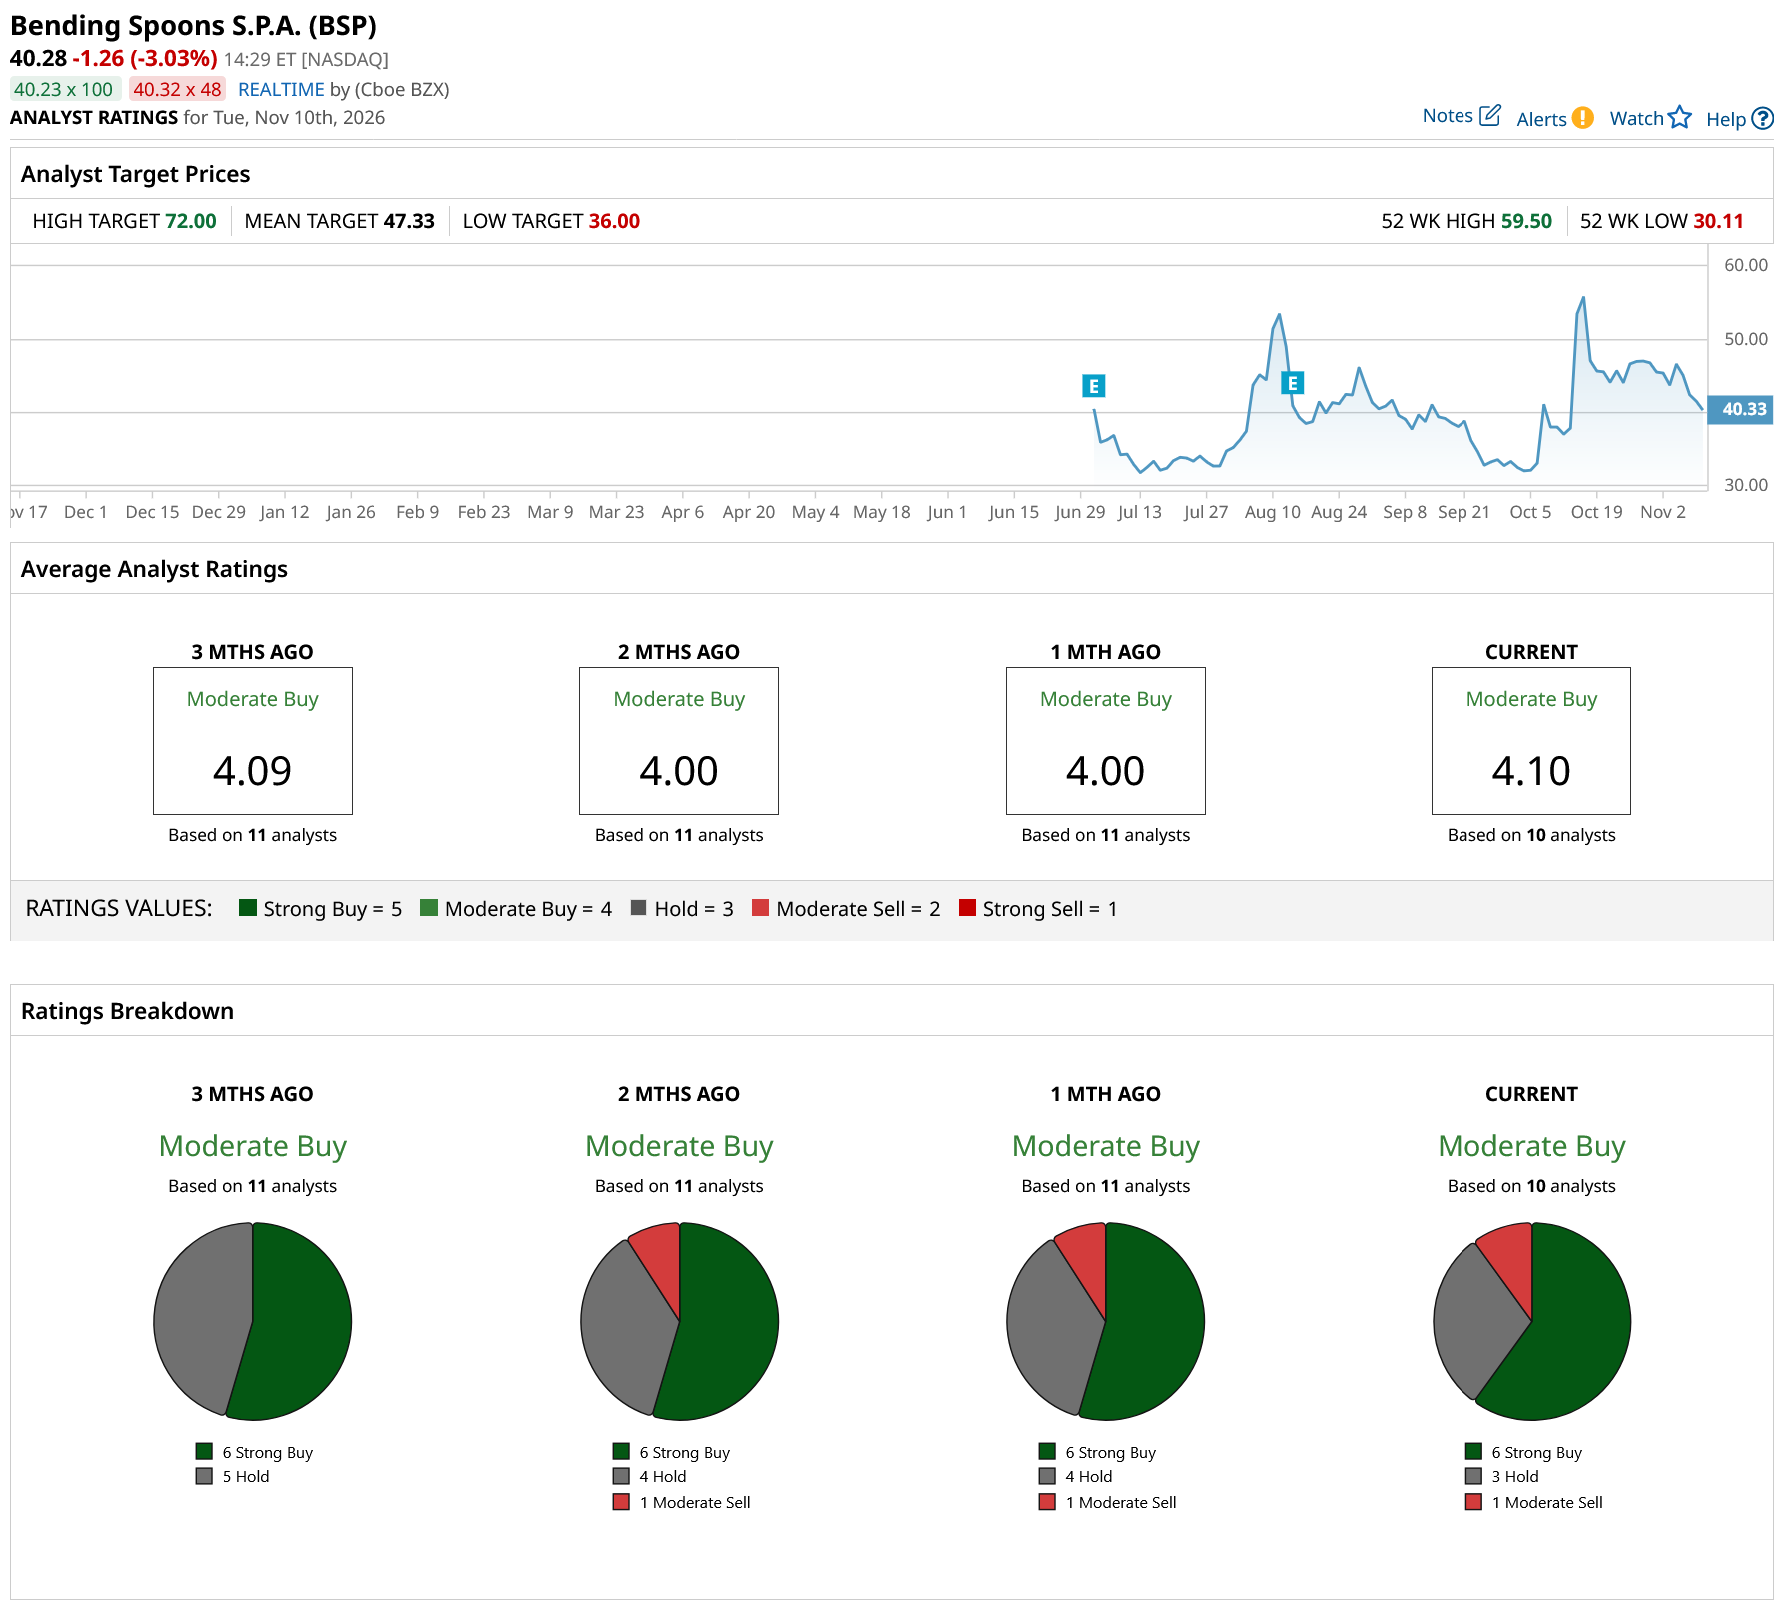
Despite the recent share-price swings, Wall Street's overall stance on BSP stock remains “Moderate Buy.” Among 10 analysts currently covering the name, six have assigned a “Strong Buy” rating, three recommend a “Moderate Buy,” and one has taken a more cautious position with a “Moderate Sell” recommendation.
The price targets suggest that some analysts still see considerable room for appreciation. The average price target of $47.33 implies potential upside of 18%, while the Street-high target of $72 points to a possible gain of 79% from current levels.
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.