
How Investors Are Reacting To Ambea (OM:AMBEA) Strong Quarterly Earnings
- Ambea reported third quarter 2026 revenue of SEK 4,477 million and net income of SEK 380 million, with higher basic earnings per share from continuing operations than a year earlier.
- Management highlighted ongoing investment in quality systems, leadership and the work environment, while actively evaluating bolt-on acquisitions to complement organic expansion from new and pipeline care facilities.
- We will examine how Ambea's investment narrative is shaped by stronger earnings and its continued focus on disciplined bolt-on acquisitions.
Scan how Ambea's acquisition push compares with other potential compounders by checking our hand-picked list of 568 high quality undiscovered gems in similar quality focused sectors.
Ambea Investment Narrative Recap
To own Ambea, you need to believe that demand for Nordic care services will support both organic growth from new facilities and disciplined bolt on deals, without stretching the balance sheet too far. The latest quarter showed higher revenue and earnings, so the near term swing factor is whether that operational momentum can be kept steady as the MiraQ quality system rollout finishes.
The biggest immediate risk still sits in execution. Integrating acquisitions, managing high debt and recruiting enough care staff all need to work in sync. The new numbers do not remove those issues, but they do give management a bit more room to execute their plan.
The analyst consensus narrative on Simply Wall St leans heavily on earnings growth forecasts and acquisition benefits. Against that backdrop, the third quarter 2026 report, with SEK 4,477 million in revenue and SEK 380 million in net income, is the most relevant data point. It shows the business producing higher basic earnings per share from continuing operations compared with a year earlier.
For you as a shareholder, that update matters because it frames both catalysts and risks. Stronger recent earnings and the comment that organic expansion remains an important growth driver give context to future bolt on acquisitions. At the same time, ongoing integration costs and debt highlighted in the broader risk discussion stay front and center for any thesis on Ambea.
Analysts framing the Ambea story are effectively underwriting SEK 25.1 billion in revenue and SEK 1.3 billion in earnings by 2029. This implies 13.9% yearly revenue growth and an earnings increase of roughly SEK 513 million from current earnings of SEK 787.0 million.
Uncover how Ambea's fair value indicates a 4% potential upside to its current price before the market closes the gap.
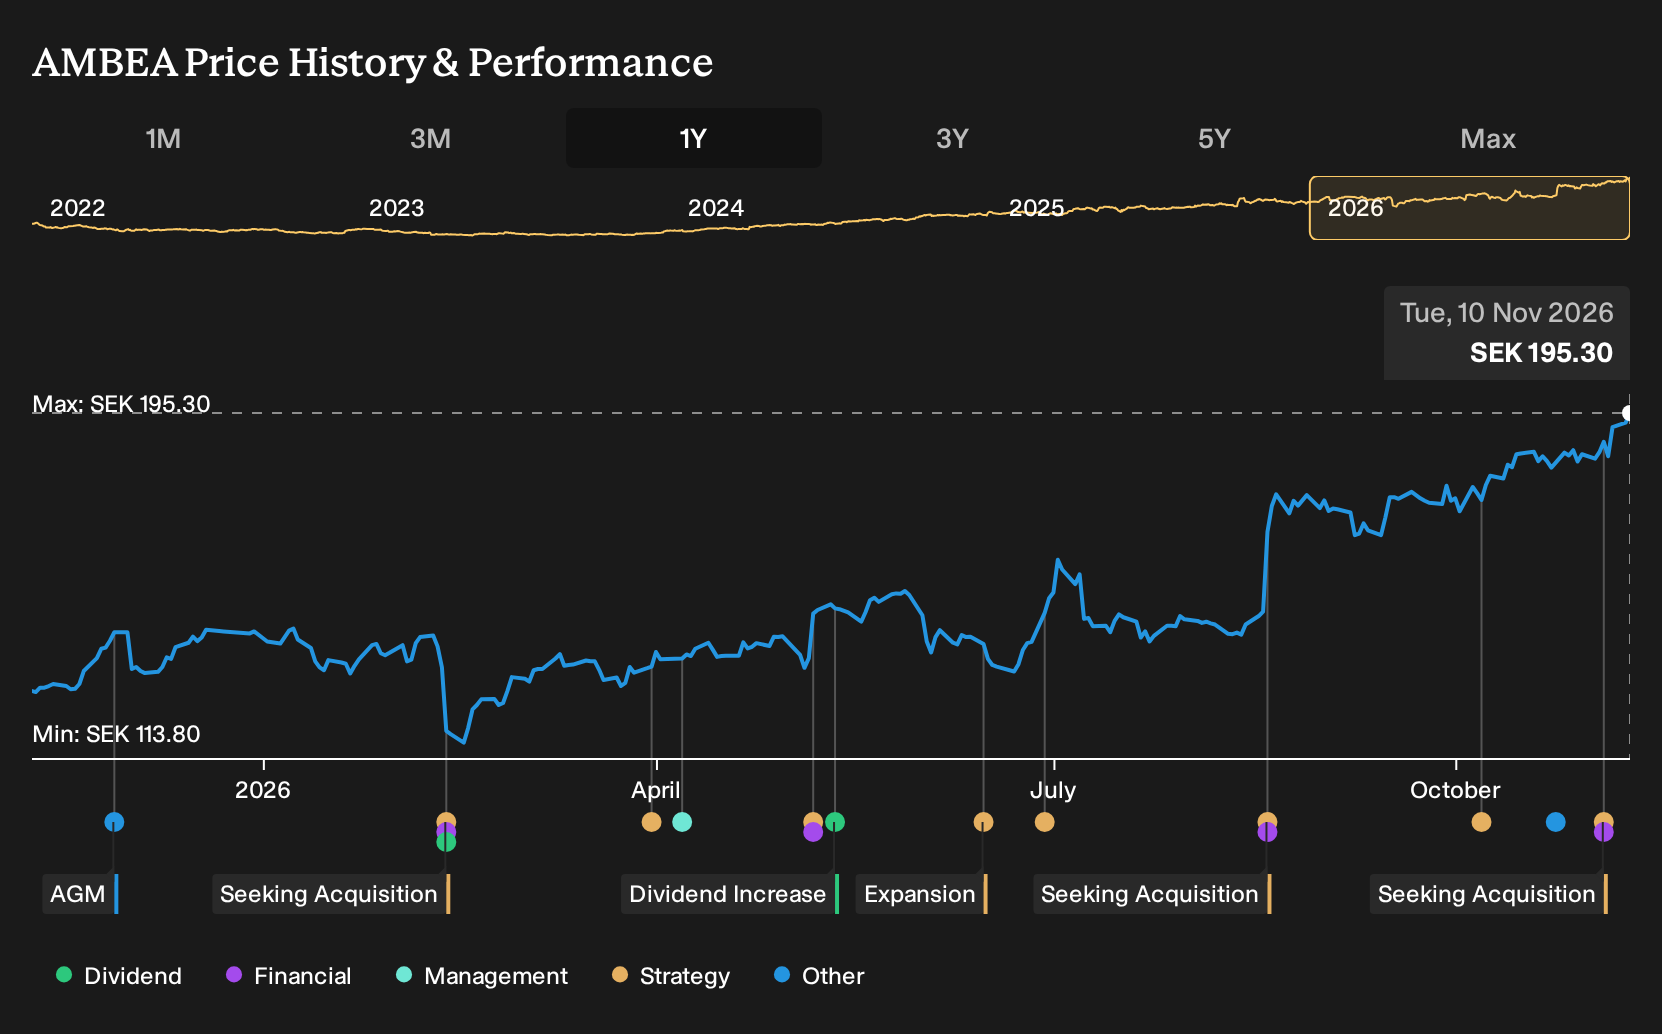
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band from SEK 204 to SEK 1,420.63, which already shows how far opinions on Ambea can stretch. When you set that against the acquisition drive and higher reported earnings, you get a mix of optimism and concern that invites you to explore more viewpoints.
Explore another Ambea fair value estimate, including one that suggests as much as 627% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ambea research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ambea. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ambea's overall financial health at a glance.
Looking For More Ideas Beyond Ambea?
If Ambea has sharpened your thinking about quality, earnings power and balance sheet risk, it can help to line it up against a broader watchlist built from other stocks that fit clear, evidence based criteria.
The Simply Wall St Screener is a practical way to do that. You can filter for cash generation, leverage, dividends and more, then compare how those traits stack up next to what you see in Ambea.
- If you want businesses that already combine financial strength with meaningful income, start with a shortlist of 217 dividend fortresses that aim to balance yield with resilience.
- For investors who care most about balance sheet resilience and fundamentals, build a watchlist from a list of solid balance sheet and fundamentals (195 results) that can handle tougher conditions without needing constant refinancing.
- When you are hunting for fresh ideas outside the usual large caps, scan a focused 568 high quality undiscovered gems where quality metrics and fundamentals do the initial filtering for you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com