
What ANZ Group Holdings (ASX:ANZ)'s Mixed Full Year Results Means For Shareholders
- ANZ Group Holdings reported full year 2026 results with net income of A$7,270 million on net interest income of A$17,894 million and proposed a partially franked 83 cent final ordinary dividend with New Zealand imputation credits for eligible shareholders.
- The bank delivered higher basic earnings per share from continuing operations compared with the prior year, while facing thinner underlying profitability, higher impairment charges and a softer capital ratio. These factors raise questions about how durable the cost cutting led profit uplift may be.
- With ANZ previously framed as reasonably valued on its existing earnings and dividends, attention now turns to how thinner underlying profitability affects that investment narrative.
Compare ANZ Group Holdings' mix of dividends, profitability and capital strength with a curated group of banks and lenders screened for list of solid balance sheet and fundamentals (12 results)
ANZ Group Holdings Investment Narrative Recap
To own ANZ Group Holdings, you have to be comfortable with a bank where cost control and technology execution are doing a lot of the heavy lifting. According to Jamesiskindacool, an investor in the Simply Wall St Community, the case already leaned heavily on current earnings, capital and dividends rather than blue sky from Suncorp Bank integration or margin expansion. The latest result, with thinner underlying profitability and higher impairments, keeps the near term focus squarely on cost savings holding up.
The biggest near term swing factor is whether management can keep extracting efficiency gains while credit quality holds steady. A softer capital ratio and a relatively low allowance for bad loans put more attention on how ANZ Group Holdings handles any turn in impairments. If funding costs stay sticky, that capital and provisioning mix looks like the key operational risk rather than the new dividend itself.
The 83 cent final ordinary dividend, partially franked at 80% and carrying New Zealand imputation credits, matters because it leans into what many shareholders already care about most. Jamesiskindacool argues the appeal has been grounded in existing earnings and cash returns rather than aggressive growth assumptions. Keeping the payout at that level, alongside higher basic earnings per share, supports that income centred thesis.
It also ties back to catalysts and pressure points. Maintaining this dividend while operating income undershoots market expectations keeps execution risk front and centre. Investors are effectively watching whether ANZ Group Holdings can keep funding a sizeable cash distribution while integrating Suncorp Bank, absorbing higher impairments and managing a softer CET1 ratio. If that balance holds, the payout becomes a key proof point on the CEO’s turnaround plan.
That A$32.18 fair value reflects Jamesiskindacool’s narrative that ANZ Group Holdings can grow revenue at 6.5% a year while eventually running the business on a 27.4% profit margin, and then valuing those future earnings in line with its current earnings, capital and dividend profile.
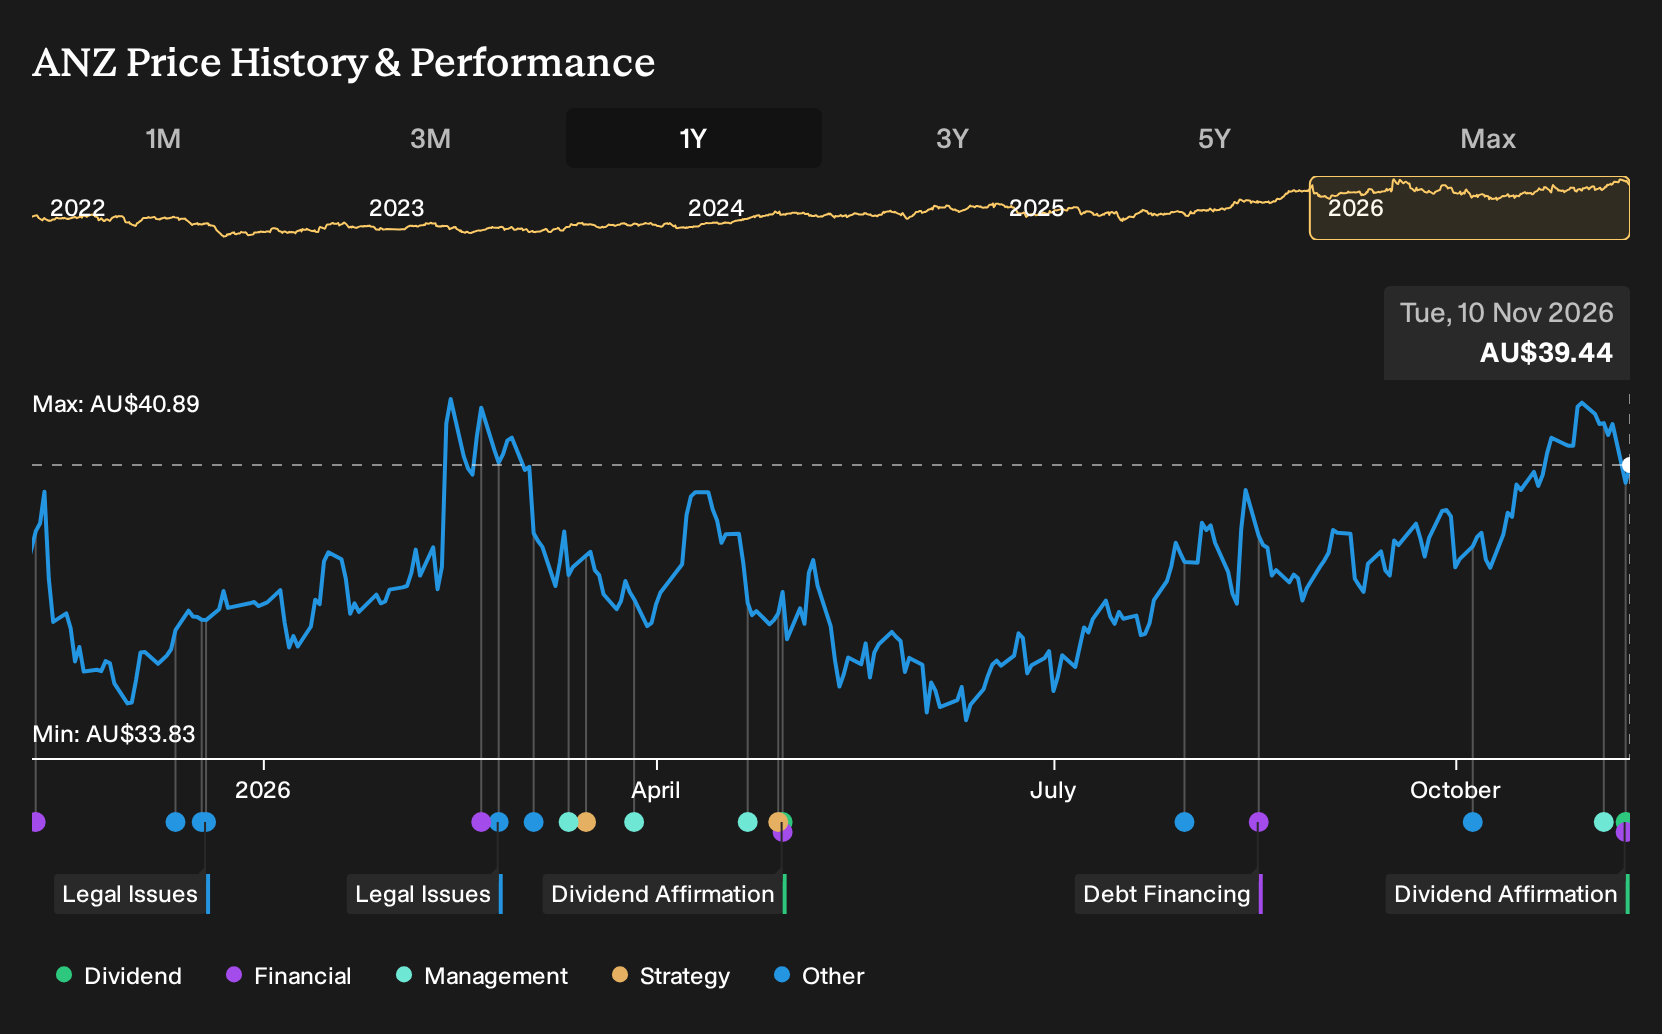
Uncover why ANZ Group Holdings' fair value indicates an 18% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between A$32.18 and about A$42, so you are seeing a wide A$10 spread on ANZ Group Holdings before this earnings and dividend announcement. That split reflects differing views on how cost cuts, Suncorp Bank integration and higher borrowing costs could shape future performance. Opinions differ sharply, so explore the full set of community views before deciding how this bank fits your portfolio.
Explore 3 other ANZ Group Holdings fair value estimates, including one that suggests as much as 18% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your ANZ Group Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ANZ Group Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ANZ Group Holdings' overall financial health at a glance.
Looking For More Ideas Beyond ANZ Group Holdings?
If ANZ Group Holdings is only one part of the income and stability mix you want, you can broaden your watchlist with other companies that match clear financial filters using the Simply Wall St Screener.
- For investors who want resilient balance sheets and robust fundamentals, start with this curated list of solid balance sheet and fundamentals (12 results).
- If value is your priority and you are hunting for quality at a reasonable price, check out a hand picked set of 2 high quality undervalued stocks that may fit that brief.
- Income focused portfolios can use a shortlist of higher yield opportunities by reviewing these potential 5 dividend fortresses built for cash flow driven investing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com