
Innodata (INOD) Stock May Be Overvalued After A 360% Run
Innodata has swung from a very strong multi‑year run to a sharp pullback, and the question now is whether the current share price still lines up with what its earnings can support. Recent headlines around job cuts and client demand only sharpen that focus for anyone trying to decide how much the stock should reasonably be worth.
- Over the past 5 years, Innodata has returned about 359.7%, which puts a lot of pressure on its earnings to justify how far the stock has already come.
- The recent workforce reductions tied to weaker client demand and the related investigation can affect how investors think about the durability of Innodata's revenue and the earnings power that underpins its valuation.
- The analysts covering Innodata have run their own numbers. See what analysts think Innodata's shares could be worth.
The stock's next move may depend on whether Innodata's current earnings profile makes today's valuation look well supported or stretched.
If this news has you rethinking concentration risk around Innodata and similar stories, a focused stock screen built around 42 profitable AI stocks that aren't just burning cash can be a useful next step in your research.
Has Innodata Run Too Far on Earnings?
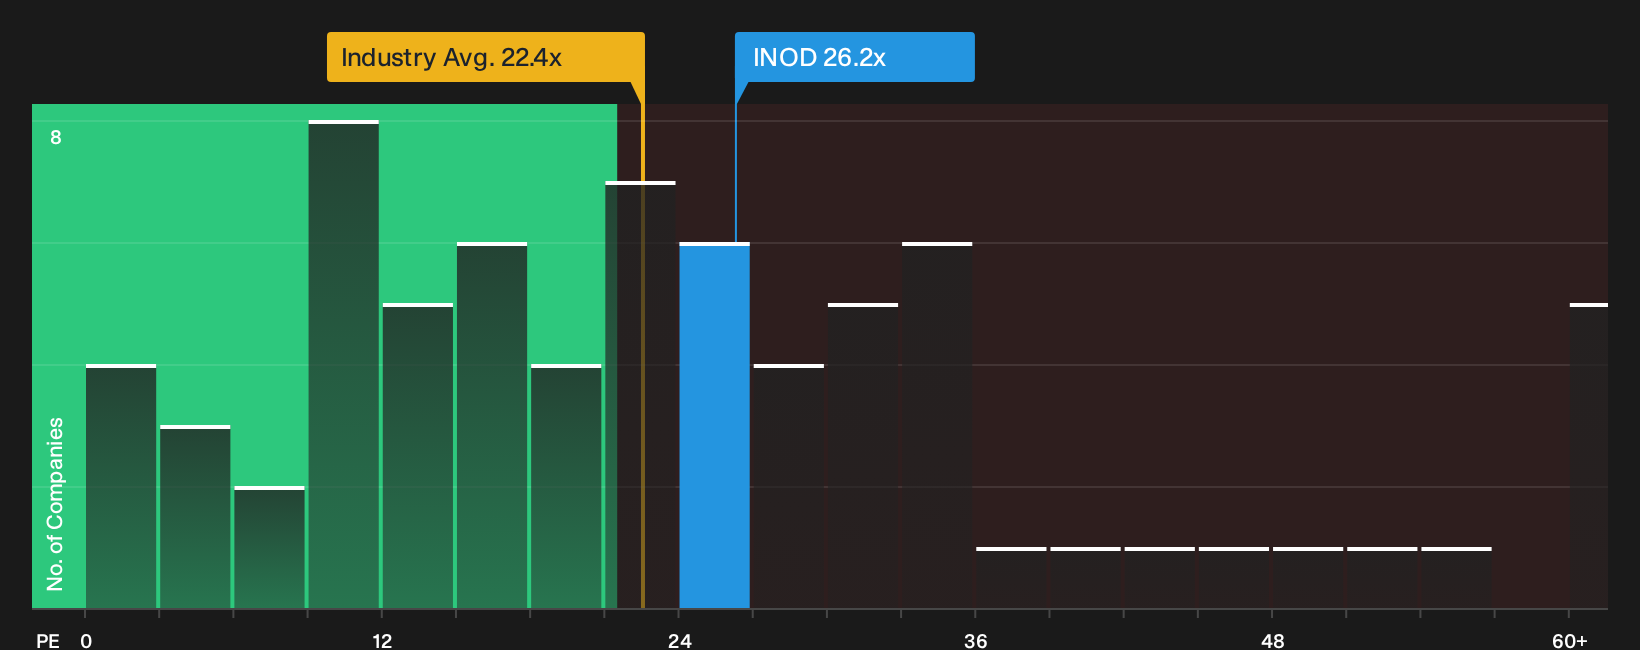
The P/E ratio works well for Innodata because earnings are central to how investors seem to be framing the story right now. In this context, the stock trades at about 26.2x earnings, which is slightly below the peer average of 27.7x but above the Professional Services industry at roughly 22.4x. Despite the recent investigation tied to abrupt job cuts and potential client churn, the current valuation still prices Innodata at a premium to the broader sector.
The fair P/E that results from the tailored model, which factors in Innodata's growth profile, profitability, size and risk, sits below where the shares currently change hands. That gap suggests the stock appears overvalued on this specific earnings multiple, so any thesis here needs to focus heavily on the durability of current profits and how the business replaces or deepens major customer relationships. Explore the numbers behind Innodata's P/E valuation.
The Innodata Narrative: What Would Justify Today's Price?
Innodata investors now face a different question. The valuation puzzle is clear enough, so the focus turns to what sort of growth, margins and earnings path would need to occur for the stock to trade meaningfully higher or lower than today. Narratives on Simply Wall St's Community page set out those possible futures and, rather than relying on a single multiple or model output, spell out the assumptions behind each fair value so you can later compare them with actual results.
One of the top narratives on Innodata: 74% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"The main thing that has to go right is that Innodata continues to scale and monetize its IP-based datasets and platforms, such as AI Cyber Training Suite and agent evaluation tools..."
Discover why this Narrative puts Innodata at 74% undervalued.
Innodata's valuation story is only half the picture
Before treating the current pricing as the whole story, it is worth knowing that Simply Wall St's checks have flagged specific concerns that sit alongside the numbers and deserve a closer look. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com