
3 Great Canadian Dividend Stocks To Own In November 2026
Rising inflation in the US and expectations of further interest rate hikes are keeping pressure on global borrowing costs, which matters for Canadian dividend stocks that many investors treat as a source of regular cash flow. When rates feel less predictable, a well covered yield above 3% can look especially appealing. This article highlights three dividend paying Canadian companies from our income screen that aim to offer consistency rather than excitement.
The three stocks highlighted here offer a compelling starting point if you want exposure to dividend powerhouses with well covered, growing and stable income streams. However, if you want the pick of this theme, these 3 dividend aristocrats stocks are the best of the best.
Sun Life Financial (TSX:SLF)
Overview: Sun Life Financial is a global insurer and asset manager that provides life and health coverage, retirement savings, and investment products supported by recurring fees.
Operations: Sun Life Financial generates most of its revenue in the U.S. at CA$14.0b, Canada at CA$12.1b, and SLAM at CA$7.1b, with Asia contributing CA$2.7b.
Market Cap: CA$56.1b
Sun Life Financial matters for a 3%+ yield screen because recurring fee and insurance income give its dividend a clear business backbone. The analyst consensus Narrative on Simply Wall St highlights how management is trying to tilt that engine toward more capital light, cash focused earnings.
"Expansion and integration of SLC Management into a roughly $400 billion global alternatives platform, together with management equity ownership and plans to generate client cross sell and expense synergies, is aimed at increasing fee based revenue and shifting the earnings mix toward more capital light asset management income."
What happens to that carefully built dividend profile if one quiet source of fee pressure starts to bite harder than management expects?
If that pressure is building under the surface, reading the full narrative for Sun Life Financial shows how Sun Life Financial’s income engine could accelerate or stall as conditions shift.

Canadian Tire Corporation (TSX:CTC.A)
Overview: Canadian Tire Corporation runs a nationwide retail network, owns income producing real estate and operates a Financial Services arm that issues credit cards and in store financing to generate recurring fee and interest income that help support its dividend.
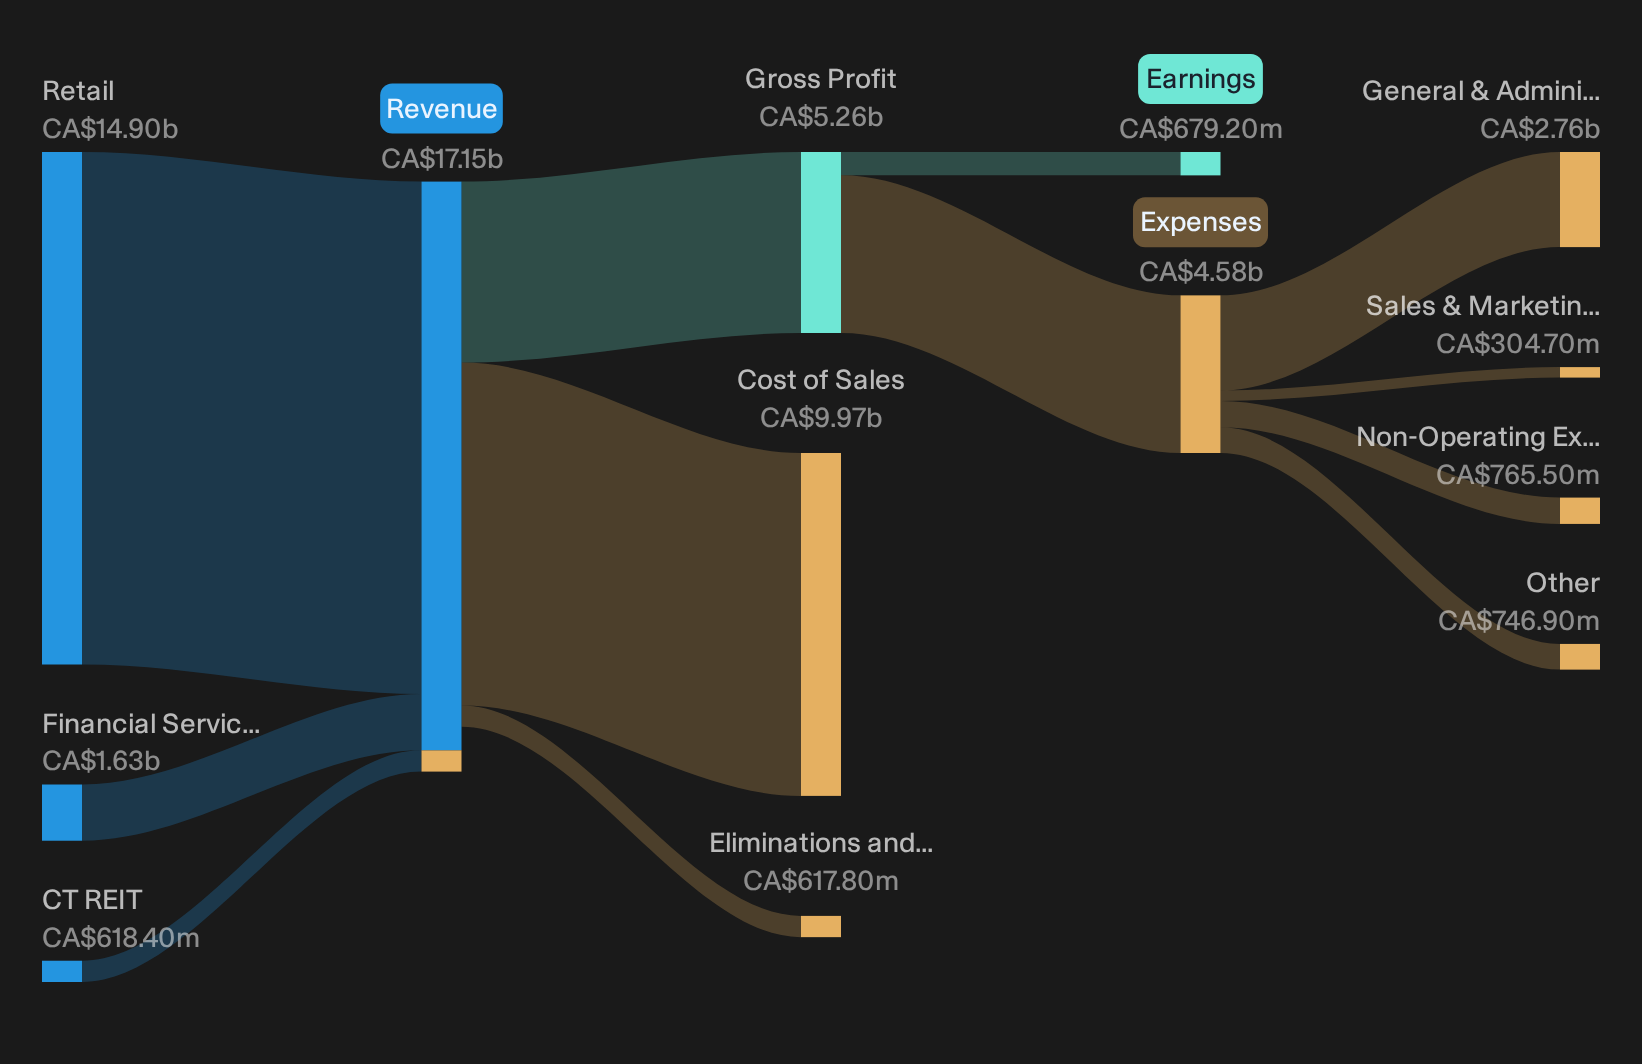
Operations: Canadian Tire Corporation earns about CA$14.9b from Retail, CA$1.6b from Financial Services and CA$618 million from CT REIT, offset by group adjustments.
Market Cap: CA$10.7b
Canadian Tire Corporation matters for a Dividend Powerhouses screen because its Financial Services engine turns everyday spending into repeat fee and interest income that helps support a yield above 3%. The analyst consensus Narrative on Simply Wall St sets out how that engine is being tuned.
"The wider rollout of AI pricing and customer analytics tools, such as the platforms used to shape promotions and category occasions, is expected to influence assortment, promo intensity and regular pricing in ways that support gross margin and earnings quality."
What happens to dividend confidence if one assumption about credit costs and retail mix quietly shifts while that AI driven playbook scales?
If that mix is quietly shifting already, the full narrative for Canadian Tire Corporation shows where Canadian Tire Corporation’s earnings engine could be accelerating, masking risk or decoupling from headline retail trends.
Bank of Nova Scotia (TSX:BNS)
Overview: Bank of Nova Scotia is a diversified bank that pays a 3%+ dividend supported by Canadian and international retail and commercial banking.
Operations: Bank of Nova Scotia generates about CA$11.9b from Canadian Banking and CA$9.6b from International Banking, with additional billions from wealth and markets activities.
Market Cap: CA$157.6b
Bank of Nova Scotia matters for the Dividend Powerhouses theme because its 3%+ yield is anchored by earnings from broad Canadian and Latin American banking operations. In addition, the analyst consensus Narrative on Simply Wall St frames how that income stream could evolve as international and wealth activities keep scaling.
"Expansion of banking and wealth management services in Pacific Alliance markets such as Mexico, Peru, Chile and Colombia remains a live driver, with International Banking revenue and loan growth in these regions and ROE above 16% pointing to further potential for fee income and earnings growth as Bank of Nova Scotia continues to deepen client relationships."
What that means for dividend comfort ultimately hinges on how one less visible shift in credit quality and capital needs plays out.
When that credit and capital story matters most, the full narrative for Bank of Nova Scotia shows where Bank of Nova Scotia’s income engine could be accelerating or quietly masking emerging risks.

Curious To Explore Dividend Alternatives
Fresh ideas rarely stay under the radar for long. As momentum builds and potential breakouts start flying, information decays fast, so review these picks before the crowd and act now.
- Spot potential value plays early and review the 6 high quality undervalued stocks while prices and expectations have not fully caught up.
- Hunt for future-critical materials exposure and scan the 33 best rare earth metal stocks before this corner of the market gets fully crowded.
- Target steady balance sheets with room to move and work through the list of solid balance sheet and fundamentals (5 results) while these candidates still look under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com