
What Herc Buyers Were Betting On
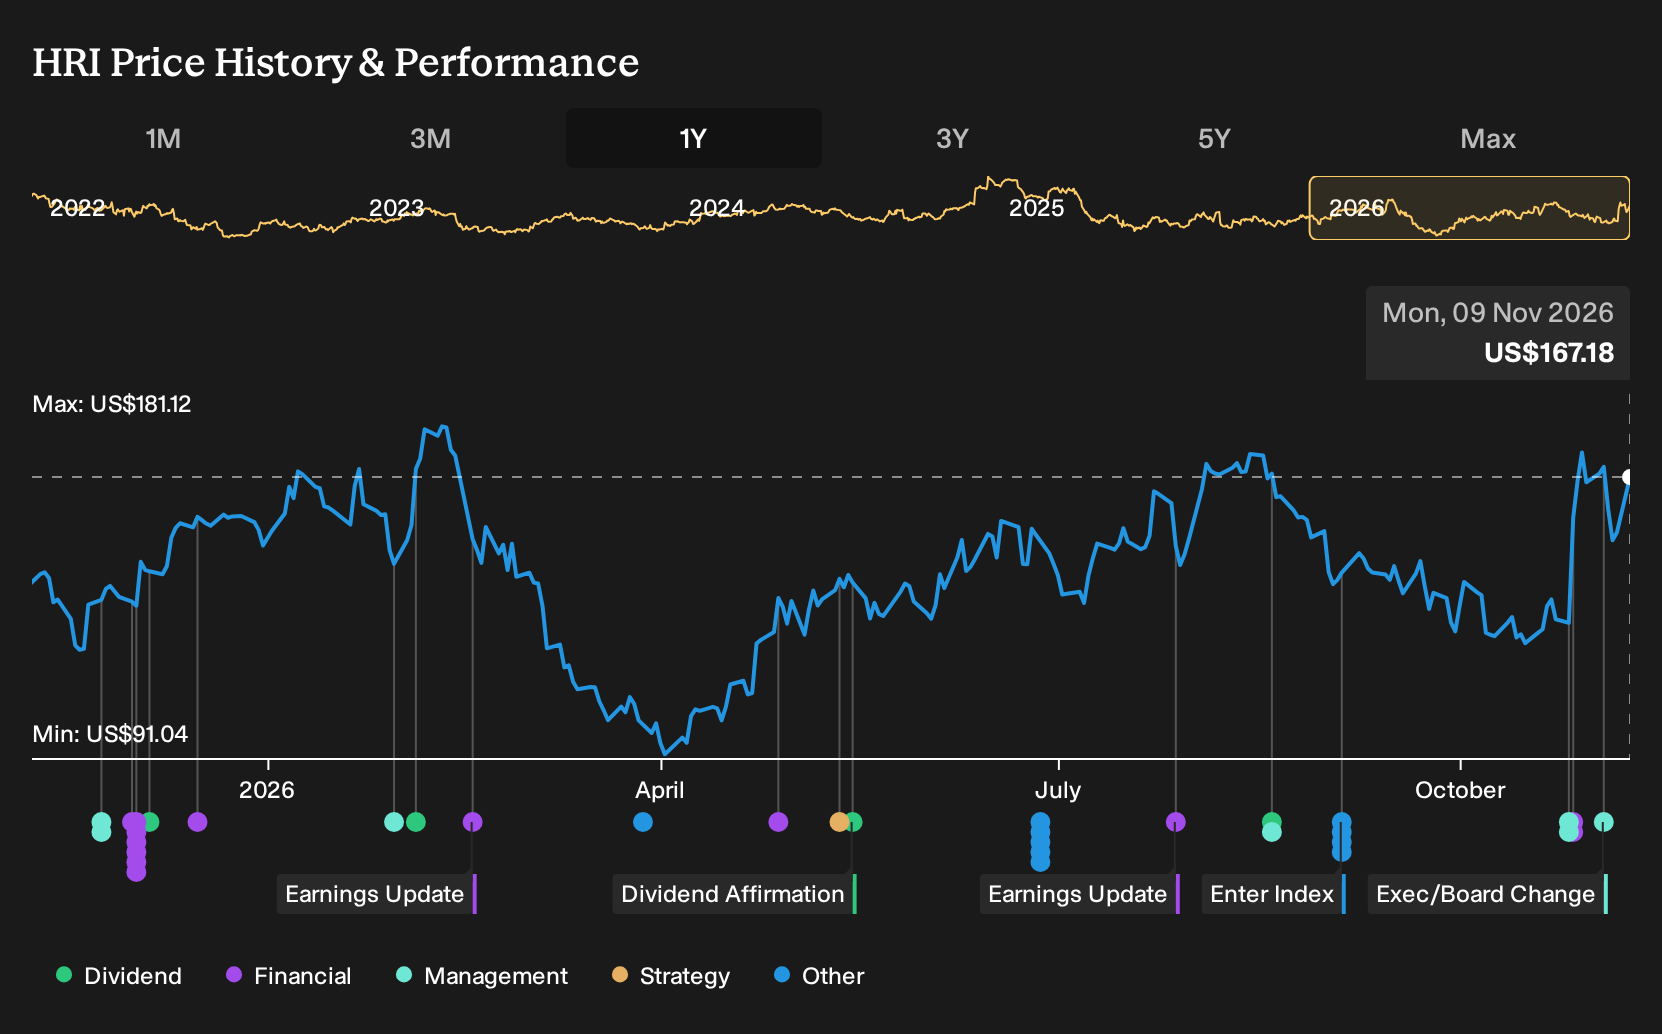
Herc Holdings kept investors busy in 2026, from record Q3 equipment rental revenue to a raised full year outlook and a fresh CEO succession plan. Holding Herc over the past year would have returned 21.3%, including dividends. If you had bought on 9 November 2025, you would now be weighing those gains against what was actually on the table then and asking whether the H&E integration and mega project pipeline ever truly justified that bet.
The easy part of this move is behind Herc. Zero in on 33 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing On Herc
The shares cost US$137 at the start of the period, and Herc Holdings sat between two very different stories about what came next.
The optimistic case saw industry rental demand holding up and H&E integration paying off. This pointed to a Fair Value of US$156, a price that reflected those upbeat assumptions about 15.4% revenue growth and a 10.7% profit margin in a few years.
The cautious view focused on transition costs and leverage, with a Fair Value of US$100 based on concerns that high debt and environmental rules could squeeze rental economics and compress margins.
What The Results Changed For Herc Holdings
The headline development for Herc Holdings was record Q3 2026 equipment rental revenue and raised full year guidance, which supported the view that mega projects and the H&E integration could support higher earnings. Reported figures showed revenue at US$1,364m and net income at US$104m, with net margin rising to 7.6%, yet earlier pro forma data showed integration still weighing on profitability.
The episode centered on whether merger benefits would outweigh transition friction. When you assess another acquirer led story, track revenue, net income and margin together against the original synergy targets rather than assuming scale alone will do the work.
What Herc Holdings’ Share Price Already Assumes
Herc Holdings now trades at US$167, after a 21.3% gain over the past year. The bearish analyst Narrative on Simply Wall St sets its Fair Value below that level and focuses on pressure from fuel, freight and a balance sheet sitting near 4x net leverage.
That Narrative argues today’s price depends on Herc turning specialty rental, mega projects and digital usage into stronger margins and lower leverage. The question for a buyer is how persistent cost inflation or slower deleveraging could challenge that assumption.
"Key Takeaways: Bearish analysts expect Herc Holdings to face ongoing pressure on margins and returns if fuel and transportation costs stay elevated and the company continues to carry close to 4x net leverage despite acquisition synergies. The main thing that has to go right is that Herc Holdings converts its growing mix of specialty rental, mega project exposure and digital platform adoption into higher quality revenue that supports its plan to reduce net leverage toward the top of its 2 to 3x target range by year end 2027."
The price and this Narrative do not agree. → Uncover what this Narrative says Herc is actually worth
Go Straight To The Source
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 38% below our estimate - channels AI driven freight and customs workloads through an automated forwarding and brokerage network.
- Company 2 - 26% below our estimate - expands a large gold reserve base while contending with higher operating costs and geopolitical risk.
- Company 3 - 49% below our estimate - scales an asset light hotel network alongside a fast growing, attached retail business.
Three companies from the same screener. Open all 25 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com