
Serica Energy (LSE:SER) Signs Beacon Pacific Rig Contract, Is It 33% Below Fair Value?
Why Serica Energy’s New Drilling Contract Matters Now
Serica Energy (LSE:SER) has kicked off a fresh chapter with a contract for the Beacon Pacific rig, setting up a multi well UK Continental Shelf drilling campaign focused on near field targets.
Recent trading has been choppy for Serica Energy, with the share price down 2.1% over one day, 10.5% over seven days, and 15.7% over the past month. However, the year-to-date share price return is 25.3% and the five year total shareholder return is 87.5%, which points to longer term holders still sitting on sizeable gains while shorter term momentum has cooled as the Beacon Pacific contract lands in the market narrative.
Scan beyond Serica Energy and review other potential production-driven oil and gas plays in our hand picked 33 best rare earth metal stocks
Serica Energy now trades at a steep discount to both analyst targets and some intrinsic value estimates after the recent pullback. Is that discount cushioning risk, or signalling that the market’s caution is justified?
Most Popular Narrative: 33% Undervalued
Serica Energy last closed at £2.24, while the analyst consensus Narrative on Simply Wall St estimates fair value at about £3.35 using a 7.56% discount rate. That gap frames the Beacon Pacific contract in the context of a view that future cash flows could justify a higher price.
The planned 2027 multi well drilling campaign, including initial infill wells at Bruce and potential follow on activity at Kyla and Glendronach, is designed to add incremental production of up to tens of thousands of barrels per day, which could increase future revenue and improve unit operating margins as fixed costs are spread over higher volumes.
See why 46 investors see Serica Energy as 33% undervalued.
Result: Fair Value of £3.35 (UNDERVALUED)
Still, Serica Energy’s story leans heavily on aging North Sea hubs like Triton and Bruce, and any further outages or tougher UK taxes could quickly challenge that upbeat narrative.
Find out about the key risks to this Serica Energy narrative.
Another View: Serica Energy Through The Sales Lens
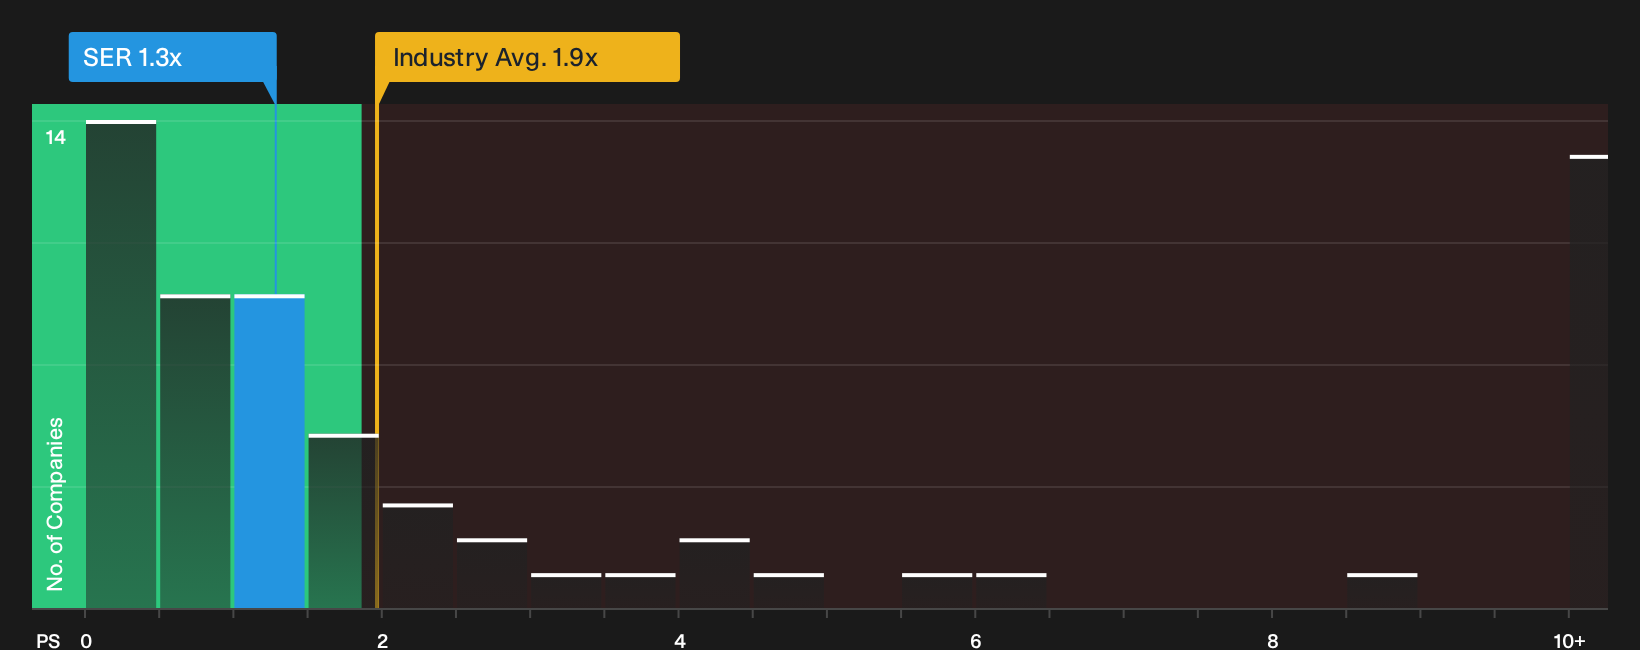
There is a catch. While Serica Energy screens as undervalued on future cash flows, its current P/S of 1.3x is almost double the fair ratio estimate of 0.7x. This is despite sitting below the UK Oil and Gas average of 1.9x and the peer average of 1.7x. Is the discount to peers enough to offset the premium to that fair ratio, or does it point to valuation risk if sentiment cools?
To unpack how that sales based gap might close over time and what it could mean for the share price path, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or a clear message? Serica Energy is generating both concern and optimism, so consider reviewing the numbers for yourself with 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Serica Energy?
If you stop with Serica Energy, you only see one corner of the market. Broaden your watchlist and you improve your chances of spotting what others miss.
- Spot potential value plays early by scanning our 16 high quality undervalued stocks before others price in their strengths.
- Prioritise resilience in tougher markets by using the 4 resilient stocks with low risk scores to focus on companies with lower overall risk profiles.
- Hunt for less crowded opportunities by checking the 5 high quality undiscovered gems and see which solid operators are still flying under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com