
How Investors Are Reacting To NFI Group (TSX:NFI) Raised 2026 EBITDA Guidance
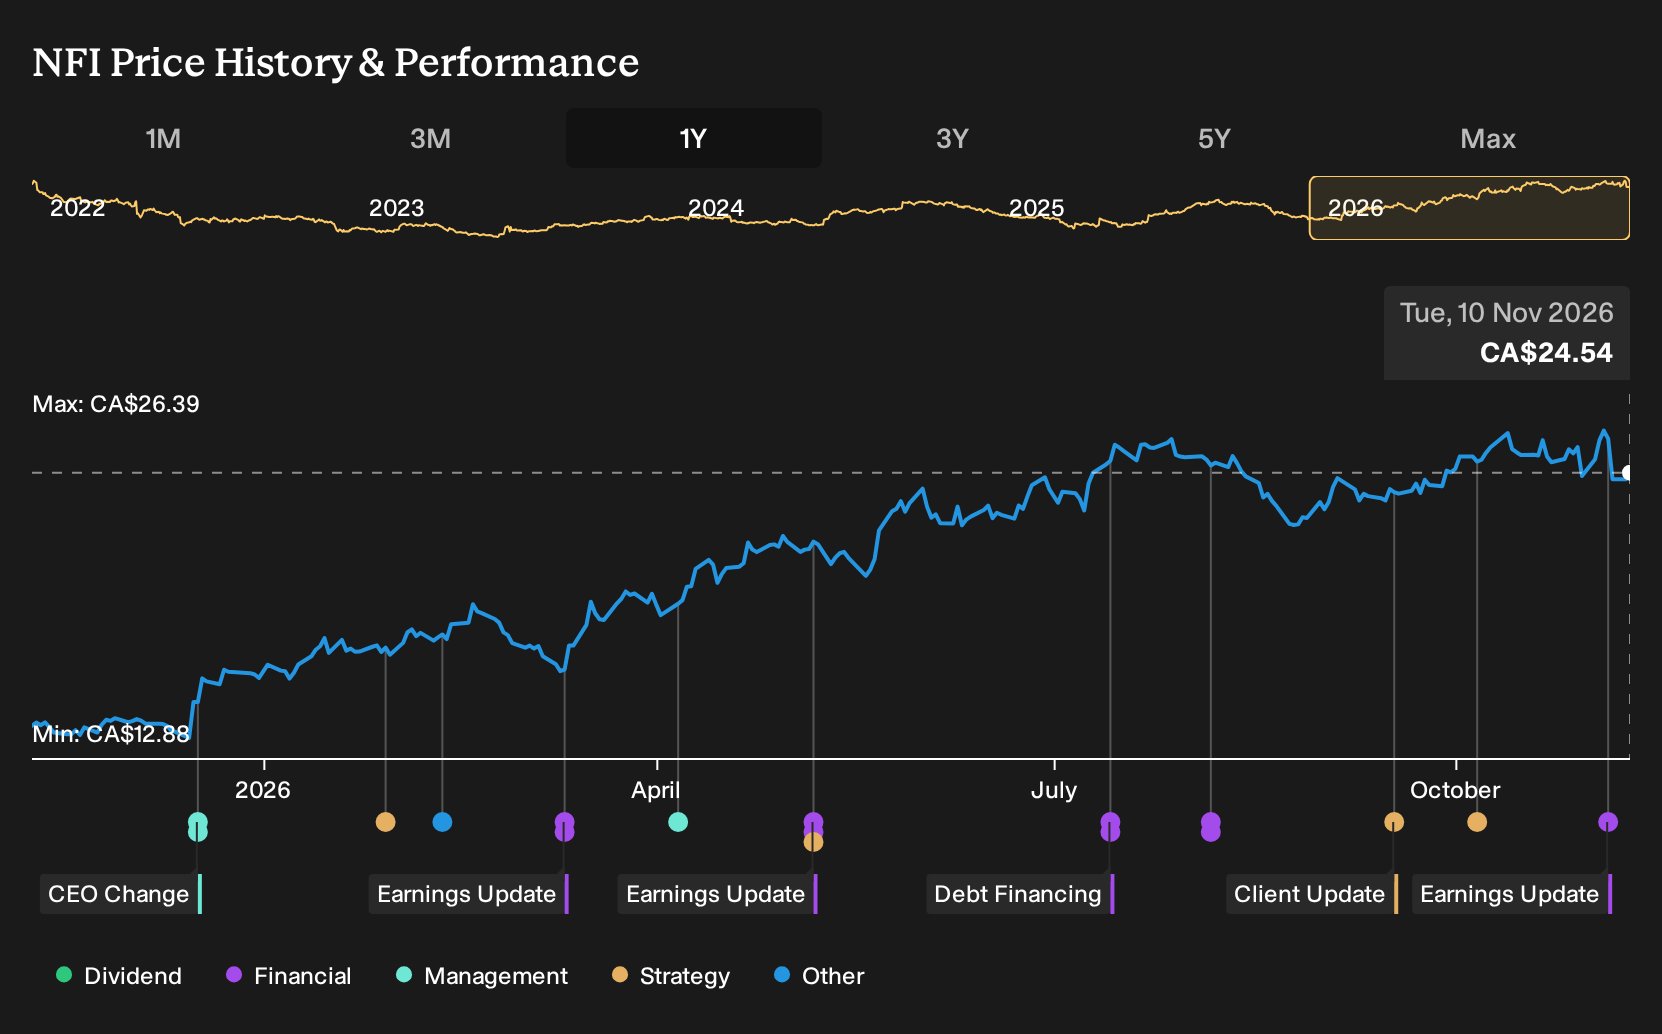
- NFI Group reported third quarter 2026 sales of US$1,007.44 million and net income of US$0.053 million, with nine month net income of US$28.96 million, alongside slightly positive earnings per share from continuing operations.
- The company raised the low end of its 2026 adjusted EBITDA guidance after firmer margins and steadier bus deliveries. It also absorbed a US$33.8 million non cash battery cell impairment linked to ongoing recall and replacement work.
- This article reviews how NFI Group's investment narrative is affected by the raised 2026 adjusted EBITDA guidance and margin performance.
Scan how NFI Group’s guidance and margins compare with peers by reviewing the hand picked list of solid balance sheet and fundamentals (5 results).
NFI Group Investment Narrative Recap
For someone holding NFI Group, the core belief is that this bus manufacturer can convert its large funded backlog into steadier production, healthier margins and enough cash to gradually reduce leverage. The third quarter numbers, with sales of US$1,007.44 million and a slim profit, point to an operation that is stabilising rather than surging. The slightly positive earnings per share from continuing operations show progress, but leave little room for execution missteps.
The analyst consensus Narrative on Simply Wall St highlights manufacturing margin and free cash flow as the key near term catalyst, and that still appears to be the focus. Raised adjusted EBITDA guidance supports the idea that margin work is gaining traction, although the US$33.8 million non cash battery cell impairment keeps the recall and replacement program front and centre as the biggest current risk, alongside interest coverage and the tough U.K. market.
The most relevant update for this earnings release is NFI Group’s record multi year funded backlog of about US$12.5b at the second quarter of 2026, which the analyst consensus Narrative on Simply Wall St treats as a core driver. The third quarter revenue line and firmer margins suggest the business is starting to work that order book through the factories at a more predictable pace.
That backlog, together with funded orders into 2027 and 2028 and public support programs in the U.S., Canada and U.K., frames the recent guidance raise as a test of execution rather than demand. For you as an investor, the key question is whether NFI Group can keep improving manufacturing and aftermarket profitability fast enough to offset recall costs, U.K. competition and interest expense so that leverage continues to ease over time.
NFI Group's narrative projects $4.7 billion in revenue and $282.3 million in earnings by 2029. This assumes 7.4% yearly revenue growth and an earnings increase of about $228 million from $54.0 million today.
Uncover why NFI Group's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame NFI Group around operating leverage rather than backlog risk. Before this earnings release, the bullish cohort floated revenue of about US$5.0b and earnings of roughly US$304.0m by 2029. You can treat this more upbeat script as one possible path that may shift after the latest guidance and margin news.
Explore 3 other NFI Group fair value estimates, including one that suggests up to 131% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NFI Group research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NFI Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NFI Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond NFI Group?
If you want to put NFI Group’s story in context, it can help to line it up against other companies with different balance sheets, income profiles and payout policies. The Simply Wall St Screener gives you a straightforward way to do that by filtering for the traits that matter most to you.
- Focus on financial resilience and cash strength by scanning a list of solid balance sheet and fundamentals (5 results) that can help you compare NFI Group to peers with similarly robust fundamentals.
- If you prefer potential mispriced opportunities, sort through a curated 5 high quality undervalued stocks that may sit closer to what you are looking for on price versus quality.
- For income minded investors, weigh NFI Group against a selection of 3 dividend fortresses that combine higher yields with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com