
Is SiWx917 Support Altering The Investment Case For Tuya (TUYA)?
- Tuya Smart recently announced that its TuyaOpen open source framework now supports Silicon Labs' SiWx917 low power Wi-Fi 6 and Bluetooth LE SoC, giving developers using TuyaOpen access to new hardware options and AI assisted coding tools for connected device prototyping.
- The SiWx917 integration into TuyaOpen, including support for Silicon Labs and Sekorm development kits, ties Tuya more tightly into hardware centric IoT workflows where its cloud services and multimodal AI can serve as the software layer for future connected products.
- We will now look at how Tuya's investment narrative could be influenced by TuyaOpen's new support for Silicon Labs' SiWx917 hardware.
Scan beyond Tuya and this SiWx917 update by sizing up a curated list of IoT and AI infrastructure plays through the 53 AI infrastructure stocks.
Tuya Investment Narrative Recap
To own Tuya, you need to believe the business can keep shifting from low margin IoT plumbing toward higher value AI software and services. The analyst consensus Narrative on Simply Wall St leans on that mix change, plus steady but not extreme earnings growth, as the core driver. The SiWx917 support fits that view operationally because it keeps TuyaOpen relevant to hardware centric customers building AI native devices.
The more immediate swing factor still looks like margin progress versus cost pressure and patchy end demand in areas like traditional lighting and IP cameras. This SiWx917 update does not rewrite those near term risks. It slightly improves Tuya’s position with developers, without directly solving semiconductor inflation, regional exposure or the question of how quickly energy and green tech projects scale.
The most connected piece of the analyst consensus Narrative on Simply Wall St here is the focus on Tuya’s developer ecosystem and tools like Tuya CoBuilder. That earlier view argued that faster development cycles and tighter developer lock in can support PaaS and SaaS revenue with operating leverage. TuyaOpen’s SiWx917 integration and AI assisted IDE point in the same direction operationally.
If Tuya actually converts more of those 2,090,000 plus registered developers into active projects on hardware like SiWx917, the main payoff would likely show up in usage of cloud services and AI applications rather than chip sales. The risk is that slow demand in some device categories or stalled regions offsets that pipeline. For you as an investor, the key question is whether tools like TuyaOpen can accelerate AI native devices and subscriptions fast enough to matter against those headwinds.
Tuya's narrative projects US$482.5 million revenue and US$100.4 million earnings by 2029. This assumes 12.3% yearly revenue growth and an earnings increase of about US$31.7 million from US$68.7 million today.
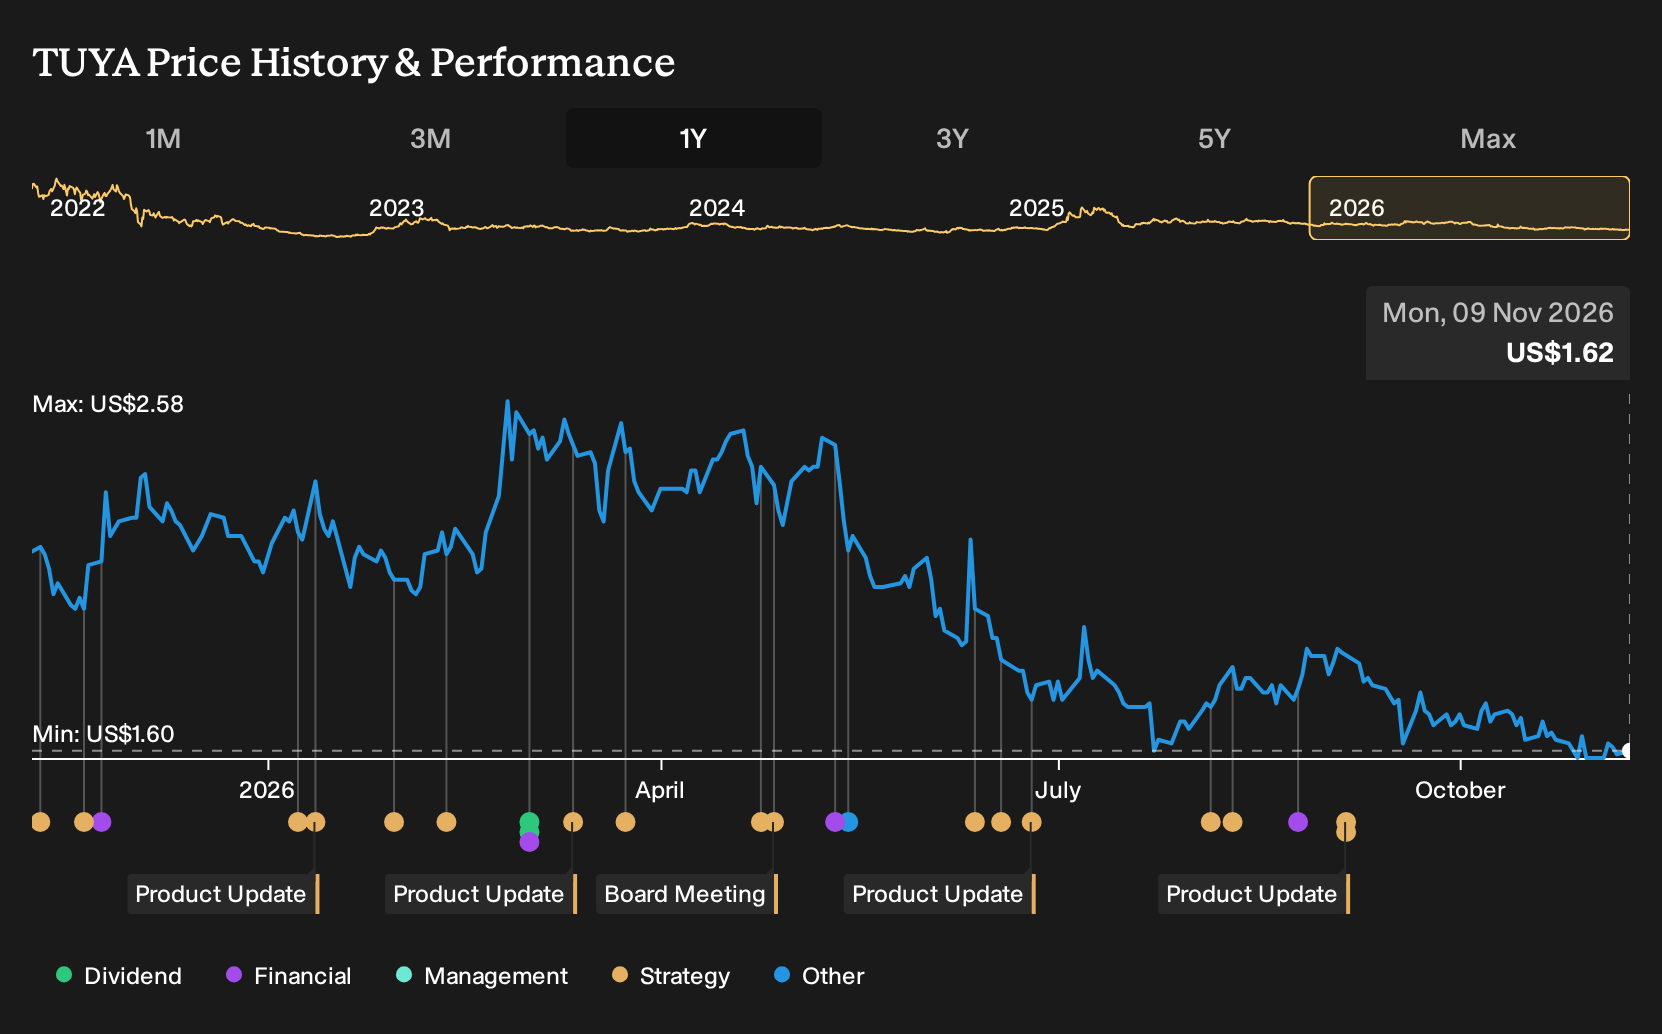
Uncover why Tuya's fair value indicates a 93% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You also have a very different story on Tuya from the lowest analysts. They worry that dependence on 318 premium customers and a PaaS heavy mix keeps earnings closer to US$96.8 million on about US$478.4 million revenue by 2029. Those views pre date the SiWx917 news, so you may see opinions shift.
Explore 4 other Tuya fair value estimates, including one that suggests it could be worth just $2.70!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tuya research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Tuya. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tuya's overall financial health at a glance.
Looking for more Tuya investment ideas?
If this Tuya story has you thinking about portfolio upgrades, it can help to widen the lens and compare it with other companies that fit different risk and return profiles using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, start with a curated set of 36 high quality undervalued stocks that may suit a more opportunistic mindset.
- For readers who care most about capital stability, consider using a filter focused on 30 resilient stocks with low risk scores to see which businesses look more resilient on multiple risk checks.
- When the goal is to back resilient operations with healthier balance sheets, shortlist companies from the list of solid balance sheet and fundamentals (24 results) and compare how they stack up against Tuya for financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com