
Freeport-McMoRan (FCX) On Its $4.5b Bagdad Bet And The Undervalued Narrative
Freeport-McMoRan (FCX) just signed off on a US$4.5b expansion of its Bagdad copper and molybdenum mine in Arizona, a project that is expected to more than double mining and milling capacity.
The Bagdad decision comes after a softer patch for the stock, with the share price down 18.16% over the past month and 12.87% over 90 days. It still shows a 16.14% year-to-date share price return and a 48.21% total shareholder return over one year, suggesting longer term momentum remains in place even as investors reassess near term risks and growth expectations.
Spot 16 top copper producer stocks that could also be gearing up for production gains as investors weigh Freeport-McMoRan's US$4.5b Bagdad expansion.For Freeport-McMoRan, a stock that has slid in recent weeks while greenlighting a US$4.5b growth project, the puzzle is whether price is reacting more to sentiment swings than to the underlying mine portfolio and cash generation potential.
Most Popular Narrative: 24% Undervalued
Against a last close of $60.31, the analyst consensus Narrative on Simply Wall St marks Freeport-McMoRan’s fair value at $79.07, implying a sizeable valuation gap that puts fresh focus on execution at Bagdad, Grasberg and the U.S. leach program.
Freeport-McMoRan’s large above-ground copper stockpiles and progress with new leach additives and heated solutions, already producing around 200 million pounds per year with a target of 800 million pounds annually within 3 to 4 years, point to potential low incremental cost volume growth that could support higher future revenue and structurally lower unit net cash costs.
See why 117 investors see Freeport-McMoRan as 24% undervalued.
The Narrative builds this valuation on analyst forecasts that revenue grows at 17.44% a year, profit margins reach 15.99% and earnings climb to $6.7b, all discounted at 8.99% to arrive at today’s fair value estimate of $79.07.
For anyone weighing the recent 1 year total shareholder return of 48.21% against a value score of 2 and mixed signals on future growth relative to the wider market, that gap between price and the Narrative’s fair value is the central question to test with personal assumptions on copper prices, project delivery and Indonesia risk.
Result: Fair Value of $79.07 (UNDERVALUED)
Still, the narrative around Freeport-McMoRan can quickly change if Indonesia policy shifts, or if big projects like Grasberg or Bagdad run into fresh delays or cost creep.
Find out about the key risks to this Freeport-McMoRan narrative.
Another View: What Multiples Say About Freeport-McMoRan
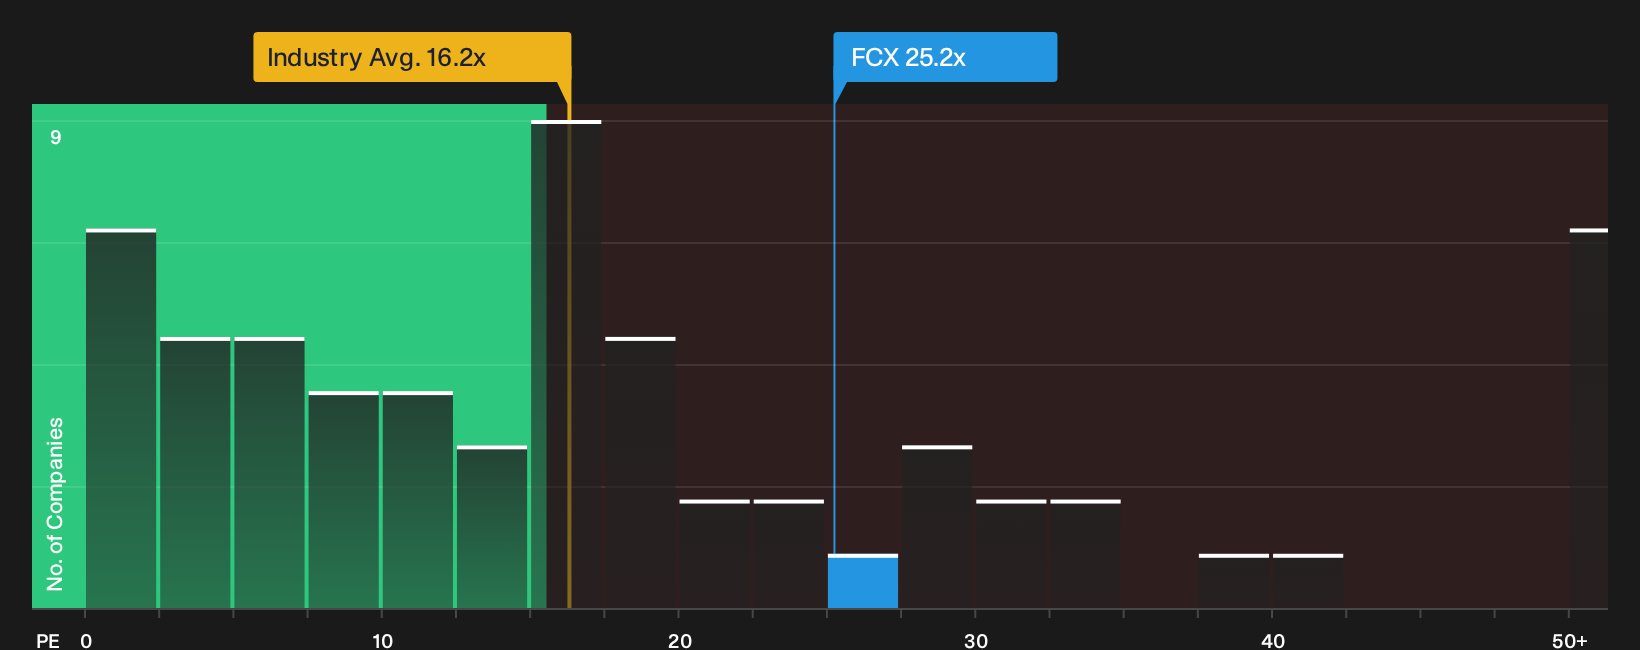
The first take portrays Freeport-McMoRan as undervalued on future cash flows, yet the current P/E of 25.2x tells a tighter story. It sits above the US Metals and Mining industry on 16.2x, above peers at 24x, and above the fair ratio of 22.3x, which suggests investors are already paying a premium for execution on growth projects. The question is whether personal expectations on copper pricing and project delivery justify paying more than both sector and fair ratio benchmarks.
That is where a closer look at valuation multiples can help test assumptions on risk and reward across different miners, instead of only focusing on one stock’s future cash flow model. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Freeport-McMoRan is split between premium multiples and an undervalued fair value story, so it pays to check the data yourself and move quickly once your thesis is clear. To see which potential upsides analysts are flagging, take a closer look at the 2 key rewards.
Looking for more investment ideas beyond Freeport-McMoRan?
If you only stop at Freeport-McMoRan, you miss a wider field of potential opportunities that could better match your risk tolerance and income goals.
- Target resilient compounding potential by scanning a 30 resilient stocks with low risk scores that may hold up better when conditions get choppy.
- Hunt for quality at a discount through a focused 36 high quality undervalued stocks that filters for stronger balance sheets and attractive pricing.
- Build a portfolio with steadier cash returns by zeroing in on a 5 dividend fortresses that screens for higher yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com