
Earnings Beat Could Be A Big Moment For Masco (MAS)
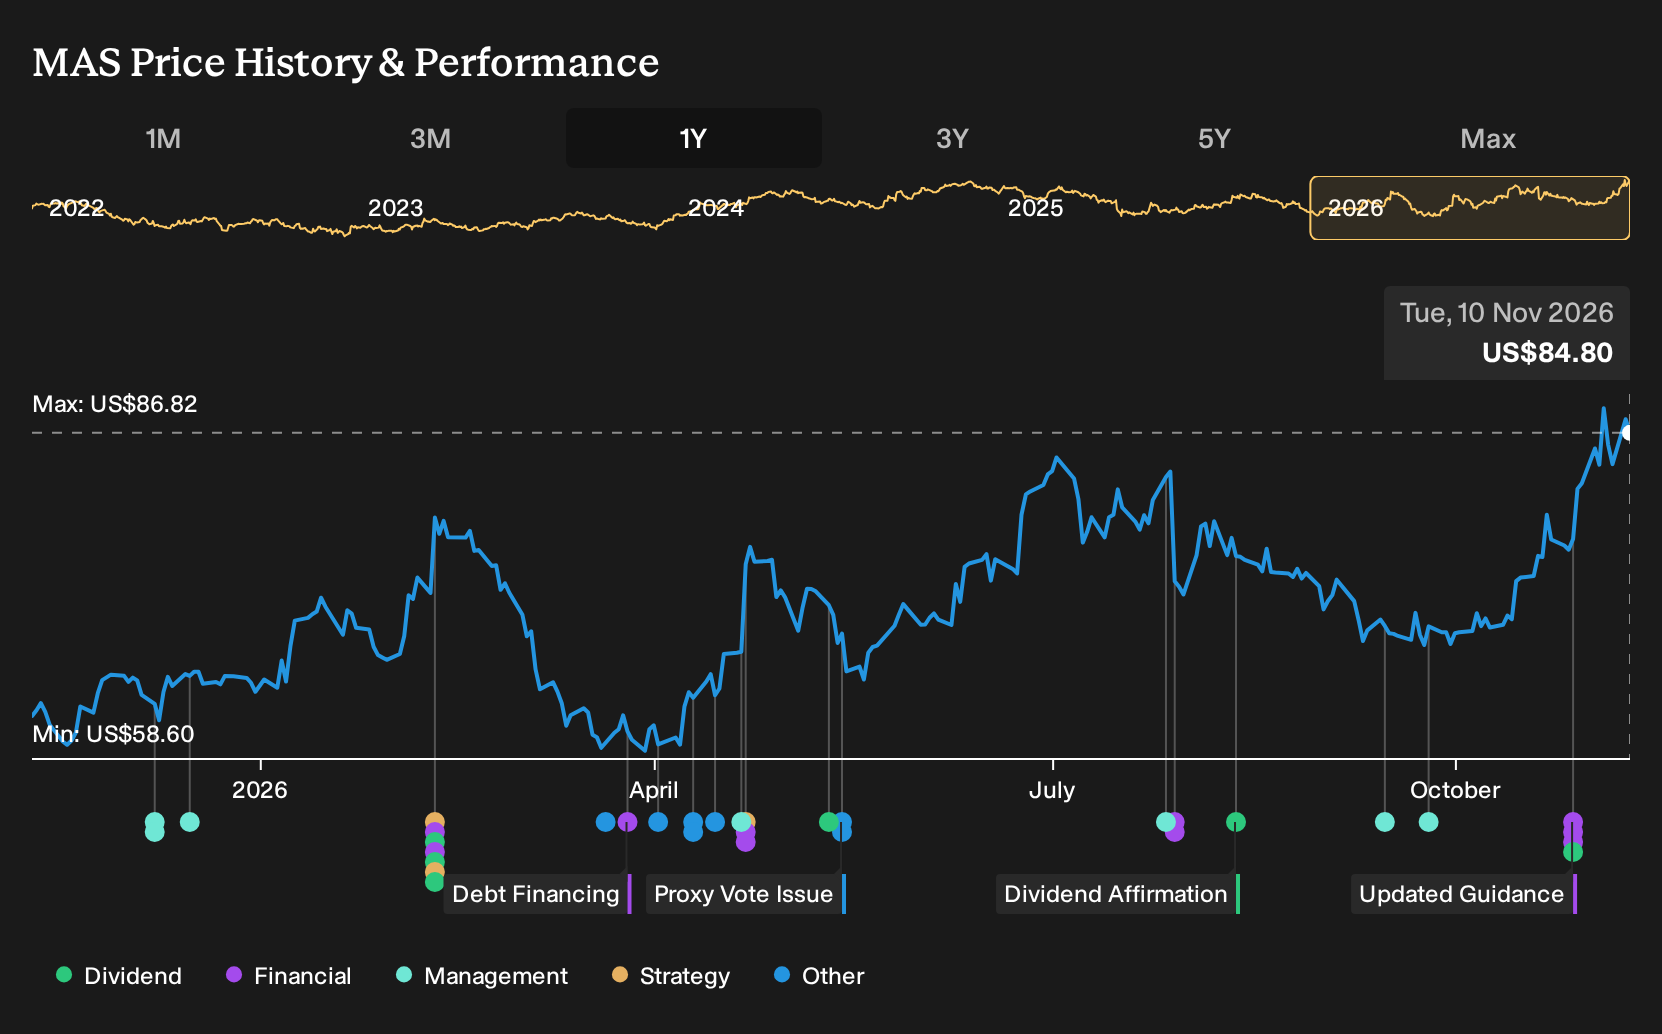
- Masco reported third quarter 2026 sales of US$1,966 million and net income of US$230 million, with basic and diluted EPS from continuing operations of US$1.17. The company also confirmed low single digit sales growth expectations and a higher full year operating profit margin outlook of 18% to 18.5%.
- The business paired these earnings with shareholder returns, including a US$0.32 quarterly dividend declared on October 28, 2026, and completion of a US$789.83 million buyback covering 11,346,986 shares. Masco is also planning a conference appearance that keeps its outlook and capital allocation decisions in investor focus.
- We will now look at how Masco’s stronger earnings and higher operating margin outlook interact with the existing renovation focused investment narrative.
Scan beyond Masco and see how other renovation focused peers line up on earnings strength and capital returns through our hand picked 36 high quality undervalued stocks.
Masco Investment Narrative Recap
Owning Masco means believing in repair and remodel demand over the long haul, and in the plumbing and decorative segments that julio, a Simply Wall St Community investor who wrote the Narrative, argues can grow off those structural trends. Recent third quarter results and the raised 2026 operating margin outlook to 18% to 18.5% keep the focus on execution rather than changing that core thesis.
The key near term catalyst is whether Masco can translate low single digit sales growth guidance into sustained earnings quality as housing affordability and sentiment shift. The main operational risk is exposure to a weaker R&R and new build cycle, paired with a balance sheet that carries a high level of debt and negative shareholders equity.
The most relevant announcement for that catalyst is management reaffirming low single digit sales growth for 2026 while lifting the operating margin target to 18% to 18.5%. That combination puts more weight on pricing, mix and cost control to support profit growth if volume remains modest.
For you as an investor, the updated margin guidance interacts directly with julio’s focus on attainable growth in plumbing and decorative architectural products. Execution against that profitability goal, together with disciplined capital allocation after a US$789.83m buyback and an ongoing US$0.32 quarterly dividend, will likely shape how much confidence investors place in Masco over the next few quarters.
Julio’s narrative arrives at a fair value of US$91.56 for Masco by applying 5.8% annual revenue growth and a future profit margin of 12.1%. Together, these assumptions support a higher steady state earnings profile than the business currently reports.
Uncover how Masco's fair value highlights an 8% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on Masco leans hard into margin risk. The lowest analysts were flagging mid single digit commodity inflation and tariff refund benefits rolling off, and were only penciling in about 2.1% annual revenue growth and earnings of roughly US$934.8 million by 2029. That is a more cautious storyline than julio’s. The fresh guidance plus the upcoming Baird conference could prompt you to revisit both sets of assumptions and decide which version feels closer to your own expectations.
Explore 3 other Masco fair value estimates, including one that suggests it could be worth just $82.37.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your Masco research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Masco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Masco's overall financial health at a glance.
Looking For More Investment Ideas Beyond Masco?
Once you have a view on Masco, it can help to cross check that thesis against other opportunities that match your preferred mix of quality, resilience and income. The Simply Wall St Screener is a useful way to compare like for like opportunities using consistent data in just a few minutes.
- If you want sturdier balance sheets and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that keeps financial strength front and center.
- For investors who care most about getting paid while they wait, filter for income focused opportunities through a curated set of 5 dividend fortresses that already clear a 5% yield hurdle.
- If you are hunting for quality that is not already crowded, cast the net wider with a hand picked group of 20 high quality undiscovered gems that combine strong fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com