
How Strong Earnings Will Impact Methanex Stock Investors
- Methanex reported third quarter 2026 sales of US$1,387.5 million and net income of US$264.98 million, issued 2026 production guidance of 9.0 million tonnes of methanol and 0.3 million tonnes of ammonia, and announced approval to repurchase up to 3,868,213 shares by November 2027.
- The combination of higher year on year sales and net income, stronger year to date methanol output, and a new buyback program highlights how Methanex is leaning on operating scale and capital allocation to shape its cash generation.
- The next step is to examine how Methanex's earnings profile and new share repurchase plan could influence its investment narrative.
Scan how Methanex's production scale and buyback plans compare with other potential opportunities by reviewing our curated list of 5 high quality undervalued stocks, which combine cash generation with balance sheet strength.
Methanex Investment Narrative Recap
To own Methanex, you need to be comfortable with a business built on large scale methanol output, contracted gas, and exposure to commodity pricing. The analyst consensus Narrative on Simply Wall St points to declining revenue and earnings forecasts over the next three years, so the recent jump in quarterly profit does not remove that medium term concern.
The 2026 guidance of 9.0 million tonnes of methanol and 0.3 million tonnes of ammonia keeps the near term story firmly about reliable production and gas availability. The biggest swing factor remains any disruption to contracted gas in regions like Chile or New Zealand. The latest update does not materially change that risk.
The new authorization to repurchase up to 3,868,213 shares, about 5% of Methanex’s equity, is the announcement that ties closest to the current earnings story. Management has paired strong recent profit, including US$264.98 million of net income in the third quarter, with a plan that reduces the share count if fully executed.
For you as a holder or potential holder, this buyback sits alongside catalysts such as higher output from Geismar and Chile and planned debt reduction. The program can amplify per share results if operations remain solid, yet it also leans on continued cash generation in a business that still faces gas supply, integration, and methanol pricing risks.
Methanex's narrative projects US$4.1b revenue and US$805.2 million earnings by 2029. This assumes 3.9% yearly revenue growth and an earnings increase of about US$850 million from a loss of US$45.0 million today.
Uncover how Methanex's fair value indicates a 6% potential downside to its current price, suggesting that the current premium may not be sustainable.
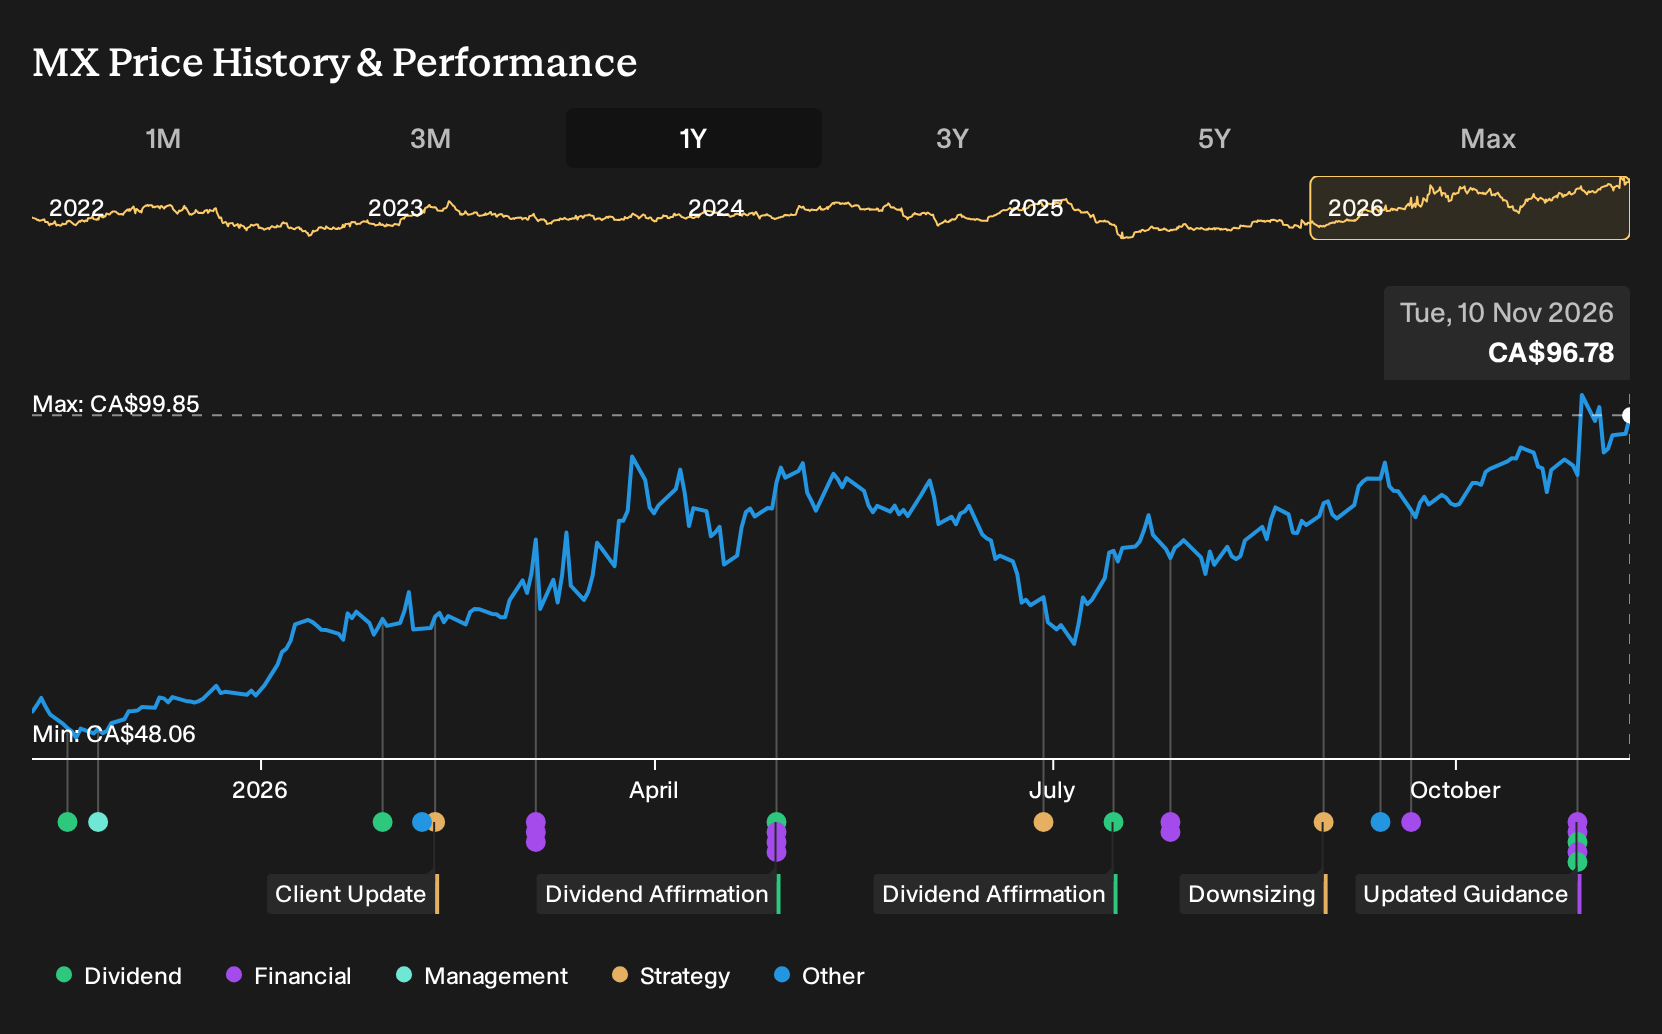
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community span roughly US$91 to US$155 per share, which is a wide spread for Methanex. That gap reflects private investors baking in very different views on gas security, the OCI integration, and methanol demand. Use it as a prompt to compare several contrasting viewpoints before deciding where you sit.
Explore 2 other Methanex fair value estimates, including one that suggests an upside potential of up to 60% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your independent research and judgment.
- A great starting point for your Methanex research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Methanex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Methanex's overall financial health at a glance.
Looking for more investment ideas beyond Methanex?
If Methanex has sharpened your focus on cash generation and capital allocation, it can be useful to line it up against a wider set of candidates that share some of those qualities. The Simply Wall St Screener lets you filter for exactly the mix of balance sheet strength, income potential, or underappreciated quality you want to research next.
- For investors who care most about resilient businesses with fewer financial red flags, start by scanning our 9 resilient stocks with low risk scores, which may offer a steadier ride through different market conditions.
- If dependable income is high on your priority list, widen your watchlist with 3 dividend fortresses, which combine higher yields with a focus on sustainability.
- To hunt for companies that are quietly executing away from the market spotlight, review our 7 high quality undiscovered gems, which pair solid fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com