
Return To Profit Could Be A Game Changer For Westlake (WLK)
- Westlake Corporation reported third quarter 2026 sales of US$2,981 million and net income of US$6 million, compared with a net loss a year earlier, with basic and diluted earnings per share from continuing operations of US$0.05.
- The nine month figures showed sales of US$8,904 million and net income of US$97 million, indicating a shift back to profitability and providing evidence of how Westlake’s cost actions and portfolio mix are reflected in reported earnings.
- We now consider how Westlake’s investment narrative is affected by this return to positive earnings in the latest quarter.
Scan how Westlake's return to positive earnings compares with other companies showing resilient balance sheets and fundamentals in our curated list of solid balance sheet and fundamentals (24 results).
Westlake Investment Narrative Recap
To own Westlake, you need to be comfortable with a chemicals and building products group that is heavily exposed to global pricing cycles and North American construction, yet is trying to lean on cost efficiency and portfolio mix to stabilise earnings. The analyst consensus narrative on Simply Wall St focuses on that feedstock cost advantage and the profitability improvement plan. The return to positive quarterly earnings helps credibility around that story, but it does not remove sensitivity to commodity prices or volumes.
The sharp swing from heavy losses a year ago to US$6 million in quarterly profit and US$97 million over nine months suggests the cost actions are flowing into reported results. The biggest near term swing factor still appears to be pricing and utilisation in Performance and Essential Materials, with the main risk coming from prolonged oversupply and any renewed spike in North American energy and feedstock costs that could erode margins again.
One of the key reference points for this earnings result remains management’s three pillar profitability improvement plan. The plan is targeted to add US$600 million of EBITDA benefit in 2026, with about US$300 million reported as realised by mid year. Westlake’s move back into the black in the first nine months of 2026 gives you a clearer line of sight to how those efforts are interacting with the demand backdrop.
Execution on cost, plant reliability and the reshaping of the chlorovinyls footprint are central to the catalysts outlined in the analyst consensus narrative on Simply Wall St. The latest results provide fresh data to assess whether those initiatives are translating into more stable earnings, while the risk side of the ledger still includes weaker housing activity for the HIP segment and dividend cover that relies on further progress in profitability.
Westlake assumptions and valuation anchors
Westlake's narrative projects US$12.7 billion revenue and US$661.8 million earnings by 2029. This implies 4.0% yearly revenue growth and an earnings increase of about US$1.9 billion from current earnings of a US$1.2 billion loss.
Those analyst assumptions rest on profit margins shifting from a current 10.9% loss to a 5.2% positive margin over roughly three years. That margin swing is material for a chemicals and building products group, where relatively small changes in pricing or utilisation can move net income sharply. The forecast path to higher profitability therefore matters as much as the headline revenue trajectory.
For readers thinking about what has to go right for Westlake, the earnings bridge is clear in the sell side numbers. The firm would need to move from loss making, through breakeven, to more than half a billion dollars of annual profit within a few years, with analysts currently using 2029 as the reference year that ties the story together.
On valuation, the consensus assumes that by 2029 Westlake reaches US$12.7 billion of sales and US$661.8 million of earnings and that the stock trades on a P/E of 19.3x at that point. That multiple is lower than the current P/E used for the broader US chemicals peer group at 22.9x in the same source. In other words, the bullish stance in that report is less about paying a premium multiple and more about earnings reaching the level implied by the forecasts.
Analysts cited in the Simply Wall St report cluster around a US$79.18 price target, with the current share price referenced at US$65.83 and individual targets ranging from US$65.00 to US$114.00. The spread shows that professionals looking at the same data reach different conclusions about how much of the cost plan, feedstock advantage and portfolio reshaping will ultimately flow into earnings per share and what valuation that profit stream might support.
For you as an investor, the useful takeaway is not a single fair value number but the set of hurdles embedded in the consensus case. The forecasts assume steady 4.0% annual revenue growth, a substantial swing in margins, a move to US$661.8 million in earnings by 2029 and a P/E that remains below the sector reference point, all while shares outstanding drift slightly lower as buybacks continue.
Uncover why Westlake's fair value indicates a 25% potential upside to its current price that may not last much longer.
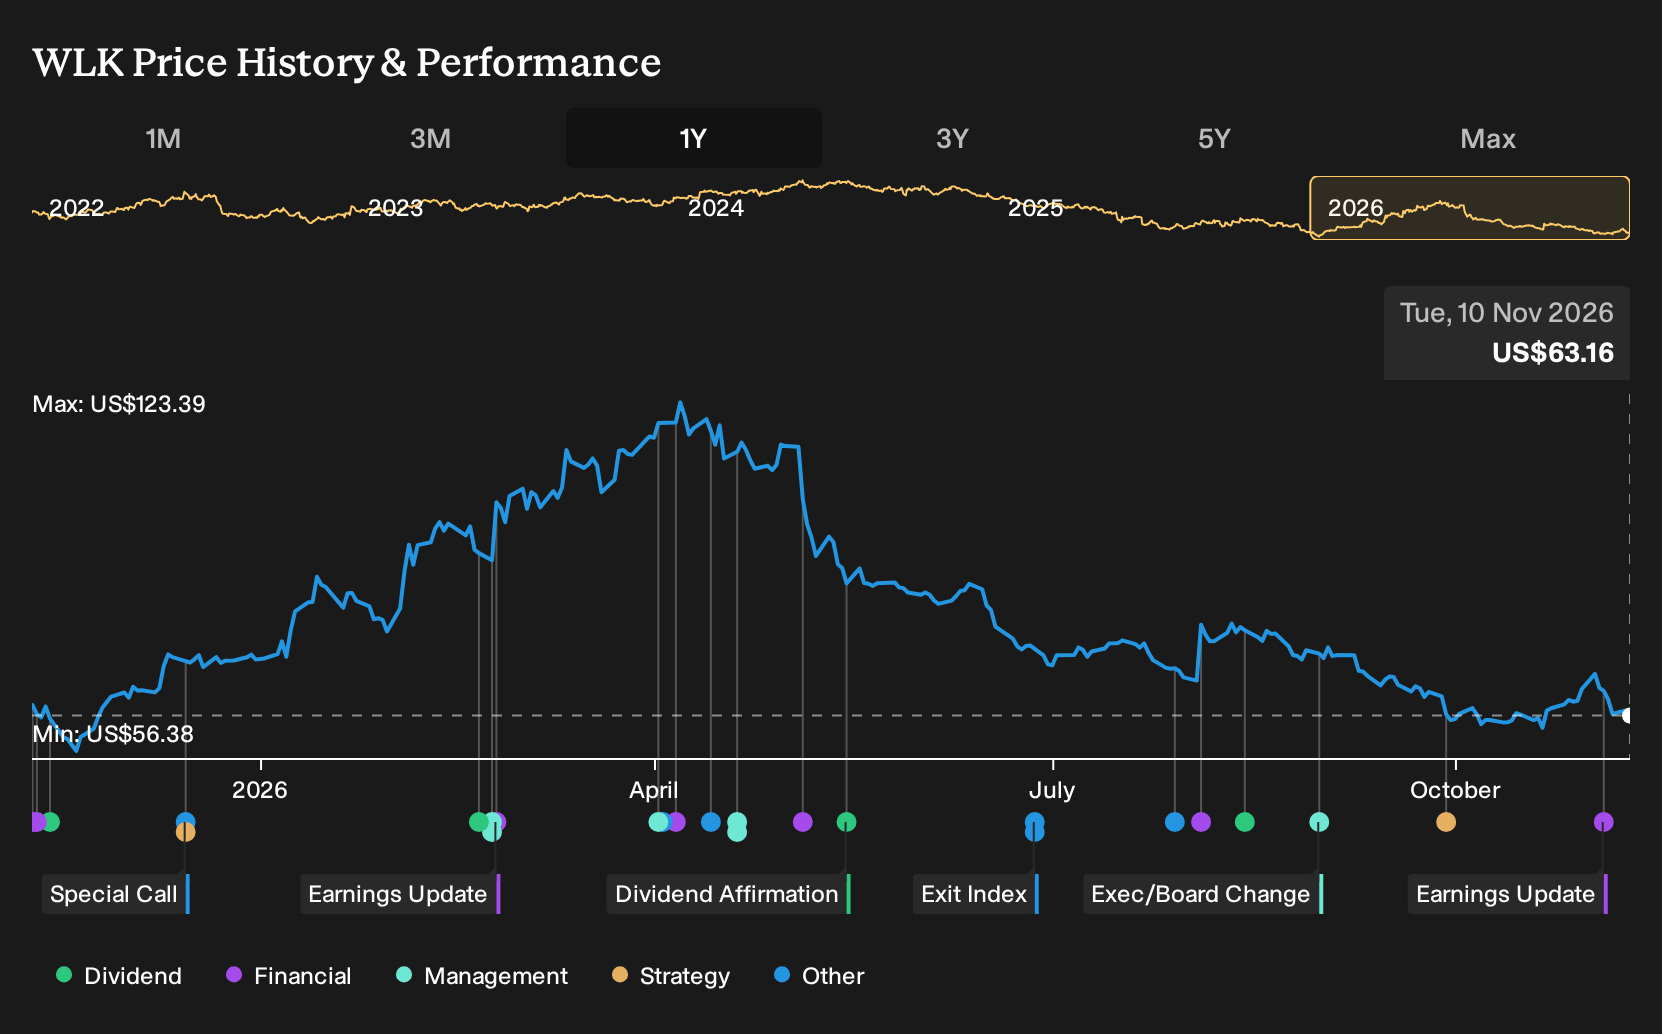
Exploring Other Perspectives
Some of the lowest ranked analysts focus on the risk that European power costs and oversupplied polyethylene markets keep pressure on Westlake margins. Before this earnings release, that group was only pencilling in roughly flat revenue around US$11.5b and about US$166.7 million in earnings by 2029. You can treat this quarter’s return to profit as fresh evidence to test against that more cautious view and decide which narrative feels closer to your own expectations.
Explore 2 other Westlake fair value estimates, including one that suggests as much as 9% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Westlake research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Westlake. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Westlake's overall financial health at a glance.
Looking for more Westlake investment ideas?
Once you have formed a view on Westlake, it can help to compare the story with other companies that share similar financial traits or risk profiles. The Simply Wall St Screener lets you filter for exactly the mix of balance sheet strength, valuation and income profile that fits your style, so you are not relying on a single ticker to do all the heavy lifting.
- If capital preservation comes first for you, start with a universe filtered for resilient businesses by checking out the 30 resilient stocks with low risk scores.
- If you want income to be a bigger part of your returns, scour the market for reliable high yielders through the 5 dividend fortresses.
- If you prefer to focus on overlooked opportunities with solid fundamentals, widen your watchlist using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com