
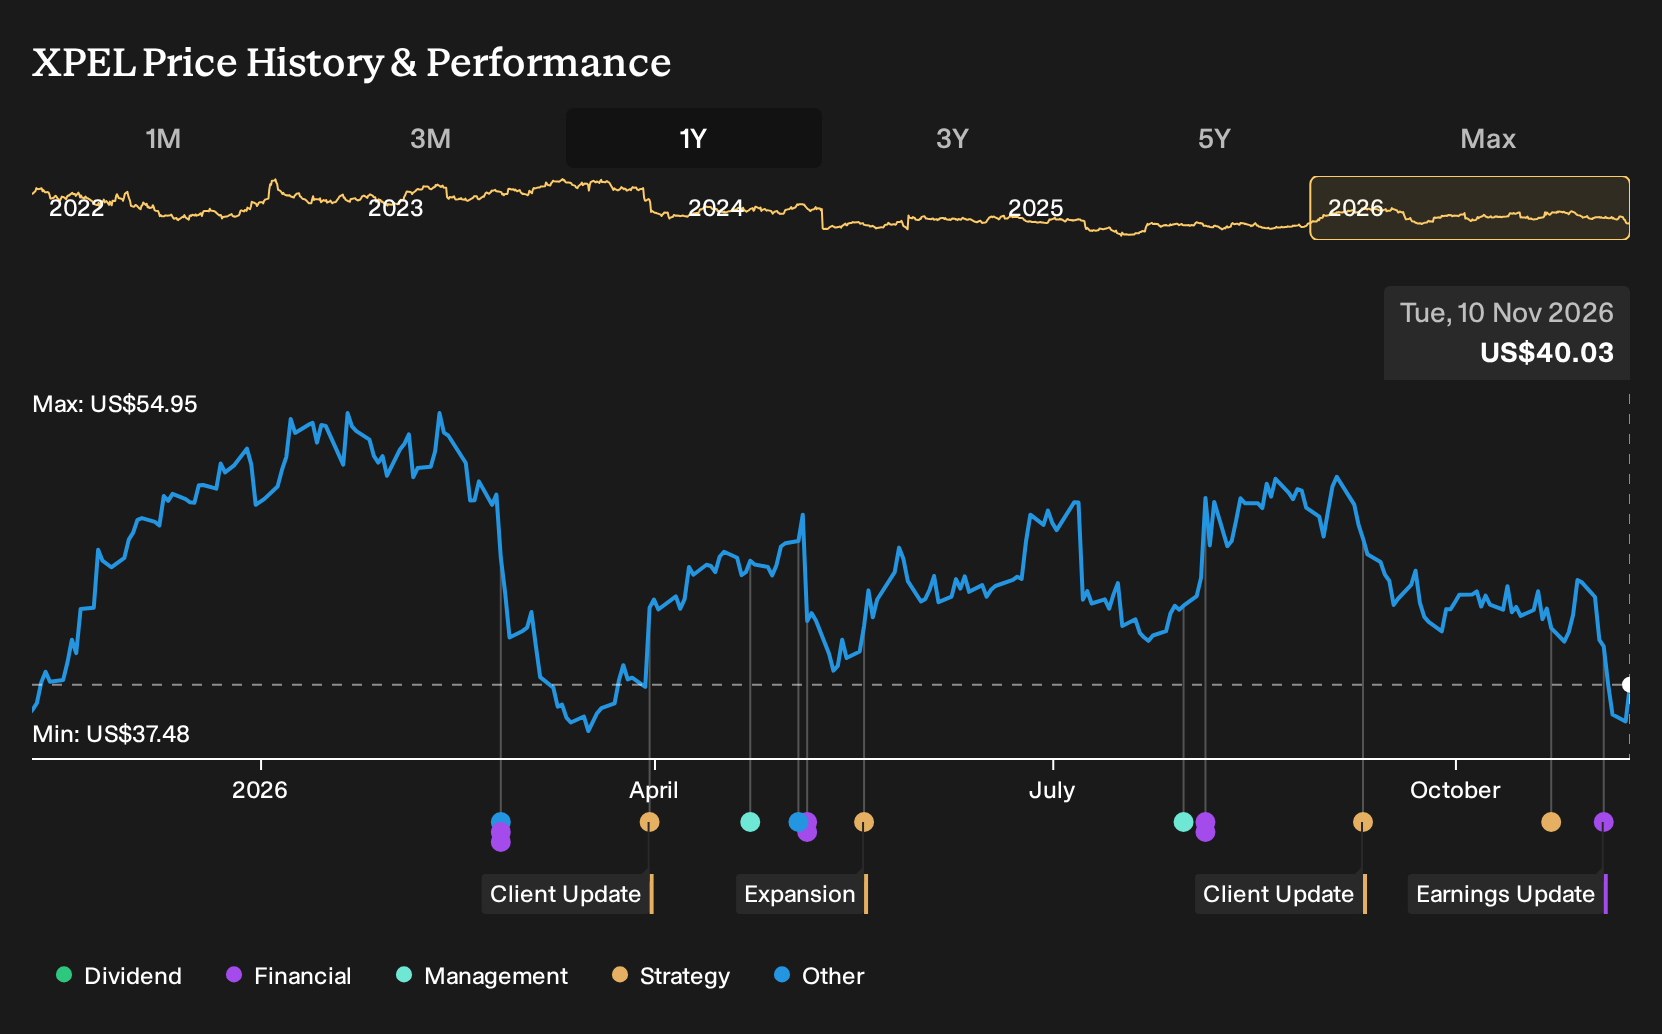
Why XPEL (XPEL) Is Up 5.3% And What's Next
- XPEL reported third quarter 2026 revenue of US$137.81 million and net income of US$16.34 million, with basic and diluted EPS of US$0.59, all above the prior year period.
- The nine month figures show XPEL generating US$398.22 million of revenue and US$44.73 million of net income, which highlights how the current operating model and product mix are supporting profitability across a longer stretch of the year.
- This article will now explore how XPEL's higher third quarter earnings per share might shape the broader investment narrative around the business.
Scan beyond XPEL's latest earnings beat and size up other profitability driven opportunities with the hand picked 36 high quality undervalued stocks that pair cash generation with balance sheet strength.
XPEL Investment Narrative Recap
XPEL appeals to shareholders who back the idea that a niche, globally distributed protective film business can keep turning product demand into steady earnings. The latest quarter, with US$137.81 million of revenue and US$16.34 million of net income, supports that thesis by showing the model working across both films and services. The near term catalyst still sits in smooth execution of expansion projects and product mix, and this update largely reinforces that focus.
The biggest near term risk is still operational, not financial. XPEL is committing about US$110 million to manufacturing and supply chain projects alongside a US$44.8 million term loan. Any delay, cost overrun or weaker facility utilization could pressure margins and earnings, even with higher quarterly EPS reported.
The analyst consensus Narrative on Simply Wall St highlights vertical integration and international roll out as central to the story. The third quarter and nine month figures, with US$398.22 million of revenue and US$44.73 million of net income, tie directly into that by showing the current network supporting an 11.2% net margin while those projects are being funded and built.
For catalysts, XPEL’s higher margin mix remains front and center. Window film and installation services accounted for more than 40% of Q2 2026 sales combined, and the fresh Q3 earnings give investors updated evidence on how that mix is influencing EPS. If these lines continue to gain share, execution on the new manufacturing footprint becomes even more important because any stumble there could offset the benefit from richer product economics.
XPEL Forecasts And What Analysts Are Baking In
XPEL's analyst narrative points to revenues of US$701.0 million and earnings of US$123.4 million by 2029. That path assumes about 11.3% yearly revenue growth and an earnings increase of roughly US$68.7 million from US$54.7 million today.
Uncover why XPEL's fair value indicates a 54% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on the risk that XPEL’s heavy manufacturing spend could weigh on returns for longer than consensus implies. The most cautious analysts were only penciling in about US$657.8 million of revenue and US$122.1 million of earnings for 2029 before this Q3 report. That represents a slower build and highlights how far opinions can differ. Use that spread as a prompt to compare several narratives and decide which set of assumptions feels closest to your own.
Explore 2 other XPEL fair value estimates, including one that suggests it could be worth just $57.00!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your XPEL research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for XPEL. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate XPEL's overall financial health at a glance.
Looking For More Investment Ideas Beyond XPEL?
Once you have framed your view on XPEL, it often helps to compare that thesis with a few very different types of opportunities sourced from the same data driven process.
- If you want potential upside with a safety net, start with a 30 resilient stocks with low risk scores that screens for resilience before excitement.
- For investors who care about quality today as much as future prospects, check out a list of solid balance sheet and fundamentals (24 results) that surfaces businesses with the financial footing to support their plans.
- If you are hunting for underfollowed opportunities, use a 20 high quality undiscovered gems to spot lesser known stocks with fundamentals that already stack up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com