
Is Ralph Lauren (RL) Undervalued Following Its Earnings Beat And Higher Outlook?
Ralph Lauren (RL) just paired stronger than expected second quarter results with a higher full year 2027 revenue outlook, putting fresh attention on how this premium apparel group is balancing demand and macro pressures.
Ralph Lauren’s latest update lands after a strong run, with a 30-day share price return of 7.63% and year-to-date gain of 10.23% helping extend a 1-year total shareholder return of 20.99% and a very large 3-year total shareholder return of about 7x. This suggests that investors view the raised 2027 outlook and recent earnings beat as reinforcing, rather than challenging, the longer term narrative around the brand.
Scan how Ralph Lauren’s renewed guidance compares with other premium consumer stocks by checking the hand-picked 36 high quality undervalued stocks that also pair resilient demand with tighter execution.
Ralph Lauren now trades near US$400, with analysts and intrinsic models implying roughly US$445 at the top end. After that earnings pop, how much of the valuation gap still looks real?
Most Popular Narrative: 10% Undervalued
On the Simply Wall St analyst consensus Narrative, Ralph Lauren screens as undervalued, with a fair value of about $446 against a last close near $400. That view leans heavily on a mix of direct to consumer strength, Asia exposure and pricing power.
Accelerating international expansion, especially in Asia and Greater China where Asia revenue recently grew around the mid 20% range and China has risen to about 10% of company sales, positions Ralph Lauren to keep scaling in higher growth regions, which can support future revenue and earnings.
Strong digital adoption and a higher mix of direct to consumer activity, with direct to consumer now about 70% of revenue and global retail comps in the low to mid teens, increases exposure to higher margin channels and can support structurally stronger net margins.
See why 29 investors see Ralph Lauren as 11% undervalued.
Analysts in that Narrative apply an 8.9% discount rate to Ralph Lauren's projected cash flows and arrive at a fair value of about $446, which is also close to the current consensus target near $447. With the share price around $400, that leaves a valuation gap of roughly 10% that rests on expectations for mid single digit revenue growth, margin gains toward about 12.9% and earnings rising toward $1.2b by 2029.
The same framework assumes a future P/E of about 26x on those 2029 earnings, higher than the recent 22x multiple and above the US Luxury average of 16.2x. The case for upside therefore depends on Ralph Lauren continuing to justify a premium through Asia growth, direct to consumer mix and category expansion in areas like women's apparel and handbags. If those pieces fail to materialise or risks in Europe, wholesale credit or pricing sensitivity bite harder than expected, the gap between the model's value and the market price could close very differently.
Result: Fair Value of $446 (UNDERVALUED)
Still, the Ralph Lauren thesis relies on growth in Asia and direct-to-consumer channels to continue offsetting European softness and any further impact from weaker wholesale partners.
Find out about the key risks to this Ralph Lauren narrative.
Another View: Ralph Lauren Through The P/E Lens
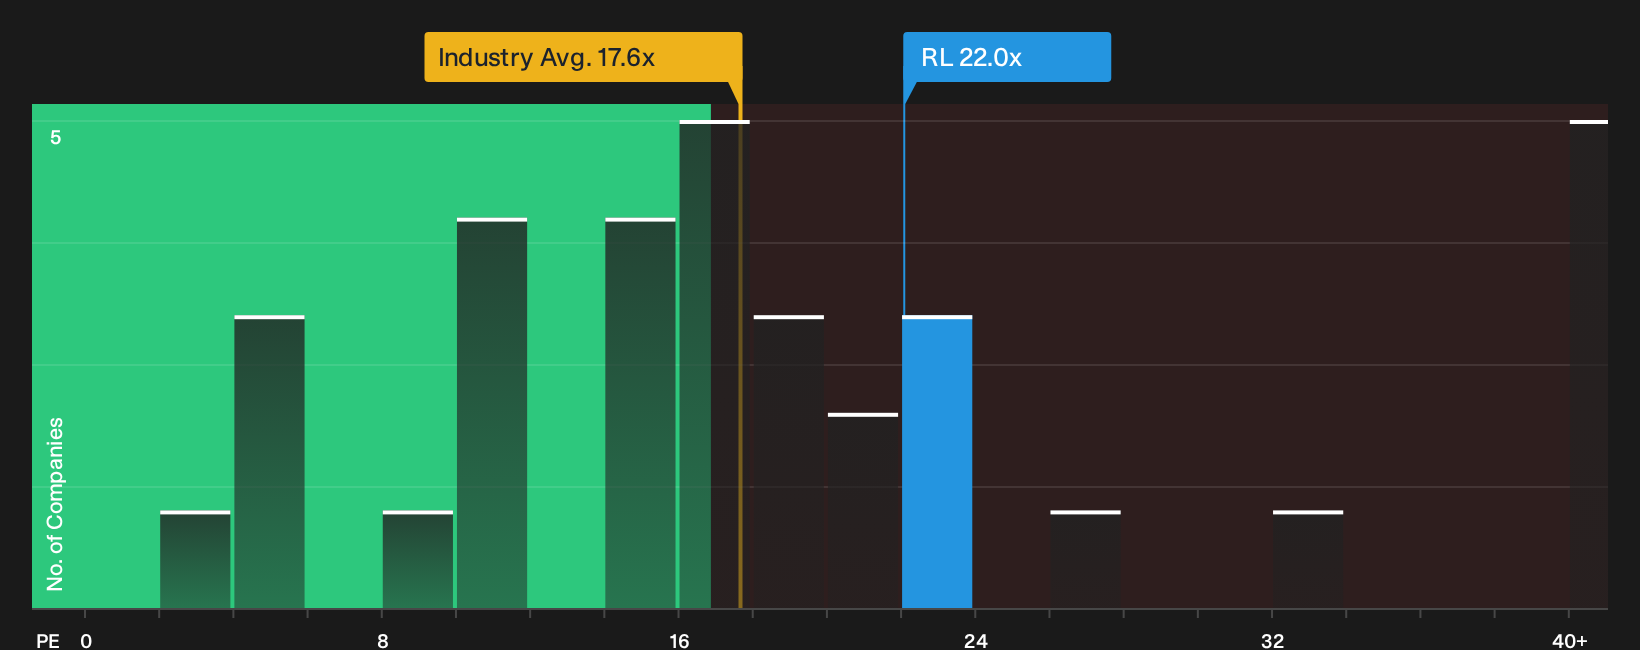
The DCF-based fair value suggests Ralph Lauren shares trade at about a 9.4% discount to an estimated future cash flow value of roughly $441. That picture shifts when you look at the current P/E of 22x, which sits above a fair ratio of 20.7x and also above both the US Luxury average of 17.6x and a peer average of 18.7x. For investors, that mix of slight DCF upside and richer earnings multiples raises a simple question: Is this a quality premium you are comfortable paying or a margin of safety that is thinner than it looks?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Ralph Lauren so far. If that balance of risk and reward feels tight, act promptly and review the full picture by checking the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Ralph Lauren?
If Ralph Lauren has sharpened your focus on quality, do not stop here. Broaden your opportunity set with screeners that surface different types of potential winners.
- Target reliability first and scan a 30 resilient stocks with low risk scores to see businesses that pair resilience scores with steadier profiles than many headline names.
- Hunt for value pockets and run a 36 high quality undervalued stocks that highlights companies where fundamentals and pricing look out of sync.
- Spot underfollowed potential and review a 20 high quality undiscovered gems that flags high quality businesses still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com