
Waste Connections (WCN) Could Be 8% Undervalued After Raising Cash Flow Outlook And Dividend
Dividend move and cash flow outlook put Waste Connections in focus
Waste Connections (WCN) raised its full-year adjusted free cash flow outlook and approved a 10% dividend increase, its sixteenth straight year of double-digit annual payout growth, drawing fresh attention from income-focused investors.
The higher full-year free cash flow outlook and richer dividend arrive as Waste Connections shares trade at $191.14, with a 30-day share price return of 25.07% and a 1-year total shareholder return of 15.13%, indicating improving momentum following several years of compounded gains.
Scan beyond Waste Connections and size up other income-focused opportunities with our handpicked 5 dividend fortresses that pair payout strength with resilient business models.
After a sharp 30 day run and a richer dividend, Waste Connections now poses a simple question for income investors: pay up for momentum today, or wait for a calmer entry before committing new cash?
Most Popular Narrative: 7.6% Undervalued
The analyst consensus Narrative on Simply Wall St estimates Waste Connections' fair value at $206.90 per share, compared with the recent $191.14 close. This frames a modest discount that rests on execution in pricing, margins and cash conversion.
The AI and broader digital initiative set, including the already deployed commercial pricing tool, a routing system now in pilot and customer service applications scheduled for rollout through 2027, is expected by management to deliver up to about 100 basis points of EBITDA margin uplift as these projects move from upfront spending to full operational impact. Several of these initiatives, such as routing and customer service tools, are still in pilot or early deployment and will take years to reach scale.
See why 19 investors see Waste Connections as 8% undervalued.
Result: Fair Value of $206.90 (UNDERVALUED)
Still, the Chiquita Canyon cash drag and ongoing fuel cost pressure could unsettle confidence if expenses run higher or persist longer than management currently outlines.
Find out about the key risks to this Waste Connections narrative.
Another view on Waste Connections valuation
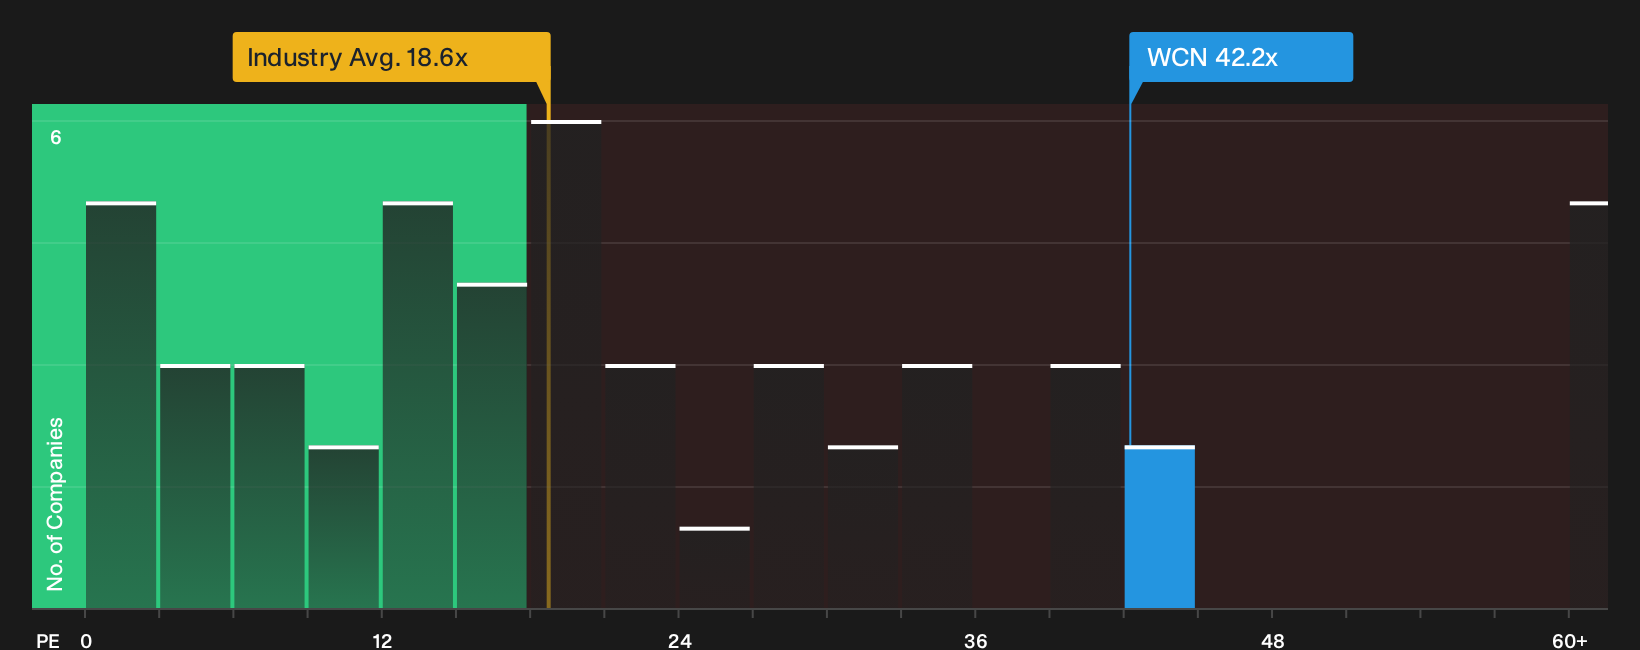
The first take frames Waste Connections as about 7.6% undervalued against a $206.90 fair value, yet the P/E picture tells a tougher story. On a P/E of 42.2x versus a fair ratio of 29x, the shares carry a rich premium to both the US Commercial Services industry at 18.6x and peers at 32.1x. That gap points to real valuation risk if sentiment cools. How comfortable are you paying up for quality when the multiple is already stretched?
Our P/E based view comes out far less forgiving than the cash flow driven work. This raises a simple question for investors comparing methods: which lens do you trust more when the two send different signals on Waste Connections at $191.14? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Waste Connections valuation and risk can feel messy. Move fast, review the underlying data and form your own view with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Waste Connections?
Do not stop with Waste Connections. Broaden your watchlist now, compare different business models and uncover opportunities that might suit your income or total return goals better.
- Target resilient balance sheets and steadier earnings profiles by scanning companies in our list of solid balance sheet and fundamentals (24 results).
- Hunt for quality businesses that the market may be pricing conservatively with the focused 36 high quality undervalued stocks.
- Build a diversified income stream by reviewing companies in the 9 elite penny stocks with strong financials that offer differentiated payout and growth combinations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com