
Corcept Therapeutics (CORT) Shares Dropped, So What Is Driving Attention Now?
Corcept Therapeutics (CORT) just posted third quarter results that sharply changed its earnings picture, with net income of US$126.78 million and basic earnings per share from continuing operations of US$1.17.
Corcept Therapeutics has seen its share price fall 39.5% over the past month and 34.6% over the past quarter, even after reaffirming 2026 revenue guidance of US$1.1b to US$1.2b. The stock is still up 92% on a year to date share price basis and has delivered a 188.3% total shareholder return over three years, which points to long term momentum even as shorter term sentiment cools around the recent earnings and ongoing legal dispute over Korlym generics.
Spot opportunities with similar earnings momentum and legal overhangs by scanning our curated list of 20 high quality undiscovered gems that share Corcept Therapeutics' blend of profitability and controversy.Corcept Therapeutics now sits in an awkward middle ground, with earnings jumping while the share price has already run hard then slipped. Is meaningful upside still in front of you, or was most of it left in the rear-view mirror?
Most Popular Narrative: 48% Undervalued
Corcept Therapeutics closed at $73.35, while the analyst consensus Narrative on Simply Wall St pegs fair value at $141 using a 7.24% discount rate. This points to a wide gap that the Narrative links to the pipeline rather than Korlym alone.
The shift from a single Cushing’s product to a broader cortisol modulation portfolio, including Lifyorli in ovarian cancer, late-stage oncology programs, and Phase II or III efforts in ALS and MASH, points to a more diversified revenue base and potential improvement in earnings resilience as dependence on any one product declines.
See why 60 investors see Corcept Therapeutics as 48% undervalued.
Result: Fair Value of $141 (UNDERVALUED)
Still, Corcept Therapeutics carries real pressure points, including Korlym concentration and the risk that higher commercialization and pipeline spending will squeeze earnings even as revenue expectations rise.
Find out about the key risks to this Corcept Therapeutics narrative.
Another View: Corcept Therapeutics Through The P/E Lens
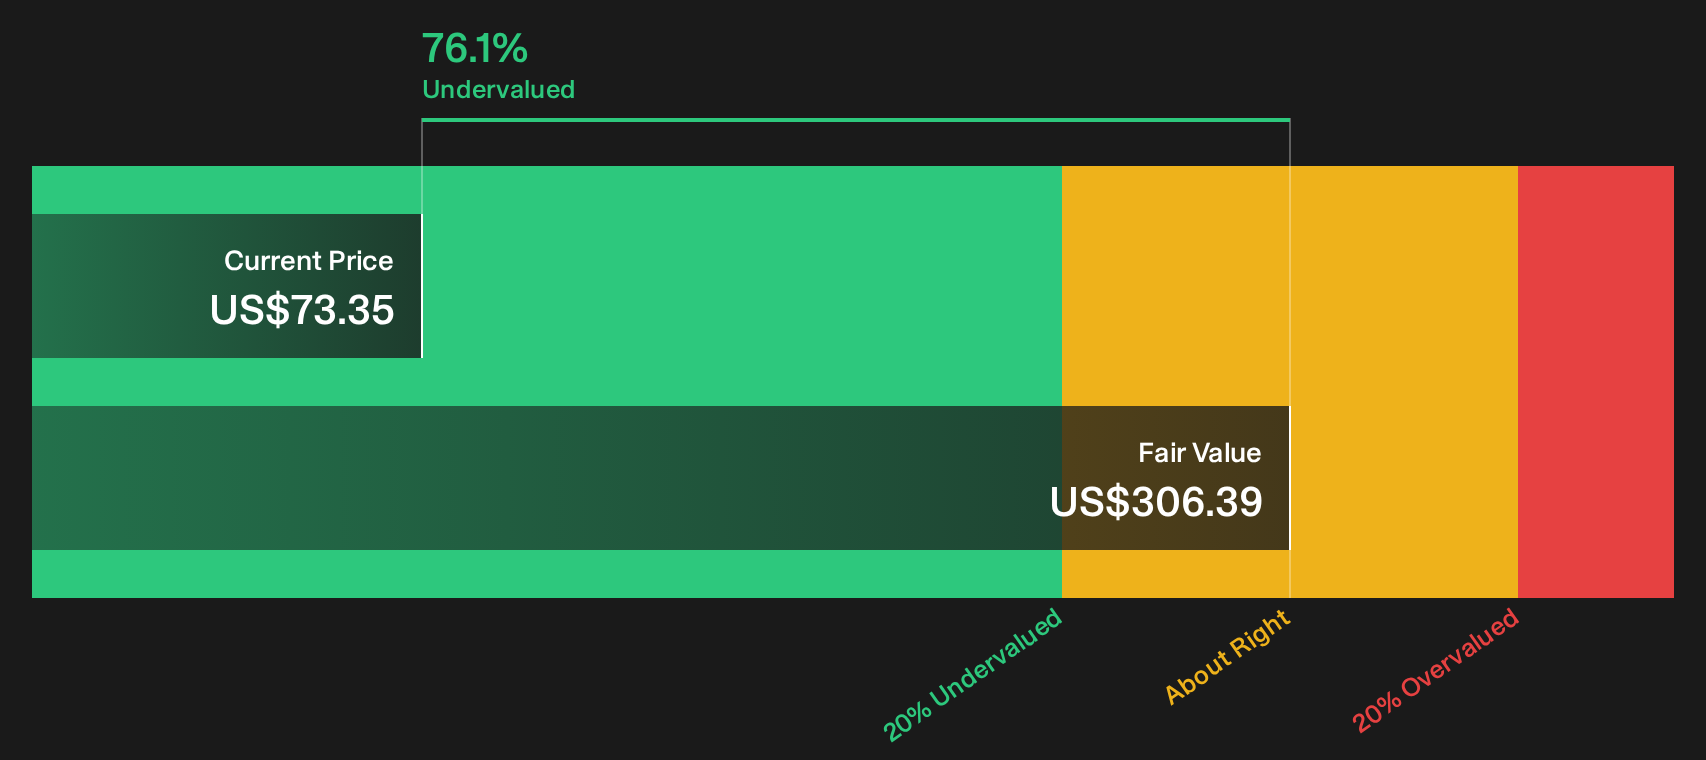
The DCF work suggests Corcept Therapeutics is deeply undervalued, with the share price of $73.35 trading 76.1% below an estimated future cash flow value of $306.39. Yet the P/E ratio tells a cooler story, at 50.4x versus a fair ratio of 40.5x and a US Pharmaceuticals average of 15.2x. That mix of apparent upside on cash flows and rich earnings multiple raises a simple question for investors: which signal carries more weight for you right now?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals like these often split opinion, so move quickly, review the underlying numbers for Corcept Therapeutics, and weigh both sides of the story. To frame that decision against the key concerns and bright spots investors are already focused on, start with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Corcept Therapeutics?
If Corcept Therapeutics has your attention, do not stop here. Broaden your watchlist with other opportunities that match your risk, income, and quality preferences.
- Target fresh upside potential by scanning our 20 high quality undiscovered gems and see which under-followed companies have numbers that genuinely back their story.
- Lock in stronger sleep-at-night potential by using the 30 resilient stocks with low risk scores to focus on businesses with sturdier risk profiles than the broader market.
- Strengthen the quality of your portfolio by filtering for resilient balance sheets through the list of solid balance sheet and fundamentals (24 results) before capital rushes to the same ideas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com