
Alignment Healthcare (ALHC) Raised Guidance Following Mixed Earnings, Is It 38% Undervalued?
Alignment Healthcare earnings jolt investor focus
Alignment Healthcare (ALHC) has drawn fresh attention after third quarter 2026 results showed revenue of US$1.36b with a swing to a quarterly net loss alongside higher full year revenue guidance.
The earnings update and raised full year guidance have arrived after a tough stretch for Alignment Healthcare shareholders, with the share price down 43.27% over 90 days and the 1 year total shareholder return falling 53.46%, even though the 3 year total shareholder return is positive at 16.74%.
Scan how other healthcare and senior-care insurers are reacting to similar earnings swings by reviewing our hand picked 36 healthcare AI stocks alongside Alignment Healthcare.
After a sharp drop in Alignment Healthcare’s share price and a wide gap between today’s US$7.67 level and published value estimates, the real tension is simple: Are investors overreacting or are the models too generous?
Most Popular Narrative: 38% Undervalued
Against Alignment Healthcare’s last close at $7.67, the analyst consensus Narrative on Simply Wall St anchors its fair value at $12.31, which points to a sizeable valuation gap based on analysts’ cash flow and earnings forecasts.
The company is investing in AI driven risk stratification, Care Anywhere clinical teams, automation and the Facets claims system migration to increase auto adjudication and payment integrity. These initiatives are aimed at lowering administrative intensity and improving net margins over time.
See why 15 investors see Alignment Healthcare as 38% undervalued.
Result: Fair Value of $12.31 (UNDERVALUED)
Still, the Alignment Healthcare story can break if Medicare Advantage reimbursement or star ratings tighten further, and if competition pushes acquisition costs higher and squeezes future profitability.
Find out about the key risks to this Alignment Healthcare narrative.
Another View: Alignment Healthcare on earnings multiples
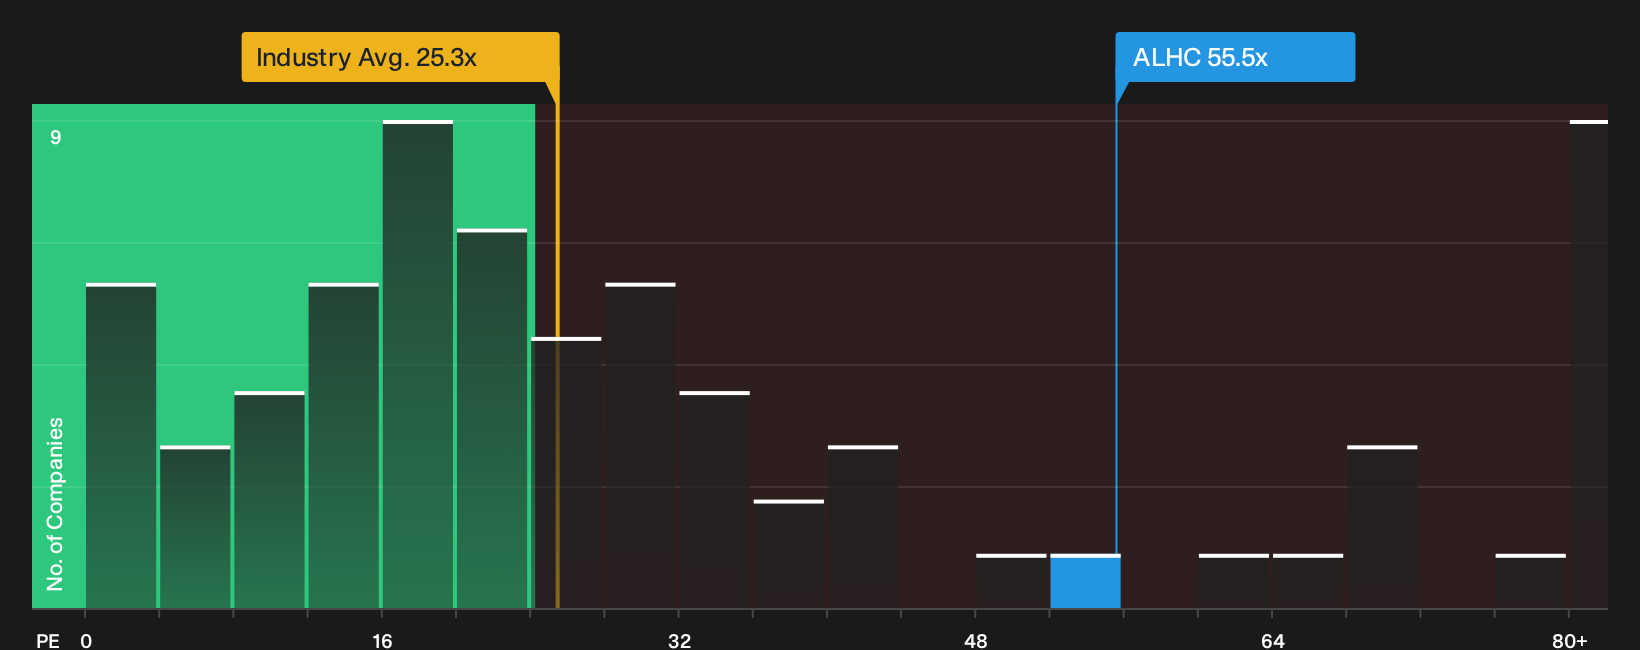
There is a catch. While the Simply Wall St narrative leans on discounted cash flows to frame Alignment Healthcare as undervalued, the current P/E of 55.5x looks rich next to the US Healthcare sector at 25.3x, the peer group at 30.1x, and even a fair ratio estimate of 47.6x. That kind of gap can either compress quickly or stay stretched much longer than expected, so which risk is more important to you right now?
To see how that valuation gap looks when you line it up against earnings, sector peers and a fair ratio the market could move towards, have a look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the push and pull in the Alignment Healthcare story feels unresolved, treat that as your cue to move fast and test the data yourself. The business carries both risks that investors are worried about and potential rewards that others are leaning into, so weigh them side by side with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Alignment Healthcare?
If Alignment Healthcare has sharpened your focus, now is the time to widen your watchlist and pressure test fresh ideas before the next wave of earnings hits.
- Target potential mispricing by scanning a 36 high quality undervalued stocks that filters for quality businesses whose market prices differ from their fundamentals.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that screens for companies with stronger risk profiles than the broader market.
- Spot early opportunities by checking a 20 high quality undiscovered gems that focuses on fundamentally solid stocks that receive less mainstream attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com