
GeneDx (WGS) Stock Seems In Line After New Testing Program Deal
GeneDx Holdings has seen its share price swing sharply in recent years, which puts fresh focus on whether today’s valuation lines up with the revenue the business is actually generating. With the stock moving around recent news in genetic testing partnerships, the question for you is how much of GeneDx’s sales story is already embedded in the current price.
- Over the past three years the stock has delivered a very large gain. As a result, a lot of past optimism is now riding on whether the company’s sales footprint can justify that journey.
- The recent collaboration with Mirum Pharmaceuticals to offer sponsored exome testing programs may support expectations for broader testing volume and potential future revenue, which directly feeds into how investors frame GeneDx’s sales base against its market value.
- The analysts covering GeneDx Holdings have run their own numbers. See what analysts think GeneDx Holdings's shares could be worth.
The issue now is whether GeneDx’s current share price is adequately supported by the level and trajectory of its sales.
If you want more context around where GeneDx sits on the risk and reward spectrum, a focused stock screen built around 30 resilient stocks with low risk scores can be a useful second starting point for research.
Does GeneDx Holdings Look Fairly Valued on Sales?
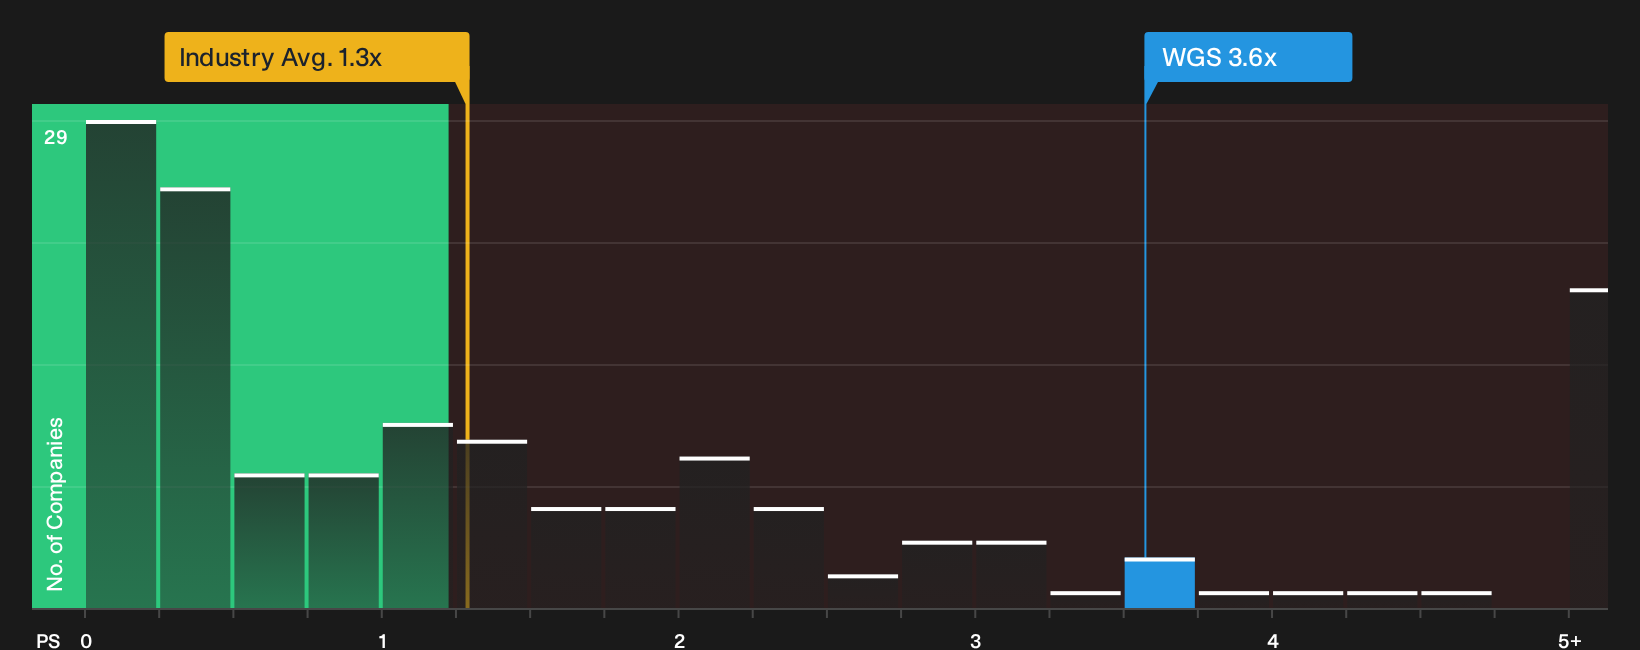
P/S is often a better fit for a business like GeneDx Holdings that is still working through losses and reinvestment, because it anchors the valuation to revenue rather than earnings. The stock trades at a P/S ratio of 3.6x, compared with a broader healthcare industry level of 1.3x and a peer group average of 0.8x. This means the market is attaching a richer tag to each dollar of GeneDx’s sales than to many comparable companies.
The tailored fair P/S level implied by the model comes out close to where GeneDx currently trades, so the ratio screens as about right rather than clearly cheap or expensive on this metric. Because the Mirum Pharmaceuticals collaboration relates to potential testing volume and revenue opportunities, investors appear comfortable paying this higher sales multiple relative to the sector. To judge whether that premium holds up, you would need to weigh the durability of GeneDx’s revenue model, its path toward cash flow, and how much execution risk you think is embedded at 3.6x P/S. Explore the numbers behind GeneDx Holdings's P/S valuation.
The GeneDx Holdings Narrative: What Would Justify Today's Price?
Narratives pick up where the P/S puzzle for GeneDx Holdings leaves off, by spelling out the specific assumptions on growth, margins and earnings that would need to hold for the stock to be worth significantly more or less than today’s price. They sit on Simply Wall St’s Community page. Instead of a single model output, they show the future scenario that number relies on, so you can watch how reality lines up over time.
One of the top narratives on GeneDx Holdings: 41% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is GeneDx converting improved payer coverage and low outpatient collection rates into higher realized reimbursement as it expands…"
Discover why this Narrative puts GeneDx Holdings at 41% undervalued.
One more GeneDx Holdings check that belongs next to the price tag
There is a separate lens that sits outside today's P/S comparison, which is where professional analysts currently expect GeneDx Holdings to be a few years from now on revenue and profits. Explore where analysts expect GeneDx Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com