
Is Onto Innovation (ONTO) Undervalued On Strong Q3 Results And Raised Guidance?
Onto Innovation (ONTO) is back in focus after reporting third quarter 2026 results that topped its own guidance, fueled by strong demand tied to AI, high performance computing and advanced packaging tools.
Despite the strong third quarter update, Onto Innovation’s share price has retreated sharply in recent months, with a 30 day share price return down 32.9% and a 90 day move down 41.5%, even as the year to date share price return sits at 19.1% and the 1 year total shareholder return is 48.0%. This points to longer term holders still sitting on solid gains, while near term momentum has clearly cooled.
Scan how Onto Innovation’s AI driven momentum compares to other chip suppliers by moving through a hand picked set of 53 AI infrastructure stocks in the same critical build out chain.
The share price reset and the spread between Onto Innovation’s US$197.51 quote, analyst targets and intrinsic value estimates now pull in different directions. Where does fair value actually land inside that gap?
Most Popular Narrative: 48% Undervalued
On the Simply Wall St platform, the leading narrative pegs Onto Innovation’s fair value at $380, well above the last close of $197.51. This frames the recent selloff as a valuation gap rather than a broken story.
According to FundamentalFlow, an investor in the Simply Wall St Community who wrote the narrative on Onto Innovation, the opportunity sits squarely in advanced packaging and process control rather than the headline grabbing GPU tier.
Onto Innovation is emerging as one of the most strategically important semiconductor equipment companies in the AI supply chain. While much investor attention remains focused on GPU manufacturers and memory suppliers, the next bottleneck increasingly lies in advanced packaging, the complex process of stacking, connecting, and inspecting AI chips and HBM memory at nanometer precision.
See why 38 investors see Onto Innovation as 48% undervalued.
Pulling the threads together, the narrative applies an implied fair value of $380 per share. This aligns with a view that Onto Innovation could justify a valuation similar to larger process control peers if AI packaging, HBM exposure and TSMC qualified tools all translate into sustained growth and profitability over time.
Result: Fair Value of $380 (UNDERVALUED)
Still, the Onto Innovation narrative could be shaken if advanced packaging capex slows materially, or if larger rivals seize key metrology wins at leading fabs.
Find out about the key risks to this Onto Innovation narrative.
Another View: Onto Innovation Through a P/E Lens
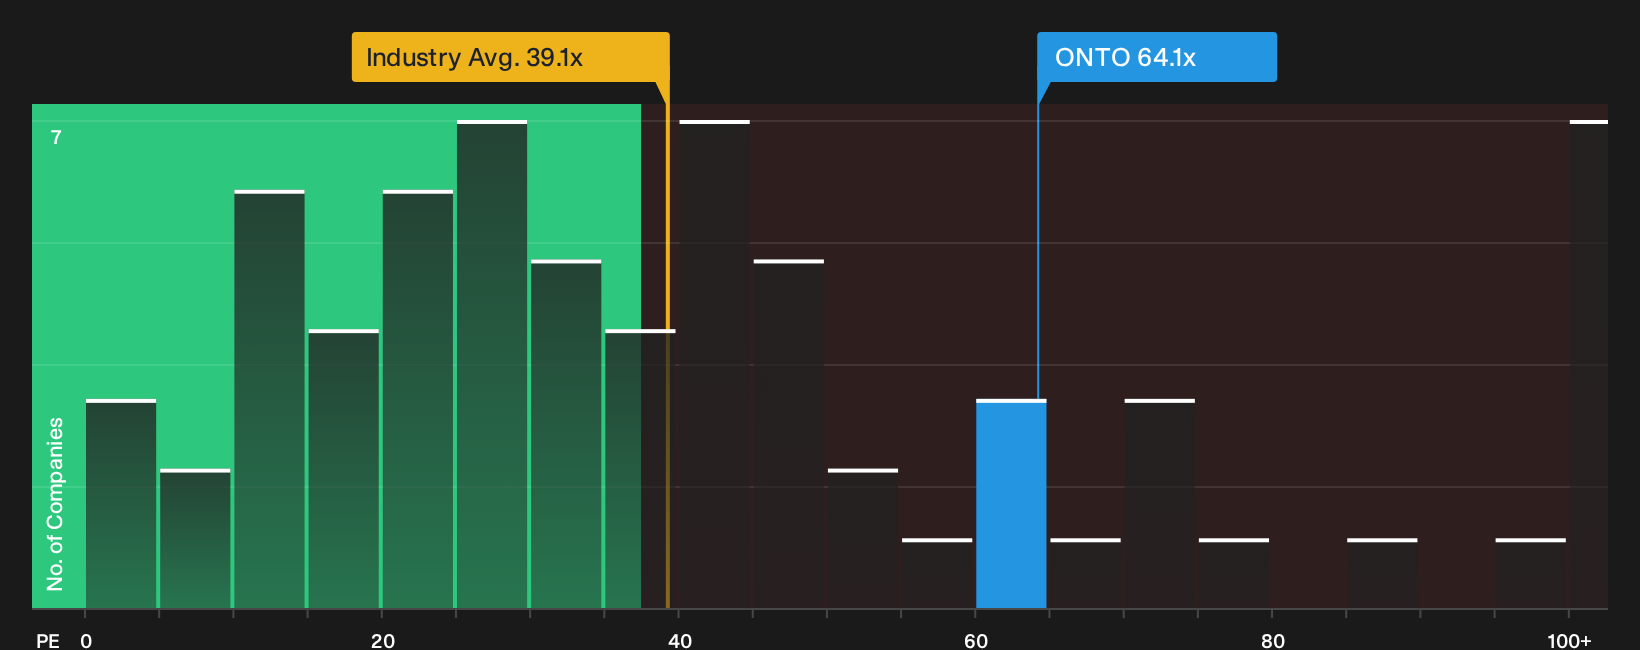
Onto Innovation appears inexpensive relative to that $380 narrative fair value, yet the market is already paying a high P/E for the shares. ONTO trades on 64.1x earnings versus a US Semiconductor average of 39.1x and a fair ratio of 52.5x. This points to valuation risk if expectations slip. Is this pricing in potential future success early, or simply stretching the story too far?
See what the numbers indicate about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about what all this means for Onto Innovation? Move quickly from opinion to evidence by reviewing the full risk and reward picture with 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Onto Innovation?
If Onto Innovation’s setup has you thinking bigger, you can use the same structured approach to scan other opportunities before the next wave of capital moves past you.
- Target strong balance sheets and resilient fundamentals by running your own filter through the Simply Wall St list of solid balance sheet and fundamentals (24 results).
- Spot potential mispriced opportunities early by screening for quality companies on the Simply Wall St 35 high quality undervalued stocks.
- Build a more income focused portfolio by scanning for reliable payers using the Simply Wall St 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com