
Via Transportation (VIA) Could Be 24% Below Fair Value After Earnings Update
Via Transportation (VIA) put fresh numbers on the table on November 9, reporting third quarter 2026 earnings that paired higher sales with a smaller net loss and updated full year revenue guidance.
That earnings update landed after a powerful run in Via Transportation’s shares, with a 1-day share price return of 4.94% on November 8, capping a 7-day move of 22.5%, a 30-day gain of 37.94% and a 90-day share price return of 78.24%. At the same time, the 1-year total shareholder return is still down 8.78%, which suggests momentum has recently accelerated while longer term holders remain under water and are still watching to see if improving fundamentals sustain this shift.
Scan how Via Transportation compares with other fast moving software and transit platforms by reviewing our curated list of 20 high quality undiscovered gems today.
Bulls point to Via Transportation’s fast revenue climb and shrinking losses. Bears focus on the still sizable red ink and sharp share price jump. Which story does the current valuation actually support?
Most Popular Narrative: 72% Overvalued
On the bearish analyst Narrative on Simply Wall St, Via Transportation’s fair value sits at $26 per share, well below the last close of $44.65. This frames a wide gap between market optimism and that downside scenario.
The main thing that has to go right is that Via Transportation turns its growing base of large network contracts, strong retention metrics and AI driven productivity tools into sustainably higher margins without eroding public sector relationships.
The current valuation implies that Via Transportation will justify a premium software multiple despite ongoing securities fraud scrutiny, reliance on public funding and a stock price that remains below its IPO level after significant volatility.
See why 0 investors see Via Transportation as 72% overvalued.
Result: Fair Value of $26 (OVERVALUED)
Still, the bearish story could fray if Via Transportation continues to convert its reported US$700 million plus pipeline and expand higher margin AI Labs projects across more cities.
Find out about the key risks to this Via Transportation narrative.
Another View: Via Transportation Through A Cash Flow Lens
The bearish analyst narrative pegs Via Transportation at $26 per share, yet Simply Wall St’s DCF work points in a different direction. On that model, VIA at $44.65 trades about 24% below an estimated future cash flow value of $59.03. Which anchor matters more for you: earnings scenarios or long term cash generation?
For a closer look at how that cash flow based estimate is built and what assumptions sit underneath it, read through the Look into how the SWS DCF model arrives at its fair value.
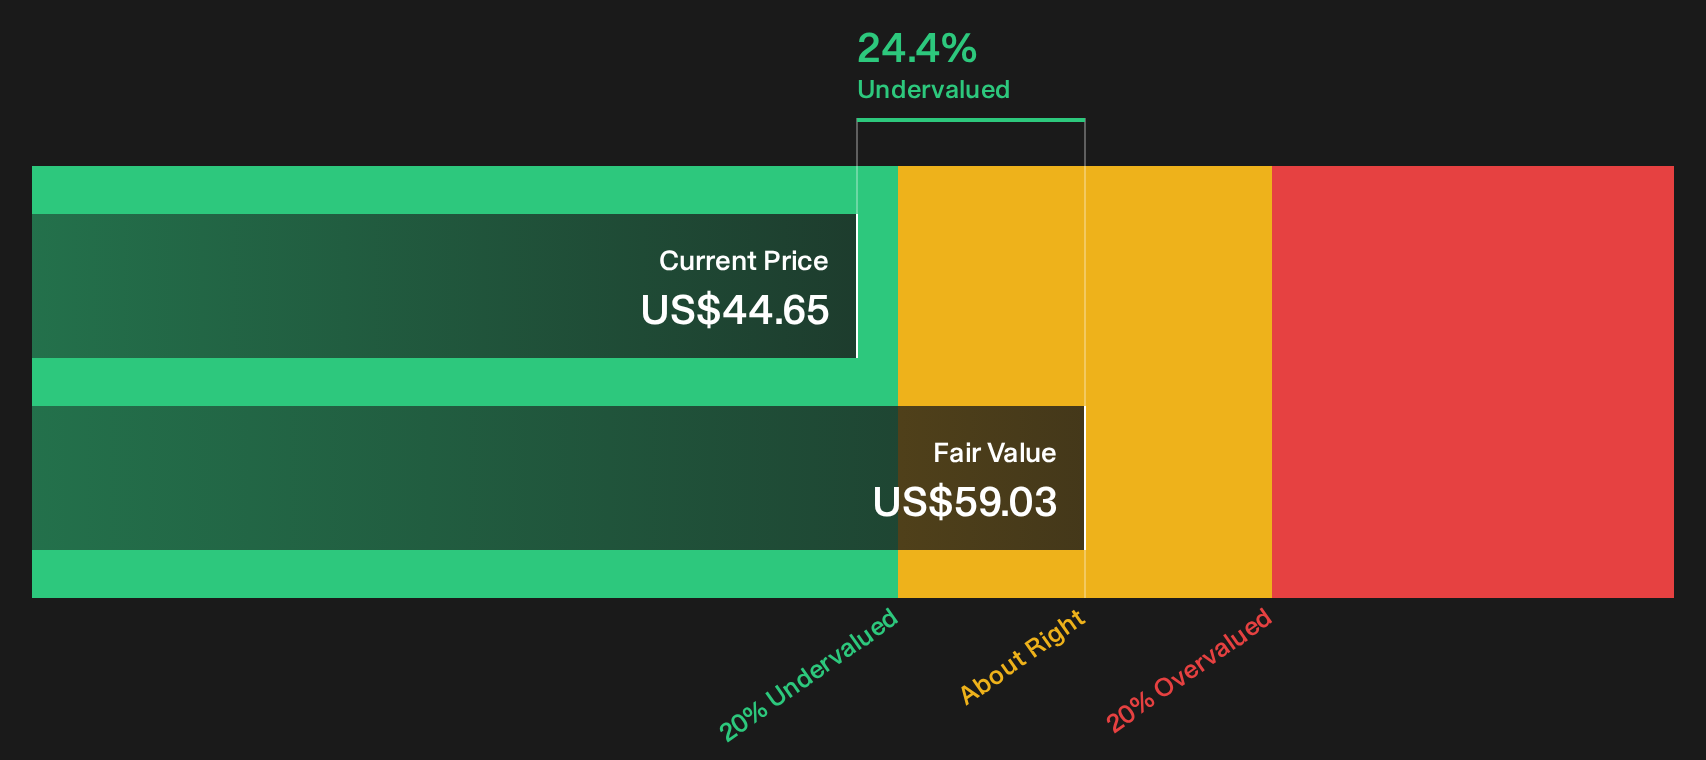
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Via Transportation for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the mix of caution and optimism around Via Transportation? Act quickly, review the data for yourself, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Via Transportation?
If Via Transportation has your attention, do not stop there. Use the Simply Wall St screener to quickly surface other potential opportunities that might fit your style.
- Target future compounding by hunting for companies that combine quality and value through our curated 35 high quality undervalued stocks.
- Prioritize sleep-at-night resilience by focusing on businesses with strong finances in the list of solid balance sheet and fundamentals (24 results).
- Strengthen your income stream by reviewing potential high-yield opportunities in the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com