
AI Storage Partnership Might Change The Case For Investing In NetApp (NTAP)
- NetApp reported that Nebul, a European AI native cloud provider, has become the first neocloud to adopt NetApp Novus, its new high performance storage architecture for zettabyte scale AI workloads aimed at secure, multi tenant environments and regulated industries.
- The collaboration highlights NetApp's push into AI ready infrastructure for sovereign European workloads, using Novus to focus on GPU utilization, data governance, and control for large scale AI factories.
- This analysis examines how NetApp's investment narrative is shaped by the Nebul Novus deployment aimed at sovereign European AI workloads.
NetApp Investment Narrative Recap
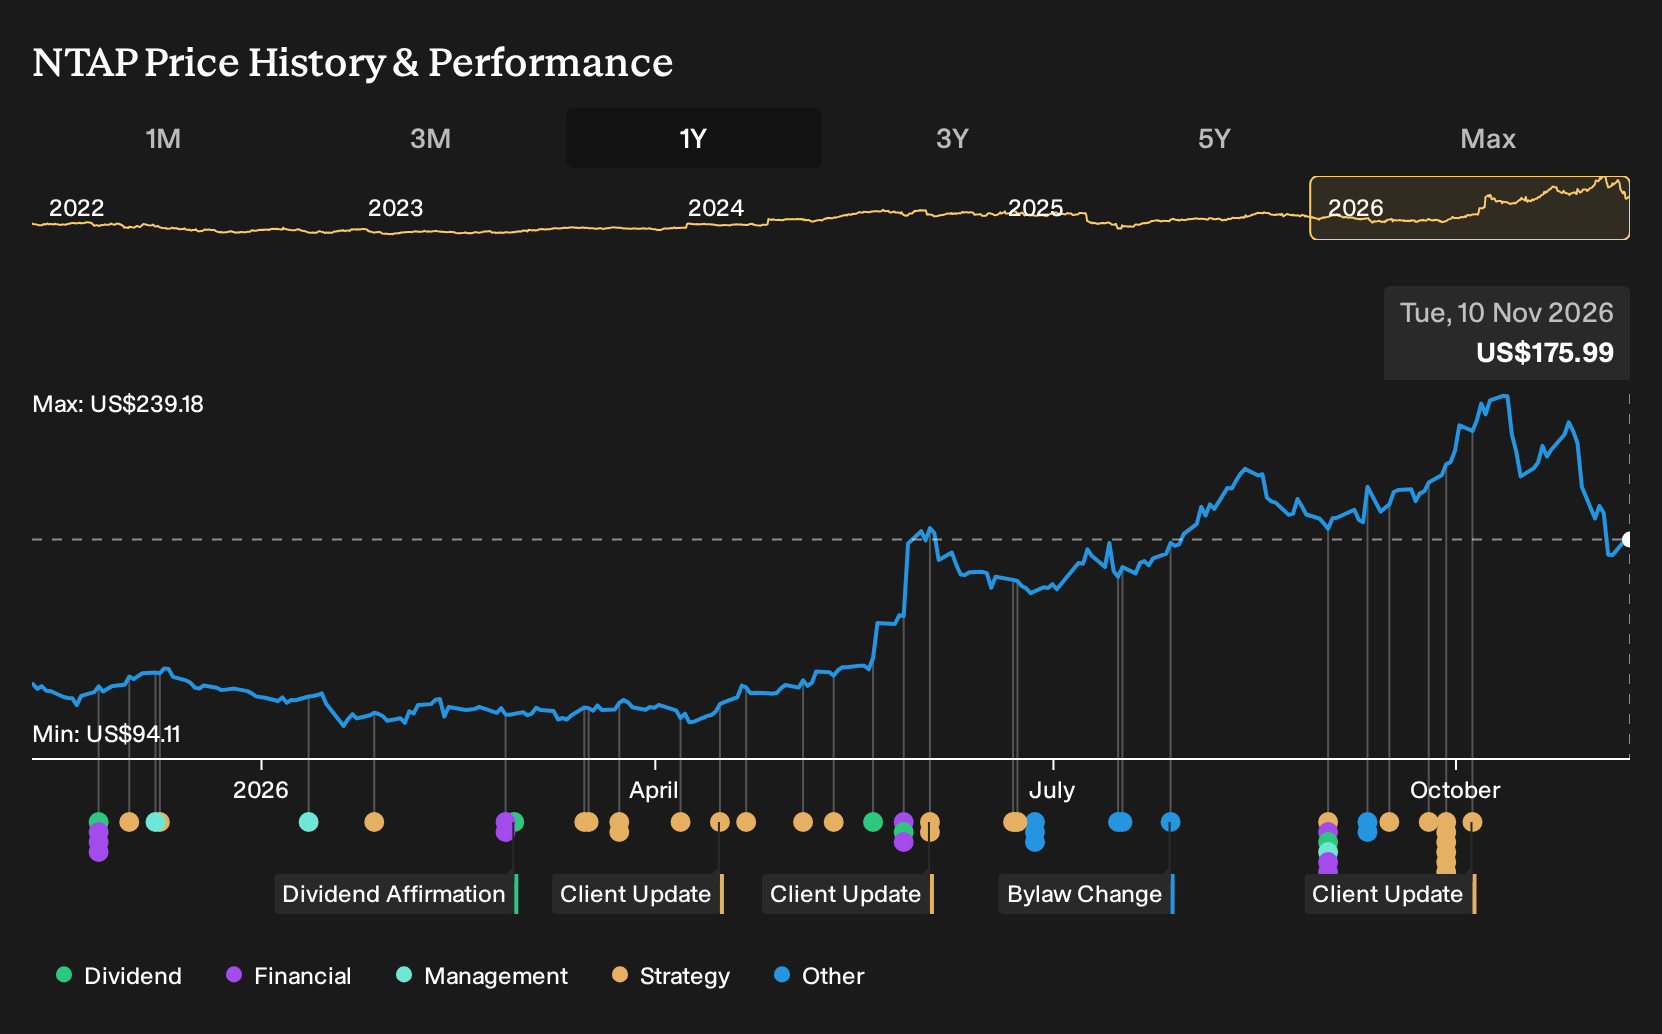
To be a shareholder in NetApp, you need to believe the business can keep turning AI and hybrid cloud demand into durable, high margin data platforms. The analyst consensus Narrative on Simply Wall St points to AI driven storage and cloud usage as key supports for revenue and earnings. The Nebul Novus deployment fits that view but on its own does not look like a material near term swing factor.
The more immediate catalyst sits around execution on AI ready offerings and cloud services, with Q2 FY27 results on December 1 likely to frame how well that is tracking. The biggest operational risk remains pressure on product gross margin from component costs and the elevated inventory position if AI and storage demand do not absorb those commitments.
The upcoming Q2 FY27 earnings release is the announcement that matters most in the context of the Nebul news. Management is scheduled to update investors on revenue, margins and AI related deal activity. That information may help you judge whether deployments like Nebul are feeding into broader Public Cloud and Hybrid Cloud performance or are still early stage references.
If the call highlights more AI factories, cloud integrations and subscription models such as Keystone Sovereign and Novus based offerings, that would speak directly to the catalysts in the analyst consensus Narrative on Simply Wall St. Any renewed focus on component costs, inventory or hardware valuation worries would lean into the existing margin and sentiment risks already flagged for NetApp.
NetApp's current earnings of US$1.4b are projected by analysts to reach US$1.9b by 2029, which is an increase of about US$0.5b. Their narrative also assumes revenue growth of 8.6% per year, leading to forecast revenue of US$9.5b and projected earnings of US$1.9b in 2029.
Uncover why NetApp's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on concentration risk. The most cautious NetApp analysts worry that large AI and sovereign cloud deals could prove stop start, with their models only banking around 5.1% annual revenue growth and earnings of about US$1.7b by 2029. Those forecasts came before the Nebul Novus news, so expect opinions to evolve and vary widely.
Explore 3 other NetApp fair value estimates, including one that suggests it could be worth just $211.69!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NetApp research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NetApp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NetApp's overall financial health at a glance.
Looking For More Ideas Beyond NetApp?
Once you have formed a view on NetApp, it can help to cross check that thesis against other companies with different risk and return profiles using the Simply Wall St Screener.
- If capital preservation matters most to you, start with resilient businesses in our 30 resilient stocks with low risk scores that score well on stability.
- For investors who care about quality at a reasonable entry point, the 35 high quality undervalued stocks can surface companies with solid fundamentals trading below estimated fair value.
- If you want to focus on balance sheet strength, filter for companies through the list of solid balance sheet and fundamentals (24 results) that pair low leverage with healthy financial ratios.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com