
Should Softer October Sales Require Action From LCI Industries (LCII) Investors?
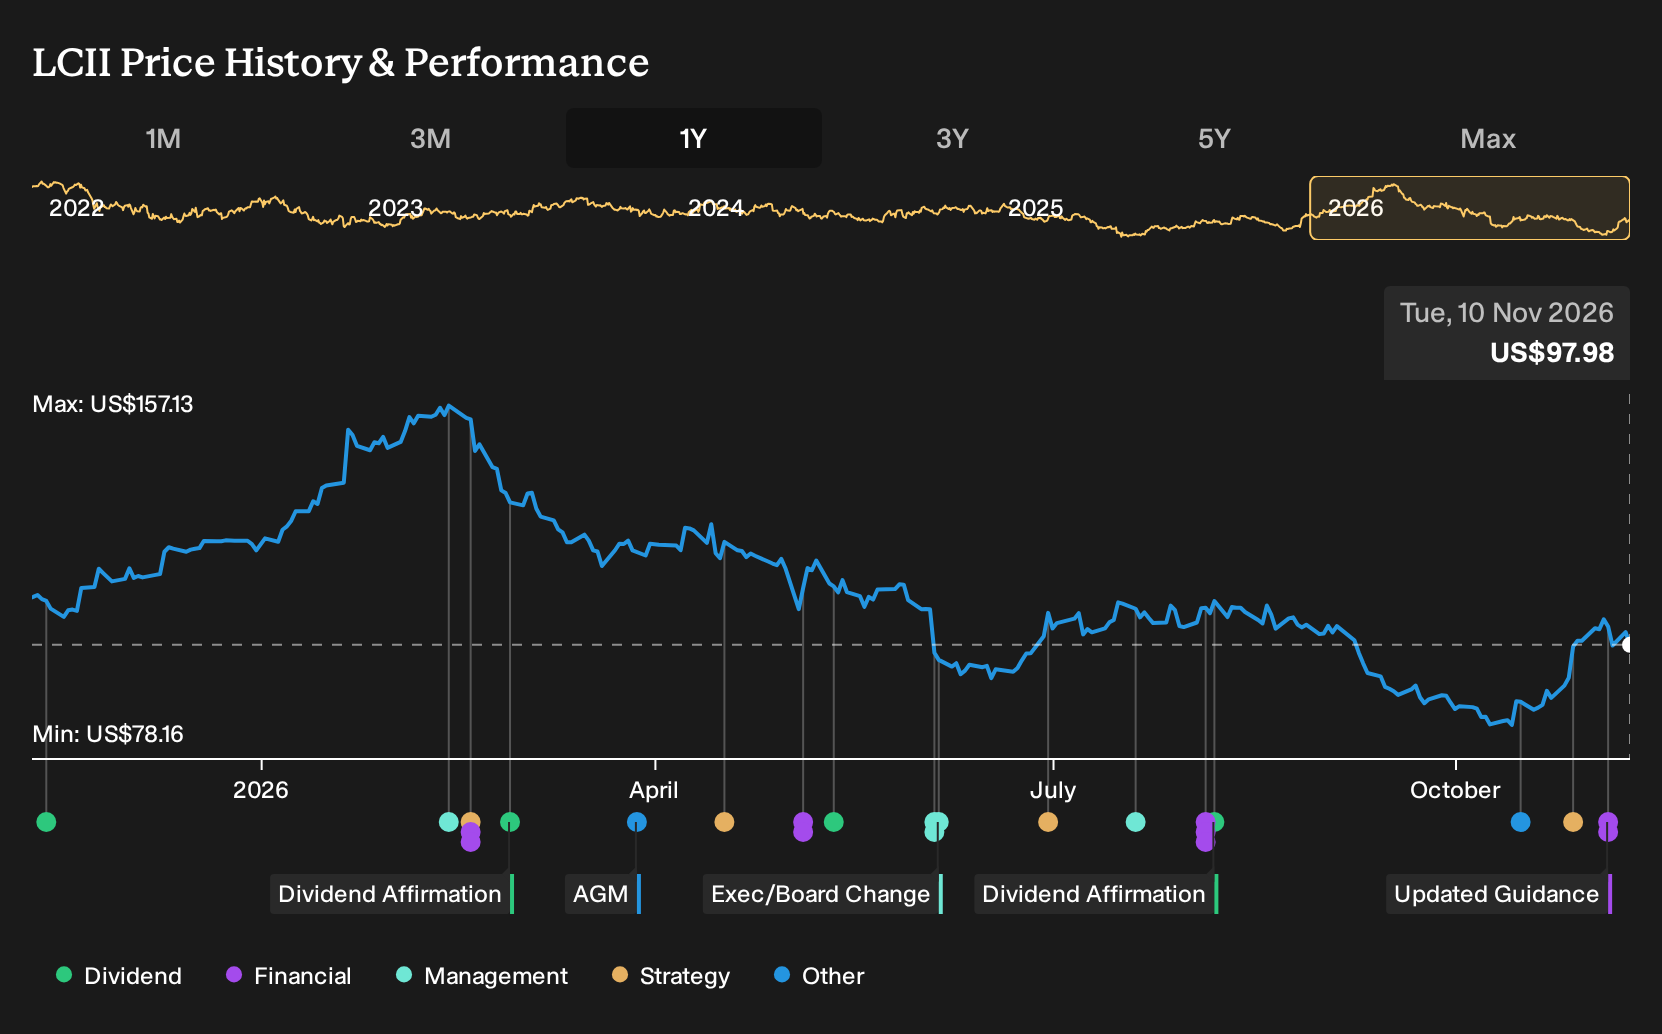
- LCI Industries reported third quarter 2026 sales of US$992.48 million and net income of US$50.09 million, with earnings per share from continuing operations slightly lower than the same period a year earlier.
- Over the first nine months of 2026, LCI Industries recorded sales of US$3.05 billion and higher net income year on year, while issuing full year revenue guidance of US$3.9 billion to US$4.0 billion, along with an expected 10% decline in October net sales compared with the prior year.
- We will now examine how LCI Industries’ softer October sales outlook could influence the existing investment narrative around diversification.
LCI Industries Investment Narrative Recap
For an investor to stay with LCI Industries, the core belief is that diversification beyond the RV cycle, higher content per unit and aftermarket exposure can offset choppy OEM demand. The third quarter update, with modestly lower quarterly earnings and the softer October sales outlook, points to pressure on near term orders rather than a break in that broader thesis.
Right now, the key short term catalyst is execution on cost optimisation and facility consolidation to protect margins as volumes soften. The biggest risk remains exposure to a weaker North American RV market, and this earnings print reinforces that sensitivity but does not materially change the diversification story described in the analyst consensus Narrative on Simply Wall St.
The new full year revenue outlook of US$3.9b to US$4.0b is the announcement that matters most here. It frames the October sales softness inside a clearer 2026 run rate and provides a basis to judge whether diversification into marine, transportation, housing and Europe is doing enough work against a cooler RV cycle.
That same update also arrives alongside higher year to date net income despite slightly lower nine month sales. This links directly to the self help margin and cost actions in the analyst consensus Narrative on Simply Wall St. The operational question now is whether further facility consolidation and aftermarket mix can offset any prolonged pressure on OEM demand and input costs.
LCI Industries' narrative projects US$4.2b revenue and US$245.1 million earnings by 2029. This assumes 1.4% yearly revenue growth and an earnings increase of about US$33.8 million from the current US$211.3 million level.
Uncover why LCI Industries' fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You also see a very different angle in the bearish LCI Industries narrative. Those analysts lean hard on continued RV OEM weakness and lower content trailers. Before this earnings release they were only baking in about 1.0% annual revenue growth to around US$4.2b and earnings of US$254.9 million by 2029. That is a far more cautious storyline. It shows how sharply views can diverge and why it can help to compare several forecasts and decide which assumptions you find more realistic after this new October guidance.
Explore 4 other LCI Industries fair value estimates, including one that suggests as much as 34% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your LCI Industries research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for LCI Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LCI Industries' overall financial health at a glance.
Looking for more investment ideas beyond LCI Industries?
If this LCI Industries update has sharpened your thinking and you want to stress test that view against other opportunities, the Simply Wall St Screener lets you quickly filter for companies that match the balance of quality, valuation and resilience you care about most.
- For investors who want quality at a discount, consider starting with companies that look attractively priced on both fundamentals and balance sheet strength by scanning through 35 high quality undervalued stocks.
- If resilience matters most to you, focus on businesses with steadier financial profiles and fewer red flags across debt and cash flow by reviewing a 30 resilient stocks with low risk scores.
- When you want ideas that stay off the usual radar yet still have solid metrics, widen your watchlist with a carefully filtered 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com