
How Upcoming Earnings Will Impact EZCORP (EZPW) Investors
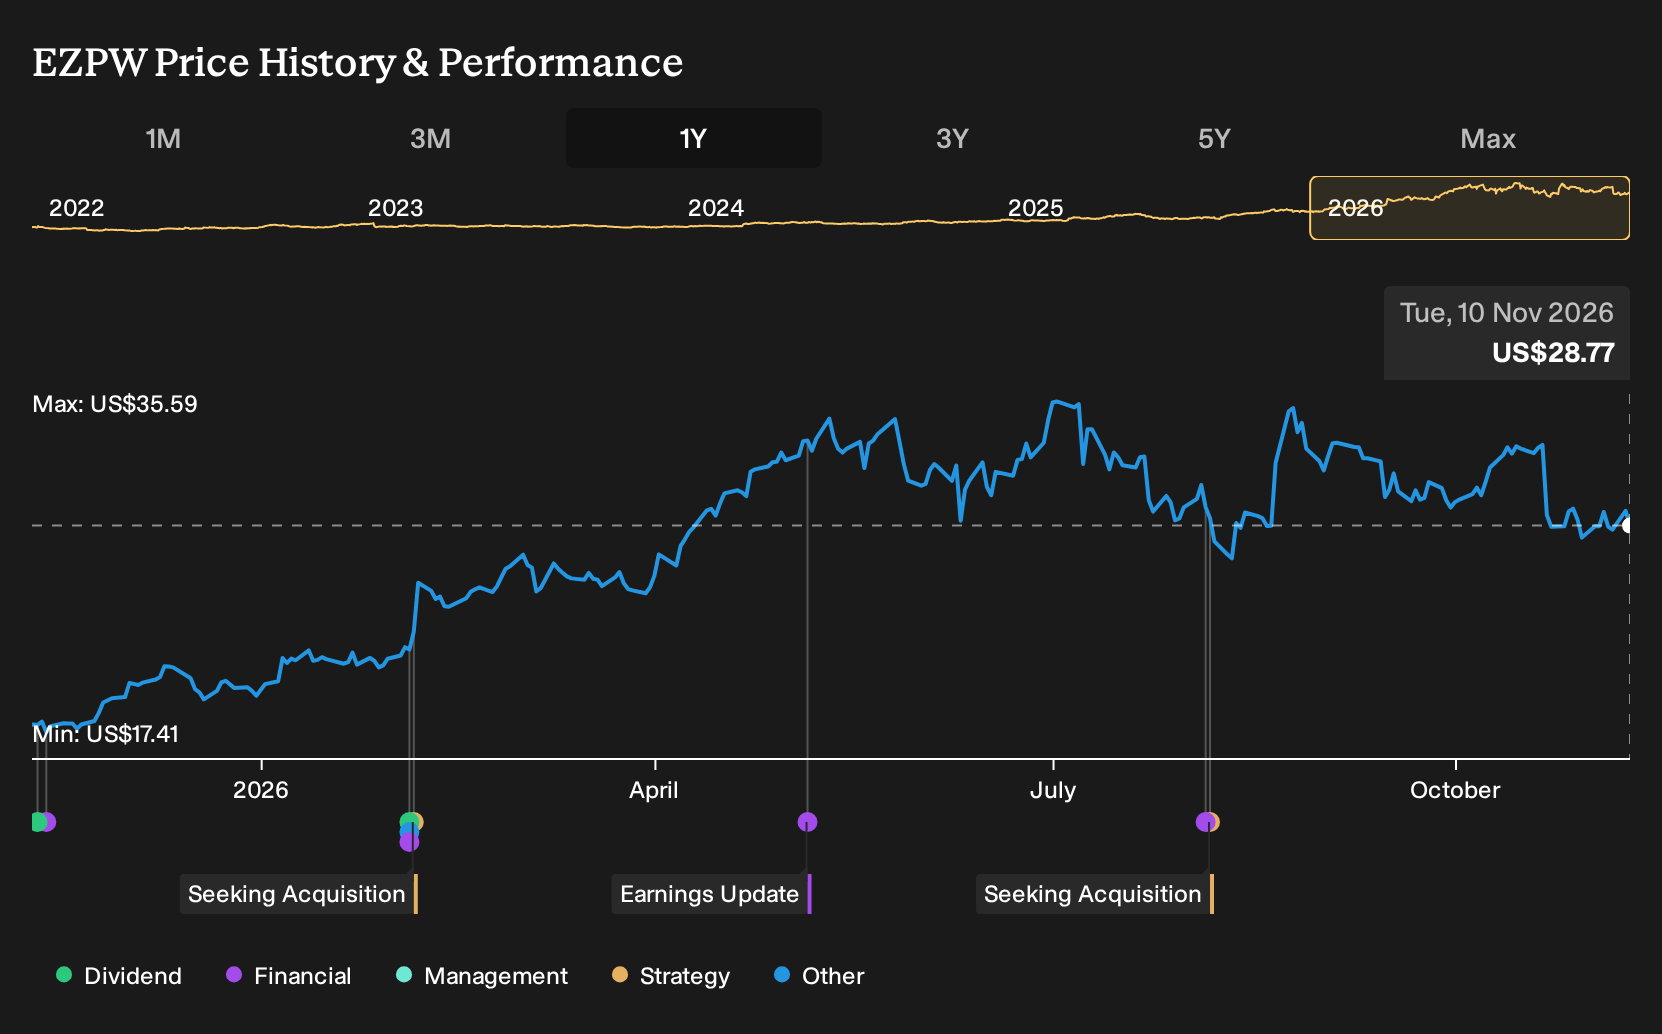
- EZCORP plans to report Q4 2026 results after the market close on 11 November, with analysts expecting EPS of $0.40 and revenue of $422.4 million.
- Consensus forecasts indicating a 17.7% EPS increase and 25.4% revenue growth year over year describe how pawn demand is shaping EZCORP's current earnings power.
- We will now look at how EZCORP's investment narrative is influenced by these projected double-digit gains in earnings and revenue.
EZCORP Investment Narrative Recap
To own EZCORP, you need to be comfortable with a pawn-led model that leans on steady loan demand, disciplined merchandising and controlled store expenses. The key short-term swing factor is how Q4 pawn service charges and merchandise profits line up against rising labor and integration costs in the U.S. and Latin America. The upcoming report shapes sentiment but does not change that core thesis.
The biggest near-term risk sits in margins. Scrap gold profitability has already moved toward long-term levels, so any cooling in core pawn activity would put more pressure on EBITDA. At the same time, newer locations from recent acquisitions need to show they can support store-level economics without eroding group returns.
The analyst consensus narrative on Simply Wall St highlights consumer credit pressure and household budget strain as important drivers for pawn demand. EZCORP leans into that backdrop through its U.S. and Latin America pawn operations, where pawn loans, service charges and resale of forfeited goods all tie back to how customers are handling cash flow stress.
That same narrative points to Latin America expansion, acquisitions like SMG and the use of standardized operating playbooks as operational levers. For you, the upcoming Q4 print is essentially a check-in on whether those levers are translating into sustainable store profitability while regulatory risk around pawn fees and loan structures remains contained.
What The Long Range EZCORP Forecasts Assume
EZCORP's narrative projects US$2.0b revenue and US$216.4m earnings by 2029. That profile is built on analysts penciling in 8.7% yearly revenue growth and an earnings increase of about US$58m from US$158.3m today.
Uncover how EZCORP's fair value indicates a 42% potential upside to its current price before that discount to expectations starts to close.
Exploring Other Perspectives
One alternate take on EZCORP focuses less on pawn demand and more on acquisition risk. The most bearish analysts already saw store expansion as stretched, even while penciling in roughly US$2.1b of revenue and US$220.9m of earnings by 2029. With Q4 results landing soon, those views could shift sharply in either direction.
Explore 4 other EZCORP fair value estimates, including one that suggests as much as 21% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis and judgment.
- A great starting point for your EZCORP research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for EZCORP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EZCORP's overall financial health at a glance.
Looking For More Investment Ideas Beyond EZCORP?
Once you have a view on EZCORP, it can help to compare that thesis with other opportunities that have different risk, balance sheet strength and income profiles. The Simply Wall St Screener lets you scan the market quickly so you can back your own convictions with data instead of noise.
- If you want potential mispricing with quality behind it, review a curated set of companies flagged as a 35 high quality undervalued stocks that may offer stronger fundamentals than their current prices suggest.
- For investors who care most about resilience, focus on businesses with healthier finances using a list of solid balance sheet and fundamentals (24 results) to see which tickers carry less balance sheet strain.
- If you prefer opportunities that are less picked over, search for underfollowed stories through a 20 high quality undiscovered gems that highlight strong fundamentals where attention has yet to catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com