
Missed L.B. Foster's Run? What Holders Had To Believe
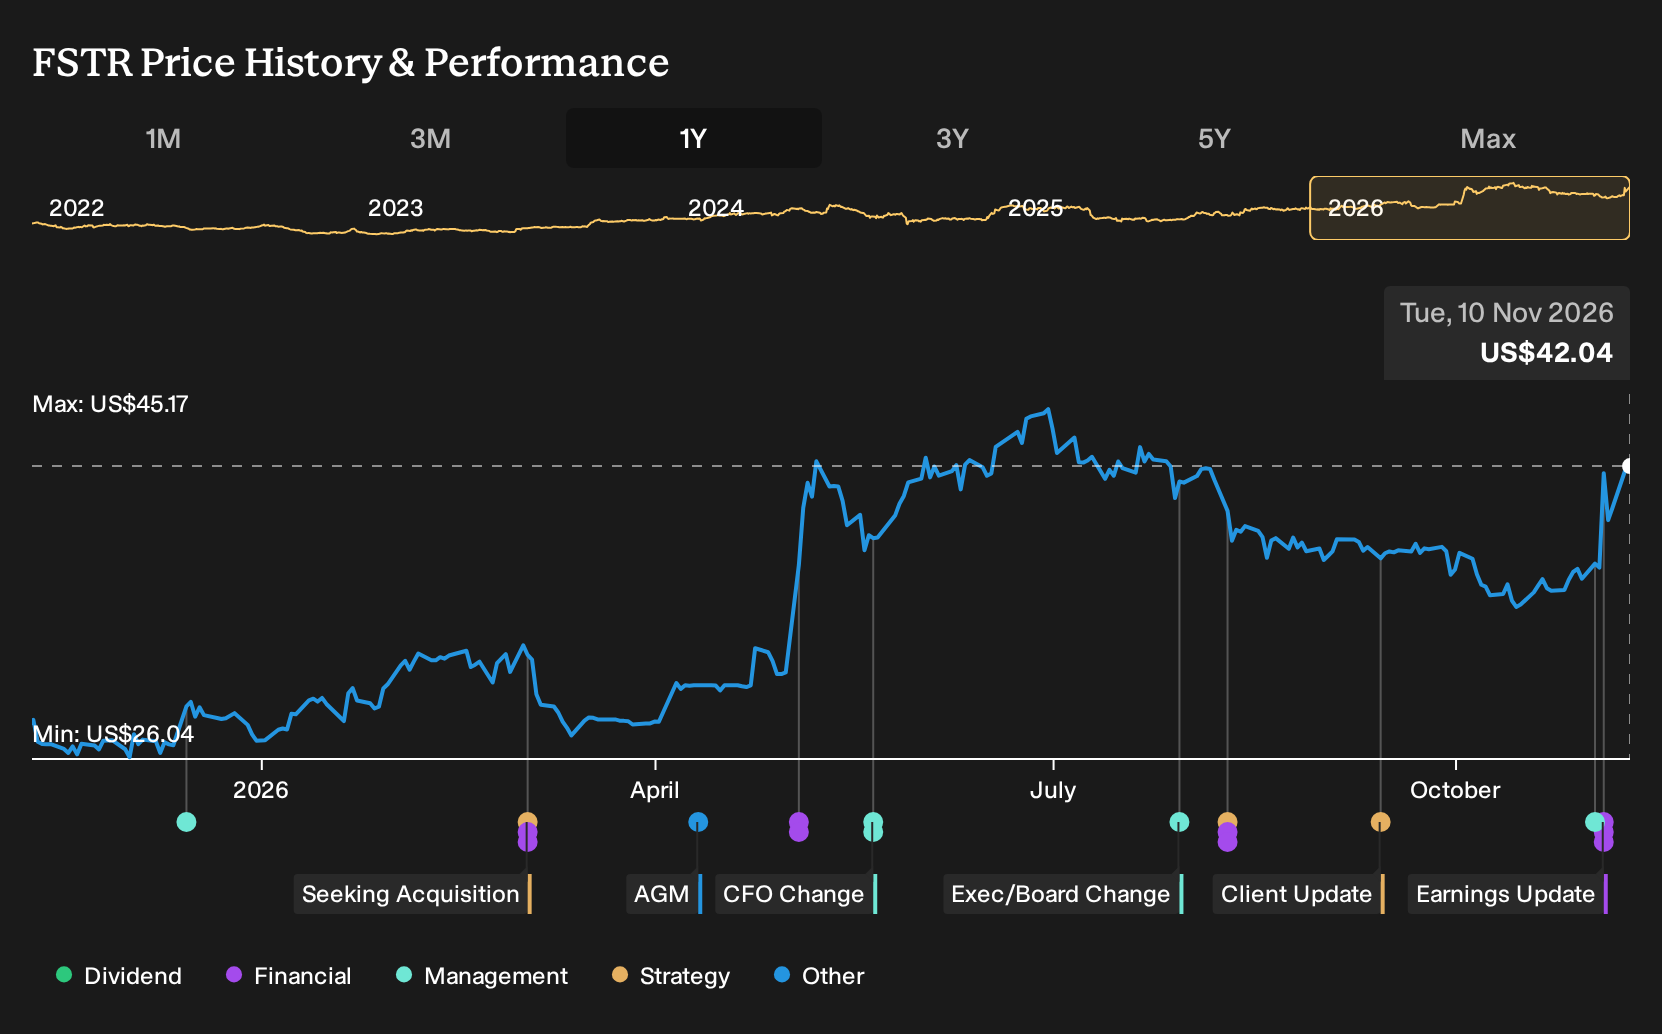
If you only glanced at the headlines, L.B. Foster might have appeared to be mainly a story of funding risk and rail cyclicality rather than a rewarding holding. Holding L.B. Foster over the past year would have returned 56.3%, including dividends. That outcome sits beside later evidence of higher quarterly revenue, rising profit, and a wider net margin, even though analysts had forecast shrinking earnings. If you were deciding back in November 2025, how would you have weighed those recorded risks against that eventual gain?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind L.B. Foster. Zero in on 35 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Weigh On L.B. Foster
The shares cost US$28.1 at the start of the period, and any investor looking at L.B. Foster then had to choose between two sharply different scripts that still sounded reasonable on their own terms.
On the optimistic side, one narrative saw Fair Value at US$33, built on government infrastructure programs and overdue rail modernization supporting 7.4% annual revenue growth assumptions and a future P/E of 31.1x on earnings of US$12.4 million.
The more cautious view put Fair Value at US$25, arguing that dependence on public funding, cyclical rail exposure, and raw material swings meant margins could shrink to 1.8% with earnings of US$10.8 million on a P/E of 26.9x.
What The Results Changed For The L.B. Foster Debate
The most concrete update for L.B. Foster came with Q3 2026 figures. Revenue was US$167.996m and net income was US$6.764m, compared with US$138.286m and US$4.354m in Q3 2025, and net margin moved from 3.1% to 4.0%. That pattern supported the optimistic script on revenue and profitability, although it did not prove that higher margins are permanent.
The lesson is simple. When a story leans on margin pressure or expansion, treat net margin as the key claim. Then track it quarter by quarter against that earlier script before updating your view.
What L.B. Foster's Recent Run Already Prices In
L.B. Foster now trades at US$42.04, and the bullish analyst Narrative on Simply Wall St places its Fair Value above that level, based on a different reading of the cash and margin story.
The Narrative leans on higher margin rail technologies and capital light cash generation. A buyer today would need to judge whether sustained free cash flow and mix shift can keep supporting that outcome.
"A key factor is that L.B. Foster continues to convert its capital light cash generation into sustained deleveraging and shareholder returns while executing the ongoing portfolio reshaping in the U.K. and Infrastructure businesses. The numbers suggest the share price reflects limited credit for L.B. Foster's cash generation, reduced leverage, and mix shift toward higher margin businesses, which supports the view that the stock may be undervalued on a fundamental basis."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond L.B. Foster
L.B. Foster is tied to rails and physical infrastructure. Your next question might be what keeps the data side running.
Every AI buildout leans on huge data centres that draw intense power. Those facilities depend on equipment staying cool and stable.
Another business focuses on the plumbing behind that problem. It designs power and thermal systems that let dense computing racks keep operating continuously.
Instead of venturing into chips, it tackles heat and energy. As AI workloads grow more demanding, that behind the scenes role could matter more.
That argument has a Narrative and a number behind it. → See the company one Narrative values 110% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com